

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pet Food Packaging Market to Reach USD 18.0 Billion by 2032 (5.7% CAGR)

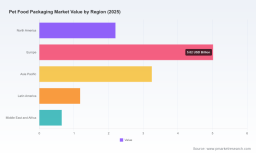
Pet Food Packaging Market 2026: Strategic Preview for Executive Decision-Making
Between 2020 and 2025 the pet food packaging market expanded materially, moving from a mid‑single‑digit billion-dollar base to a significantly larger industry by the 2025 base year. Our analysis forecasts continued expansion through the 2026–2032 horizon, with the market tracking a steady compounded annual growth rate (CAGR) of 5.7% and approaching the high‑teens billion‑dollar mark by 2032. For leadership teams planning capital allocation, product redesigns, or market entry in 2026, these headline dynamics create both opportunity and urgency.
Pet Food Packaging Market
Why this report matters for 2026 strategy cycles
- Timing of regulatory inflection points: New packaging regulations and expanding producer responsibility schemes in key markets mean compliance-driven redesigns and EPR cost exposures will crystallize in 2026–2027. Decisions made this year on material choices, recyclability pathways, and supplier contracts will lock in fee and waste-management outcomes for the next decade.
- Capitalizing on predictable growth: With a multi‑year growth trajectory and clear category tailwinds (premiumisation, convenience formats, and e‑commerce demand), firms that prioritize scalable, recyclable formats will capture disproportionate share without depending solely on price competition.
- Margin preservation under input volatility: Raw material price drivers—resins, paper, metal—continue to create margin variability. The right combination of design‑to‑cost, supplier hedging, and recycled-content sourcing is now a strategic must, not just an operational improvement.
- Competitive positioning vs. concentration: The market displays moderate concentration (CR3 ~37%; CR5 ~47%), indicating significant room for differentiated plays by regional specialists, sustainable innovators, and format disruptors.
What the full PW Consulting report provides (practical, decision‑ready content)
- Robust market model: Annual market sizing from 2020 through 2025, plus a granular forecast for 2026–2032 under base, upside, and downside scenarios—built to be plugged into your financial models.
- Actionable segmentation framework: Demand breakdowns by material families, packaging formats, and pet food types—framed to guide SKU rationalisation and capex planning (note: this preview omits detailed split figures; the full dataset is included in the report).
- Value‑chain cost maps: Line‑by‑line input cost drivers, transport and conversion margins, and sensitivity tables to quantify margin impact from raw material swings and recyclate price movement.
- Regulatory impact assessment: Scenario analyses of EU and US EPR timelines, expected eco‑modulation effects on producer fees, and compliance roadmaps for global and regional product portfolios.
- Supplier and capability matrix: A pragmatic vendor scorecard—technical, sustainability credentials, geographic coverage, and scale—that supports rapid shortlist creation for RFPs and strategic partnerships.
- Commercial playbooks: Go‑to‑market strategies for brand owners, private label operators, and converters focused on premiumisation, convenience (reclosability, spouts), and e‑commerce protection requirements.
- M&A and partnership diagnostics: Target archetypes, valuation multiples observed in adjacent packaging segments, and regulatory due diligence checklists that reflect the evolving circularity landscape.
- Implementation templates: Roadmaps for packaging trials, conversion timelines, cost‑benefit templates for mono‑material conversions, and a 12–24 month action plan to operationalise recyclable formats.
Competitive landscape — who matters and why
The pet food packaging ecosystem is served by a mix of global converters, regional specialists, and metal can manufacturers. The competitive set includes leaders that combine scale with innovation in recyclable, mono‑material and high‑barrier solutions. Key players profiled in the report include:
Pet Food Packaging Market
- Amcor plc (Zurich): A global supplier focusing on recycle‑ready flexible portfolios designed for wet and dry pet food. Amcor’s investments in heat‑seal and barrier technologies mean brand owners can target recyclability without sacrificing shelf life—important for premium wet formats.
- Huhtamaki Oyj (Espoo): Known for mono‑material and alu‑free solutions, Huhtamaki’s blueloop concept and retort pouch capabilities make it a strategic partner for customers wanting to reduce composite materials while preserving convenience attributes.
- UFlex Limited (New Delhi): A fast‑moving manufacturer offering a broad array of recyclable flexible formats. Recent trade show activity demonstrates a drive to capture demand from emerging markets and private label operators seeking cost‑effective, recyclable alternatives.
- Mondi plc (Vienna): Strong in sustainable mono‑material solutions for dry pet food. Recent product launches with brand partners signal that paper‑based and mono‑plastic replacements are commercially viable at scale where barrier performance is managed through design.
- Silgan Holdings Inc. (Norwalk): A leading metal container producer, Silgan is positioned to serve wet food and specialty segments where shelf stability, dosing, and perceived premiumity justify rigid formats and dispensing closures.
Recent company moves underscore strategic themes: product launches and trade show demonstrations illustrate an industry pivot toward recyclable mono‑materials and format diversity. These developments are not isolated PR— they reflect investment decisions that will shape supplier roadmaps and cost structures through 2028 and beyond.
Pet Food Packaging Market
Regulatory and raw‑material drivers shaping 2026 decisions
- European PPWR: With the Packaging and Packaging Waste Regulation entering into force and recyclability targets becoming binding by 2030, European market participants must accelerate redesigns and prepare for eco‑modulated EPR fees. This creates a near‑term window (2026–2028) for phased portfolio migration and supplier requalification.
- US packaging EPR expansion: Multiple US states have passed comprehensive EPR laws and others are considering bills. Producer responsibilities in these states are already changing packaging economics and will drive demand for recycled content and mono‑material approaches.
- Input commodity volatility: Paper, metal and various plastic resins remain principal cost determinants. The report’s sensitivity scenarios quantify how price shocks translate to pack‑level margin erosion and when to hedge versus redesign.
Strategic imperatives for leadership in 2026
- Prioritise portfolio triage: Identify SKUs where recyclability upgrades deliver the greatest EPR and brand value lift, and where rigid formats versus flexible alternatives change total system cost.
- Design for recyclability, not merely substitution: Focus on mono‑material engineering, compatible inks and adhesives, and barrier innovations that reduce EPR exposure without compromising shelf life or food safety.
- Lock in supply chain partnerships now: Early agreements with converters and resin suppliers for recycled content and collection credits will be a competitive barrier as demand for certified recyclate intensifies.
- Test at scale, then industrialise: Move beyond lab prototypes—use controlled rollouts and retailer pilots to validate consumer acceptance, machinability on existing fill lines, and reverse‑logistics implications.
- Embed regulatory scenario planning in pricing: Use the report’s fee‑modelling templates to stress‑test price realignment and promotional strategies under different EPR outcomes.
- Assess M&A and JV opportunities: Target converters with mono‑material IP or regional collection ecosystems that accelerate time‑to‑market for recyclable formats.
How to use this intelligence in your 2026 planning cadence
For C‑suite and category leaders, the report functions as both a market compass and an execution playbook. Use it to:
- Calibrate three‑year capex plans for packaging equipment and conversion tooling.
- Develop supplier scorecards and RFP templates that quantify recyclability and EPR impact.
- Build pricing and promotional scenarios that reflect both material cost trajectories and evolving regulatory fees.
- Prioritise SKU rationalisation to reduce SKUs that are high‑cost to convert to compliant formats.
Next steps — converting insight into advantage
2026 will be a turning point where regulatory, commercial and material forces converge. The PW Consulting Pet Food Packaging Market report is structured to move your team from awareness to action: it supplies the market model, supplier intelligence, regulatory scenarios, and playbooks required to make defensible investment and sourcing decisions in 2026.
Executives preparing budget proposals, capex cases, or M&A memos will find the detailed datasets, supplier scorecards and implementation templates indispensable. This preview intentionally omits detailed segmentation tables and certain proprietary split figures; those are included in the full report and critical for pinpointing SKU‑level decisions.
For leadership teams that must balance sustainability commitments with margin preservation, our core recommendation is straightforward: treat packaging transformation as a portfolio of initiatives—regulatory compliance, consumer value, and cost optimisation—each requiring dedicated metrics, vendor commitments, and staged implementation. The right decisions this year will not only reduce regulatory risk but will create durable differentiation in a market growing steadily toward the late‑decade opportunity set.
For detailed analysis of this topic, please visit the official page: Pet Food Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com