

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Micro Turbine Market to Reach USD 344.8M by 2032 with 9.44% CAGR

Micro Turbine Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s latest Micro Turbine Market study is designed as a strategic playbook for executives making capital, product and policy decisions in 2026. Grounded in a five‑year historical review (2020–2025) and a detailed forecast through 2032, the research converts complex technical, regulatory and commercial dynamics into actionable options — while deliberately reserving the granular sub‑segment tables and vendor scorecards for clients who access the full report.
Micro Turbine Market
Market at a glance: macro trajectory and what it means
Micro turbine markets have moved beyond niche backup installations toward versatile building blocks for distributed energy, combined heat and power (CHP), and waste‑heat recovery. On a top‑line basis, the global micro turbine market expanded from approximately USD 163.2 Million in 2020 to about USD 215.0 Million in 2025 (base year). Under our central projection, the market is expected to rise to roughly USD 233.5 Million in 2026 and reach about USD 344.8 Million by 2032. That trajectory reflects a compound annual growth rate (CAGR) of 9.44% over the 2026–2032 forecast window — a pace that signals sustained commercial opportunity for manufacturers, integrators and project financiers.
Micro Turbine Market
Two high‑level implications follow: first, the market scale is now material enough to justify dedicated R&D and commercial investment while remaining fragmented enough to reward focused specialization. Second, policy drivers and fuel‑stack evolution (from natural gas and biogas to higher hydrogen blends and hybridized systems) will determine which value pools emerge fastest.
Micro Turbine Market
Why this research matters to a 2026 strategic plan
- Capital allocation: Our models translate headline growth into project‑level IRR sensitivities for CHP, standby and waste‑heat recovery applications so CFOs can prioritize capex and leasing options against other distributed energy investments.
- Product and technology roadmaps: Engineering leaders receive a comparative view of fuel flexibility, electrical/thermal efficiencies and balance‑of‑plant tradeoffs that influence lifecycle O&M and retrofit potential.
- Go‑to‑market and commercial structuring: Sales and business development teams will find playbooks for bundling micro turbines with energy storage, controls and service agreements to capture recurring revenue.
- Policy and incentive optimization: Project teams get a synthesis of near‑term incentives and compliance risks (see regulatory highlights below) to accelerate project payback and maximize tax credit capture.
- M&A and partnership screening: Corporate development teams can identify acquisition targets and JV partners with niche IP or channel access before valuations re‑rate the sector.
Regulatory and incentive context that will shape 2026 decisions
Policy remains a key lever. The report collates current incentive mechanics that materially change project economics: for example, the Fuel Cells (Residential and Microturbine System) Tax Credit provides a specific per‑capacity credit structure, and provisions within the Inflation Reduction Act (IRA) offer an Investment Tax Credit and Production Tax Credit pathway — notably a 30% ITC for qualifying systems under 1 MW AC or thermal when prevailing wage and apprenticeship conditions are met. Project teams must also reconcile recent administrative and statutory developments that alter eligibility timelines and emissions requirements. Installation capital expenditures continue to vary with capacity and configuration; recent benchmarking places microturbine CHP installed costs in the range reported by major energy programs, which should be used as a baseline for project underwriting.
Two practical takeaways: lock in incentive eligibility early in the design phase, and build prevailing‑wage compliance into contractor selection to avoid losing value at financial close.
What PW Consulting’s report delivers — operationally useful content
- Market sizing and forecast model (2020–2032) with downloadable scenario variants (central, upside, downside) and sensitivity tools you can run with your own price and fuel assumptions.
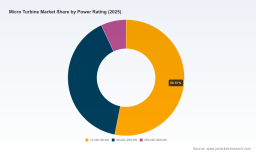
- TAM/SAM/SOM framework and practical guidance on how to partition opportunity by application, power rating and procurement model (CAPEX vs. EPC vs. energy service contract).
- Vendor landscape and competitive scorecards that evaluate technology readiness, fuel flexibility, service network, and commercial terms (note: detailed vendor revenue shares and segment allocations are reserved for subscribers).
- Unit economics calculator and payback templates that incorporate capital costs, incentive capture, fuel price trajectories and O&M profiles.
- Technical Appendix with benchmarked efficiency curves, emissions factor comparisons and recommended test protocols for field acceptance.
- Risk heatmaps and mitigation playbooks covering supply‑chain concentration, rare‑earth exposure, and counterparty credit risk for off‑take agreements.
- Case studies and commissioning checklists from recent projects that clarify lessons learned on permitting, interconnection and performance verification.
Competitive landscape — who matters and why
The micro turbine market remains moderately fragmented: the three largest players account for under a quarter of global share (CR3 ≈ 24.6%) and the top five approximately 26.2%. That structure favors specialist entrants and focused scale strategies over broad incumbent dominance. Below is an executive read on core vendors and their strategic posture.
- Ansaldo Energia S.p.A. (Genoa, Italy) — Ansaldo is positioning microturbines as part of integrated CHP/CCHP systems, promoting multi‑fuel capability (natural gas, biogas and hydrogen blends up to high percentages) and high electrical/thermal efficiency performance metrics. Their strength lies in system engineering for industrial and utility customers and in leveraging turbomachinery expertise across product lines.
- Capstone Green Energy Corporation (Van Nuys, CA, USA) — Capstone operates with a broad product footprint and a distribution model that emphasizes repeatable CHP deployments. Recent major orders and repeat business with food manufacturers underscore strength in packaged solutions and aftermarket services. Capstone’s air‑bearing microturbine architecture supports flexible fuels (natural gas, RNG, landfill gas, and hydrogen blends) and is a commercial leader in volume deployments.
- Bladon Micro Turbine (Warwick, UK) — Bladon is focused on small gensets for off‑grid and telecom backup applications and differentiates through single‑engine simplicity and ruggedness. Their positioning makes them a preferred option in harsh environments and for customers prioritizing fuel flexibility including liquid fuels.
- FlexEnergy Solutions (Centennial, CO, USA) — FlexEnergy targets larger microturbine gensets and hybrid off‑grid/grid‑parallel systems. The company’s emphasis on modular, scalable plants positions it well for distributed utility and industrial projects where site‑specific customization is needed.
- Turtle Turbines (India) — Turtle Turbines operates in the steam and compact cogeneration niche, offering mini‑cogen and waste‑heat recovery systems tailored to process industries. Their market edge is local manufacturing and fast time‑to‑deployment for captive power use‑cases.
- Advanced Microturbines Srl (Genoa, Italy) — With offerings spanning microturbines to turboexpanders, Advanced Microturbines targets energy‑recovery applications (gas decompression, pressure let‑down recovery) and small off‑grid systems. Their value proposition centers on energy recovery economics and compact system footprints.
- pyropower GmbH (Germany) — pyropower focuses on externally fired micro gas turbines for pyrolysis CHP systems, enabling electricity generation from thermal feedstocks in decentralized industrial settings. This technology is attractive where waste feedstock heat is available but fuel cleanliness varies.
Recent commercial signals reinforce these dynamics: a series of Capstone orders and follow‑on projects in 2025 highlights robust industrial demand for packaged CHP systems, and commissioning of small hydro‑powered microturbine projects demonstrates how the same core technology can be deployed in non‑combustion energy recovery roles. These events emphasize the market’s dual path: traditional combustion‑based CHP and a growing set of energy recovery and hybrid applications.
Strategic recommendations for 2026
- Prioritize modular CHP pilots in industrial hubs with high thermal loads — use the payback templates in our report to size projects that meet corporate decarbonization targets while accessing IRA/ITC benefits.
- Design product roadmaps for multi‑fuel capability, with explicit support for higher hydrogen blends and biogas/RNG compatibility; retrofit pathways will be a competitive differentiator.
- Bundle service and performance guarantees to convert one‑time equipment sales into annuity streams; rigorous remote monitoring and predictive maintenance materially increase life‑cycle margins.
- Evaluate M&A targets in niche categories (steam microturbines, turboexpanders, pyrolysis CHP) to secure specialty IP and accelerate entry into adjacent value pools.
- Embed regulatory compliance planning (prevailing wage, incentive phase‑outs) into the earliest development gates to avoid value leakage at financial close.
- Establish strategic supply‑chain partnerships for critical rotating components and control electronics to reduce lead times and protect gross margins as demand scales.
PW Consulting’s Micro Turbine Market study provides the models, templates and industry intelligence executives need to convert this growth trajectory into defensible action in 2026. For readers seeking the complete sub‑segment breakouts, vendor financials, downloadable forecast models and our full competitive scorecards, the detailed report and supporting data sets are available through PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Micro Turbine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com