

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: HD Microcellular PU Foam Market to Reach USD 2,115M by 2032 at 6.5% CAGR

High Density Microcellular Polyurethane Foam: Strategic Preview for 2026 Decision‑Makers
Introduction — why this preview matters
As organizations enter 2026 with capital allocation, product roadmaps, and supply‑chain redesigns on their agendas, the High Density Microcellular Polyurethane (HD‑MCPU) foam market presents a distinct mix of opportunity and risk. PW Consulting’s latest study (base year 2025, historical window 2020–2025, forecast 2026–2032) frames that environment with quantitative backbone and actionable implications. The market is sizable and expanding — driven by demand in technical applications — and our analysis highlights where executive teams should concentrate attention this year to convert growth into durable competitive advantage.
High Density Microcellular Polyurethane Foam Market
Market at a glance — macro trajectory without revealing the playbook
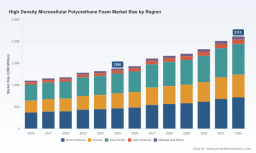
Key macro signals every senior leader must internalize: the HD‑MCPU foam market has demonstrated steady expansion through the first half of the decade and continues to compound. The report’s base year (2025) anchors a market value measured in the hundreds of millions (USD, Million) with a mid‑single‑digit compound annual growth rate (CAGR) projected across 2026–2032. By the end of the forecast window the market is materially larger than the 2025 base, reflecting both organic demand from established industrial verticals and emergent uses in electrification and precision manufacturing.
High Density Microcellular Polyurethane Foam Market
Two implications follow immediately. First, growth is sufficient to justify selective capacity investments and targeted R&D for firms seeking technical differentiation. Second, growth is not uniform — it is concentrated in technically demanding applications and geographies where regulatory and logistics dynamics can materially change cost economics within quarters. Our study provides the granularity to prioritize where to put money at risk; this preview is designed to orient strategy and highlight the questions that must be answered before capital is committed.
High Density Microcellular Polyurethane Foam Market
What 2026 decisions this market influences
- Procurement & commodity hedging: With polyurethane feedstock prices remaining volatile, procurement teams must move beyond yearly contracts. Dynamic hedging, supplier segmentation, and options for backward integration are now strategic imperatives.
- CapEx and footprint strategy: Mid‑term capacity additions make sense only when matched to technical capabilities and local input cost economics. Consider modular micro‑scale lines for regional flexibility rather than single, large greenfield plants.
- Product & application strategy: The highest returns accrue to formulations and machining capabilities that reduce tolerance, thermal conductivity, or outgassing for EV, aerospace, and medical instrument use cases. Prioritize product roadmaps that raise switching costs for key buyers.
- M&A and partnerships: The market is moderately concentrated among a handful of specialists. M&A can rapidly scale capabilities and customer access, but must be evaluated against integration complexity and raw material exposure.
- Risk management & regulatory compliance: Environmental constraints on feedstocks and emissions are tightening; compliance strategies must be budgeted into product lifecycle costs and go‑to‑market timelines.
Dynamics shaping the 2026 landscape
Three categories of dynamics dominate the near‑term outlook: raw‑material economics, logistics & trade, and regulation. Each directly influences margin, time‑to‑market, and strategic optionality.
- Raw‑material economics: Polyurethane input costs have shown renewed upward momentum in early 2026. Analysts reported polyurethane prices in Europe at approximately 3.48 USD/kg in March 2026, with upward movement driven by elevated MDI and polyol feedstock costs. South America experienced a similar cost lift, with prices near 3.43 USD/kg and a significant rise through the winter months due to constrained cargo availability and feedstock pressure. These inputs drive variable cost and can quickly compress margins on commoditized products.
- Logistics & freight: Freight disruptions and rerouting raised landed costs for imports in key manufacturing hubs during early 2026, increasing the value of local capacity or nearshoring strategies. Transport surcharges are no longer a short‑term cost blip; they are a structural element for regional sourcing models.
- Regulatory pressure: Environmental scrutiny on raw materials and the carbon footprint of intermediate chemicals has intensified. Regulators are enforcing lifecycle considerations that affect formulations, permissible emissions, and waste management. Compliance timelines should be embedded in product development and customer contracts today.
Competitive landscape — who matters and what they bring
The HD‑MCPU foam market is populated by specialized incumbents and a small but growing set of technical suppliers. Market concentration metrics indicate meaningful market share held by the leading firms (CR3 and CR5 at moderate levels), creating both an entry barrier and a landscape of potential partnership targets.
- Rubberlite Inc. (Huntington, WV) — https://www.rubberlite.com/ Rubberlite’s HyPUR‑cel® family is a clear example of a focused product architecture for technical applications such as gasketing, sealing, and industrial components. Their strength lies in differentiated product specifications and longstanding relationships in industrial segments that value consistency and post‑sale support.
- XYFoams (Hubei Xiangyuan New Material Technology Inc.) (Xiaogan, Hubei Province, China) — https://www.xyfoams.com/ XYFoams is notable for breadth in density range and for addressing emerging high‑growth needs like EV battery insulation and precision electronics. They combine scale with cost competitiveness, making them a natural partner or competitor depending on regional strategy.
- General Plastics Manufacturing Co. (Tacoma, WA) — https://www.generalplastics.com/ General Plastics’ LAST‑A‑FOAM® portfolio targets aerospace and precision engineering applications where tolerances, material stability, and certification pathways are central. Their go‑to‑market strength is technical validation and regulatory familiarity.
- Urethane Technologies International (Monroe, WA) — https://www.utech-polyurethane.com/ Urethane Technologies focuses on high‑quality urethane foam production with an emphasis on microcellular high density variants for industrial and technical uses. Their value proposition is process control and customization for customer‑specific performance.
For decision‑makers, the takeaway is straightforward: business models that combine technical depth with supply‑chain resilience command premium positioning. Whether through vertical integration, long‑term offtake agreements, or collaborative development contracts, securing upstream inputs and certification pathways accelerates de‑risking.
Practical, operational levers for 2026
- Short term (0–12 months): Lock in flexible supply agreements that include escalators and volume bands; establish a cross‑functional materials war room to monitor feedstock indices daily; prioritize customer contracts that pass a portion of feedstock risk through indexation clauses.
- Medium term (12–36 months): Invest in modular capacity and regional finishing operations rather than single large plants; develop co‑innovation labs with key OEMs to fast‑track qualified materials into EV and aerospace supply chains.
- Long term (36+ months): Evaluate upstream investments or minority stakes in polyol/MDI producers where regulatory shifts and feedstock security materially affect product economics; pursue bolt‑on acquisitions that bring process IP, certification history, or market access to priority verticals.
What PW Consulting’s full report delivers (and what this preview intentionally withholds)
Our full market study provides the operational detail required to execute the 2026 plays outlined above. Deliverables include:
- Detailed market volumes and value by segment, region, and application across the historical and forecast windows (2020–2032).
- Scenario models that stress test margins under different feedstock price, freight, and regulatory outcomes — plus sensitivity matrices for capital projects.
- Benchmarked supplier performance and supplier‑level scorecards that evaluate cost, technical capability, lead time reliability, and compliance risk.
- Deal‑ready strategic options: a prioritization framework for M&A targets, partnership templates, and phased integration roadmaps.
- Operational playbooks for procurement, quality assurance, and product qualification tailored to high‑density microcellular formulations used in high‑value applications.
In this preview we have deliberately avoided publishing granular regional or application split figures and certain product‑level economics. That core segmentation data is the most valuable intelligence for commercial negotiations and capital allocation — and it is included in the complete report and associated data‑dashboards.
Final strategic advice for 2026
Executives should treat HD‑MCPU foam not as a commodity but as a strategic intermediate where formulation, process control, and supply certainty determine competitive advantage. The combination of mid‑single‑digit CAGR and concentrated supplier capabilities favors focused investment in technical differentiation, flexible sourcing, and regulatory readiness. If you are preparing capital plans, supplier selection criteria, or R&D roadmaps for 2026, act now: secure your feedstock exposure, validate materials with high‑priority customers, and consider targeted partnerships to accelerate qualification cycles.
To convert these directional recommendations into executable decisions — supported by the data and scenario analysis that senior teams require — access the full PW Consulting High Density Microcellular Polyurethane Foam Market study. The complete report contains the proprietary segmentation, supplier scorecards, and financial models that underpin the strategic plays outlined here.
Contact PW Consulting or visit our source webpage to request the report, the interactive data‑dashboards, and a tailored briefing for your executive team.
For detailed analysis of this topic, please visit the official page: High Density Microcellular Polyurethane Foam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com