

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting Report: Worldwide Polylactic Acid Straw Market Poised for 12% CAGR from 2026 to 2032
By pmarketresearch, 2026-08-12
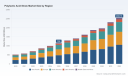
Worldwide Polylactic Acid (PLA) Straw Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Polylactic Acid (PLA) Straw Market delivers a concentrated briefing designed to inform capital allocation, supply-chain restructuring, and product strategy as companies position for the decisive 2026 planning cycle. The study synthesizes historical performance (2020–2025), a detailed forecast horizon (2026–2032) and an actionable playbook for market participants. Key macro takeaways: the market scaled materially between 2020 and 2025, reached a meaningful milestone in the 2025 base year, and is forecast to expand at an average compound annual growth rate (CAGR) of 12.0% over 2026–2032 — confirming a multi-year commercial runway for PLA-based straw solutions.
Portable Generator Set Market
Why this matters for 2026 strategy
- Accelerating adoption, predictable momentum. The market’s historical trajectory and our 12% projected CAGR through 2032 indicate that PLA straws are moving beyond a niche compliance solution to a structural component of foodservice and retail packaging systems. For business leaders, this translates into a predictable demand base to support capacity investments, product R&D, and channel expansion in 2026.
- Fragmented competitive dynamics create windows for scale plays. Market concentration metrics in our study show a modestly consolidated top tier, leaving substantial share accessible for fast-followers and regional champions. That fragmentation supports both organic growth and M&A-led consolidation strategies.
- Regulatory backstop and infrastructure dependency. Mandates and bans on single-use plastics are establishing minimum market demand, but the pace at which that demand converts to commercially viable sales is closely tied to composting infrastructure and certification requirements. Companies that align product design and certification roadmaps to prevailing standards will convert regulatory intent into revenue more efficiently in 2026.
What the report provides — practical, transaction-ready insight
We designed the report as a decision support tool, not merely an industry overview. The deliverables most relevant to near-term 2026 choices include:
Worldwide Bicycle Ergometer Market
- Proprietary market sizing and forecast model (2020–2032) with scenario layers that stress-test demand against regulatory and feedstock risk parameters.
- Bottom-up cost build for PLA straw production, including sensitivity analyses for lactic acid and corn-starch feedstock price swings, energy costs, and extrusion yields.
- Supply-chain mapping that identifies concentration points and single-source risks across resin, compounding, and finished-goods extrusion.
- Regulatory and certification matrix that cross-references regional standards (industrial composting, biodegradability testing, labelling requirements) with go-to-market implications.
- An executable playbook covering five archetypal strategies: local manufacturing and nearshoring, supplier diversification, premium product differentiation, integrated feedstock sourcing, and M&A / strategic partnerships — each with KPIs, investment envelopes and implementation timelines suited for 2026 budgeting cycles.
- Targeted company profiles and competitive benchmarking to support vendor selection, JV negotiations, and due diligence in potential acquisitions.
Market dynamics you must factor into 2026 plans
- Feedstock volatility. PLA economics are tightly coupled to agricultural feedstocks and lactic acid availability. Recent industry signals showed notable price uplifts for both corn-derived inputs and regionally traded lactic acid — volatility that can compress margins or force rapid price pass-through. Our model quantifies how a range of feedstock scenarios alter EBITDA at different integration levels.
- Regulatory drivers are firm but heterogeneous. Standards like EN 13432 and regional single-use plastic bans have created minimum thresholds for product acceptance, but compliance requirements vary by jurisdiction and by end-use case. Certification timing and label claims therefore materially affect market access and price realization.
- Trade policy and tariffs. Import tariffs on PLA products into certain territories increase landed cost for Asian-sourced straws and change the calculus for centralized vs. regional manufacturing footprints.
- Industrial composting and end-of-life infrastructure. Market growth will be smoother where composting infrastructure exists or where municipal waste policies align with industrial compostability. Where infrastructure lags, buyers are more price-sensitive and quality/education become differentiators.
Competitive landscape — what incumbents and challengers are doing
The competitive set is composed of global resin leaders, specialized bioplastics producers and regionally focused finished-goods manufacturers. The report profiles each major player and interprets the strategic intent behind recent moves.
Worldwide Vineyard Equipment Market
- TotalEnergies Corbion (Luminy PLA). As a leading PLA resin supplier, recent product-grade optimizations aimed at improving extrudability and clarity signal a push to make PLA more cost-competitive in high-throughput straw lines. For customers, this reduces technical friction and opens options for premium clarity products targeted at foodservice chains.
- NatureWorks (Ingeo). The announced capacity expansion is a classical response to upstream demand signals. For strategic planners, this move reduces the likelihood of resin shortages but also intensifies competition for contract volumes and long-term offtake agreements in 2026–2027.
- Biome Bioplastics. Certification updates and targeted product positioning reflect a route-to-market that emphasizes compliance and brand trust — a strategy that appeals to institutional buyers prioritizing verified end-of-life claims.
- Regional manufacturers (Biopac India, Ecor Products, Green Straw, Vegware). These firms exemplify differentiated strategies: low-cost export platforms, niche product ranges (e.g., hot-beverage rated PLA), and integrated foodservice portfolios. Their agility remains a competitive challenge to larger players moving into downstream offerings.
Strategic implications and recommended actions for 2026
Below are high-level actions our clients are evaluating with support from the report. Each recommendation is backed by scenario-tested financial and operational plans included in the full deliverable.
- Pursue flexible sourcing and contractual hedges. Hedging feedstock exposure and establishing multi-supplier contracts for resin will mitigate input-price shocks emerging from agricultural cycles and regional supply disruptions.
- Invest selectively in certifications and claims governance. Faster certification turnaround and audited claims management unlock higher price points and reduce buyer churn in institutional channels.
- Optimize manufacturing footprint. A regional-production strategy limits tariff exposure and improves service levels to priority accounts. The report includes decision matrices to compare centralized scale vs. regional manufacturing trade-offs under different tariff and demand scenarios.
- Differentiate on functional performance. Performance-driven differentiation (heat-stable PLA grades, flexible vs. straight straw designs, clarity, strength) commands premium positioning where buyers treat sustainability and functionality as co-equal criteria.
- Assess M&A selectively. Given market fragmentation, bolt-on acquisitions or minority investments in regional champions can accelerate channel access and scale; our M&A playbook ranks targets by strategic fit and likely valuation multiples.
Risk matrix and what keeps CFOs awake
Our risk analysis prioritizes three issues for 2026 financial planning:
- Feedstock-driven margin compression. Material price moves in corn starch and lactic acid are the single largest earnings risk.
- Certification and liability exposure. Misaligned claims or failed biodegradability tests can cause reputational and contractual penalties.
- Policy and trade shocks. New tariffs or abrupt shifts in single-use plastics regulation can alter regional demand curves within quarters.
Each risk is accompanied in the report by mitigation playbooks — contractual, operational and insurance-based — that quantify cost-to-mitigation and ROI timing windows suitable for 2026 budget cycles.
How PW Consulting’s analysis supports actionable 2026 plans
Our study is structured for rapid translation into boardroom decisions. We combine a transparent modeling framework, primary interviews with resin and finished-goods producers, and a detailed competitive database to enable:
- Capex prioritization with NPV and payback scenarios under multiple feedstock outcomes.
- Commercial play testing for channel and pricing strategies with tactical sales materials and buyer decision heuristics.
- Due diligence packages for M&A and JV partners, including operational checklists and post-deal integration scorecards.
Next steps — where to find the full intelligence
This preview provides the strategic contours you need to begin shaping 2026 priorities. The full report contains the granular segmentation, proprietary forecasting worksheets, company-level financial impacts, and downloadable scenario models that underpin the recommendations summarized here. To access the complete intelligence suite, including the full competitive profiles and the datasets that feed our cost and demand models, visit the PW Consulting report page.
PW Consulting stands ready to support bespoke strategy sessions, M&A screens, or supplier negotiations informed by the report. For decision-makers targeting 2026 execution certainty in the PLA straw market, the time to convert strategic intent into operational plans is now.
For detailed analysis of this topic, please visit the official page: Worldwide Polylactic Acid Straw Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Fire and Gas Detection Systems Market to Rise from USD 7,500 Million in 2025 to USD 11,654.9 Million by 2032 at a 6.5% CAGR
By pmarketresearch, 2026-08-12
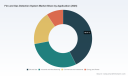
Worldwide Fire and Gas Detection System Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market research, "Worldwide Fire and Gas Detection System Market — 2026 Outlook and 2026–2032 Forecast," provides executive teams with a rigorous, forward-looking evidence base to shape capital allocation, product strategy, M&A screening, and regulatory compliance planning in 2026. Built on a 2025 base year and a detailed historical run (2020–2025), the report projects the market through 2032 and quantifies a sustained growth trajectory at a compound annual growth rate (CAGR) of 6.5% across the forecast horizon. Our bottom-up model places the market at approximately USD 7.5 billion in 2025, expanding toward an estimated USD 11.65 billion by 2032.
Worldwide Database Assessment Service Market
Why this report matters for 2026 strategic decisions
-
Timing: 2026 is a pivotal year for firms that need to translate near-term regulatory shifts, supply-chain realignments, and sensor-technology inflections into competitive advantage. The PW Consulting forecast crystallises those inflection points into revenue and risk scenarios that are actionable within board planning cycles.
Sleeper Chair For Hospital Market -
Risk-aware growth planning: With the market forecast growing at 6.5% CAGR, management teams must balance growth capture against margin pressure from component cost volatility (semiconductor and precision optics inputs) and increasing compliance costs in high-risk sectors. Our scenario modules enable trade-off analysis between premium integrated solutions and cost-competitive modular offerings.
Worldwide Mechanical Booster Pumps Market -
Capital allocation and M&A prioritisation: The market’s moderate concentration (CR3 ~42.5%; CR5 ~58.75%) suggests a landscape where leading incumbents hold substantial influence but meaningful consolidation opportunities remain. That concentration profile supports an active M&A playbook targeting technology tuck-ins, regional scale, and solutions that accelerate digitisation of installed bases.
What’s inside PW Consulting’s report (practical deliverables)
-
Proprietary market model and forecast (2026–2032) — delivered in an interactive format that lets users stress-test revenue trajectories under alternative macro and regulatory scenarios.
-
Executive decision-support dashboards — including CAPEX implication matrices, IRR simulations for technology investments, and playbooks for pricing and bundling strategies tied to installed base monetisation.
-
Competitive heat maps and capability gap analyses — positioning the major global suppliers by technology stack, service footprint, and solution integration depth to help prioritise partnerships, OEM relationships, and M&A targets.
-
Channel and go-to-market playbooks — tactical guidance for OEMs, system integrators, and industrial end-users on accelerating adoption of wireless, IoT-enabled, and AI-driven predictive maintenance offerings.
-
Regulatory impact assessments — scenario-based analysis of how evolving standards (including recent NFPA updates) materially alter certification timelines, product roadmaps, and liability exposure.
-
Supply-chain sensitivity analysis — identifying critical raw material and component bottlenecks (e.g., semiconductor-grade sensors, precision optics) with mitigation strategies and alternative sourcing frameworks.
Key themes shaping the market in 2026
-
Standards convergence and certification complexity: The adoption of broader integration expectations in fire alarm standards — for example, updated guidance that brings gas detection, open path, ultrasonic gas, and smoke detection closer together — is changing product architectures and certification timelines. Companies that proactively align R&D roadmaps with standards evolution will shorten time-to-market and capture premium positions in regulated sectors.
-
Sensor and electronics supply dynamics: Fire and gas systems are increasingly reliant on advanced sensor technologies (electrochemical cells, infrared and IR3 optics, semiconductor-based sensing elements), and the upstream supply chain remains susceptible to capacity constraints and pricing swings. Strategic suppliers will need to secure multi-year supply agreements or invest in vertical integration to stabilise margins.
-
Digitalisation and predictive maintenance: Miniaturisation, IoT connectivity, wireless mesh deployments, and AI-driven analytics are transitioning many deployments from reactive alarm systems to predictive safety ecosystems. This shift unlocks new recurring revenue streams (SaaS, managed detection) and changes how capital is deployed across product, services, and software.
-
Segmentation-driven go-to-market: Demand drivers differ materially by end market (e.g., oil & gas vs. commercial buildings). The most successful vendors will tailor solution bundles and service SLAs to the risk profiles and procurement practices of each vertical while maintaining a modular product architecture to limit product proliferation costs.
Competitive landscape — who matters and why
The market is controlled by a mix of diversified industrial conglomerates, focused safety specialists, and nimble technology challengers. PW Consulting’s analysis profiles each major participant along three dimensions: technology breadth, systems integration capability, and go-to-market reach.
-
Honeywell International Inc. — A global, diversified player with broad fixed and portable portfolios and deep channel penetration across oil & gas, chemical, and industrial end-users. Its strength lies in integrated safety ecosystems and the ability to bundle detection with automation and building management services.
-
MSA Safety Incorporated — Focused on industrial safety, MSA’s product set spans fixed and portable detection and open-path technologies. Its compliance-centric approach and active role in standards discourse (including NFPA-focused activities) keep it well-positioned among safety-conscious buyers.
-
Drägerwerk AG & Co. KGaA — Known for high-reliability optical and multi-gas detection technologies, with a strong footprint in maritime and petrochemical installations. Dräger’s engineering heritage supports premium-priced, specification-driven contracts.
-
Emerson Electric Co. — Integrates detection solutions within broader process automation and safety instrumented systems, targeting end-users that prioritise unified control and safety architectures.
-
Siemens AG — Combines fire detection components with industrial and building management systems; suited to large-scale, multi-site deployments requiring centralised monitoring and lifecycle services.
-
Autronica Fire and Security AS, ABB Ltd., Johnson Controls International — Each offers differentiated capabilities in maritime, industrial automation, and building safety respectively. These players compete on service depth, regional presence, and integration with adjacent safety systems.
-
Specialists and challengers (Teledyne, FGD, ESP Safety, Industrial Scientific, etc.) — These firms provide focused technical advantages (e.g., advanced UV/IR flame detection, portable connected gas monitors) and represent high-value acquisition targets for larger integrators seeking rapid capability upgrades.
Recent market signals — what to watch in 2026
-
Standardisation and industry forums: High-visibility engagements, such as MSA Safety’s presentations at the NFPA Conference & Expo, signal that standards evolution is not only regulatory but also a commercial battleground. Firms that shape and anticipate standard updates can influence procurement criteria and interoperability requirements.
-
Product innovation at trade shows: Recent launches of long-range, optically enhanced flame detectors and targeted HVACR-focused gas detection offerings underscore the pace of sensor innovation and the widening universe of addressable use-cases.
-
Channel activations and trade-show activity: Active participation by midsize specialists at major expos highlights the importance of relationship selling and the continuing relevance of demonstration-led procurement, especially for safety-critical applications.
How to use the report — recommended executive actions for 2026
-
Board-level scenario planning: Use the report’s forecast scenarios to stress-test capital spending paths under different regulatory and supply conditions, and align R&D budgets to the most likely adoption curves for IoT-enabled and AI-enhanced offerings.
-
M&A target screening: Deploy our competitive heat maps to identify acquisition targets that provide complementary sensor technologies, regional footholds, or service capability that accelerate recurring revenue models.
-
Portfolio rebalancing: Apply our margin-pressure and supply-risk modules to decide where to invest in vertical integration (e.g., sensor manufacturing), where to pursue partnerships, and where to de-emphasise legacy product lines.
-
Commercial optimisation: Adopt the go-to-market playbooks to design outcome-based contracts (e.g., uptime guarantees, performance-based maintenance) that capture more of the installed-base value chain.
Access to full intelligence
PW Consulting has deliberately structured this briefing to present the strategic contours and decision-useful implications of the market while preserving the granular subsegment tables, regional breakdowns, and vendor share matrices that are part of the full report. Executives, investors, and technology leaders who require detailed breakdowns (including model-level forecasts by product type, application, and region; vendor-level revenue estimations; and downloadable datasets) should obtain the full research package.
For organisations preparing budgets, negotiating supplier agreements, or evaluating acquisition targets in 2026, the full report is designed to be directly operational — supplying the datasets, scenario workbooks, and playbooks needed to convert insight into action. Contact PW Consulting or visit our report landing page to request the full dataset, custom briefing, or a tailored workshop for your leadership team.
About PW Consulting
PW Consulting specialises in strategic analysis and operational guidance for industrial technology markets. Our cross-functional teams combine market modelling, primary research with industry stakeholders, and practical scenario planning to deliver intelligence that executives can act on immediately. Our Worldwide Fire and Gas Detection System Market study integrates proprietary supply-chain analysis, standards-impact assessment, and vendor capability audits to help clients make confident decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Fire and Gas Detection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Intelligent TCM Diagnosis System Market to Expand at a Robust 14.48% CAGR Through 2032
By pmarketresearch, 2026-08-12
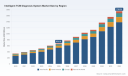
Worldwide Intelligent TCM Diagnosis System Market: Strategic Preview for 2026 Decision-Makers
PW Consulting presents an executive preview of our upcoming Worldwide Intelligent Traditional Chinese Medicine (TCM) Diagnosis System Market report. This release synthesizes the report’s most consequential, decision-grade findings and lays out how senior executives, investors, health system strategists, and policy teams should position themselves as the market accelerates into 2026. The purpose here is to demonstrate the analytical depth of the full study and to highlight the strategic choices that will matter — while preserving the granular segment and regional tables that drive transactional decisions (those details are available in the full report).
Worldwide Windshield Glass Market
Executive snapshot: a market on a steep, durable growth curve
The intelligent TCM diagnosis systems market has shifted from niche validation to broad commercial scale over the past half decade. Our market sizing shows the market expanding from roughly 345 Million USD in 2020 to about 679 Million USD in 2025 (base year). Under conservative-to-midcase assumptions embedded in our model, the market is forecast to exceed 1.75 Billion USD by 2032, reflecting a compound annual growth rate (CAGR) of approximately 14.48% across the forecast period.
Worldwide eLearning Content Software Market
For 2026 specifically, the market is projected to step up meaningfully versus the 2025 base as clinical deployments, reimbursement alignment, and modular product strategies drive adoption in hospitals, integrated care settings, and screening centers. These macro dynamics create an inflection point for companies and health systems: 2026 will be the year where product-market fit becomes tangible and commercial scale decisions — partnerships, regulatory pathways, and distribution investments — will determine long-term share.
Worldwide 5G Network Equipment on Top of Antennas Market
Why 2026 is the strategic hinge year
- Reimbursement and payment modernization — The ongoing roll-out of DRG-style payment reforms across TCM hospitals has begun to align incentives toward objective diagnostics and standardized treatment protocols. For providers, clear reimbursement pathways reduce commercial risk; for vendors, they unlock procurement budgets tied to outcomes and efficiency.
- Clinical validation and deployment — Recent clinical deployments of AI-assisted instruments converting classical four-diagnosis inputs (pulse, tongue, facial, inquiry) into structured, auditable data streams have moved the technology from pilot to production environments in multiple hospital systems. These real-world evidentiary lifts shorten sales cycles and improve interoperability prospects.
- Consolidation opportunity window — Market concentration metrics show a moderate level of aggregation among leading vendors. The top-tier players occupy a meaningful but not dominant share, leaving strategic room for fast followers, focused niche players, and M&A-driven roll-ups to accelerate scale.
Industry dynamics that should guide 2026 resource allocation
- Regulatory and policy scaffolding: National policies encouraging unified payment systems and designated TCM reimbursement categories mean that technology vendors must design value propositions aligned with both efficiency (length of stay, clinical workflow) and documentation/auditability for payers.
- Clinical economics over feature lists: Procurement committees increasingly prioritize demonstrable impacts on length of stay, diagnostic consistency, and resource utilization. Vendors should price and package solutions around validated ROI pathways rather than purely feature-driven innovation.
- Data sovereignty and interoperability: As deployments scale across hospital networks and screening centers, the ability to integrate diagnostic outputs into electronic medical records and population-health platforms becomes a procurement gating factor.
- Research-to-market pipelines: Partnerships between academic medical centers and vendors are accelerating translational pathways; these collaborations are the fastest route to credible clinical evidence and guideline recognition.
Competitive landscape: who matters and why
The competitive field combines specialist TCM device manufacturers, AI-focused startups, and academic-commercial hybrids. Our review of active players highlights several archetypes and exemplar firms:
- AI-first diagnostic platforms — Companies developing machine-learning models for multi-modal TCM inputs (pulse waveform, tongue imaging, facial analytics) are establishing differentiation through algorithmic accuracy, model explainability, and clinical validation pathways.
- Medical-device integrators — Firms with manufacturing scale and regulatory experience offer end-to-end systems (sensors + software + cloud analytics) tailored for hospital adoption and lifecycle support.
- Academic-anchored innovators — University research centers and affiliated spin-outs provide leading-edge sensor validation and clinical trial infrastructure that accelerates evidence generation and acceptance by clinical leaders.
Representative companies shaping the market include a mix of Beijing-, Shanghai- and regional-based technology firms, established TCM pharmaceutical and wellness providers expanding into diagnostics, and research institutions that have moved validated instruments into clinical use. While we identify and profile key players in the full report, the strategic takeaway for 2026 is straightforward: success will attach to three capabilities — clinically validated algorithms, manufacturing and distribution scale, and payer-aligned economic narratives.
Recent signals: deployment and policy events to watch
- Clinical deployment highlight: In March 2026, a major university-affiliated research center publicly documented deployment of an AI-assisted intelligent TCM diagnostic instrument into hospital and screening settings. This milestone illustrates how academic validation and institutional adoption can serve as a commercialization catalyst.
- Payment reform implications: The ongoing implementation of DRG-based systems within TCM hospitals has started to create explicit reimbursement pathways for technologies that demonstrate measurable reductions in length of stay and diagnostic variability — an essential market enabler.
- Policy nuance: Dual-path payment models, which combine DRG frameworks with targeted subsidies for recognized TCM techniques, create both opportunity and complexity for vendors—products that can document clinical and economic value in both streams will have the broadest adoption potential.
Practical, actionable contents in the full PW Consulting report
The full report is built for executable decisions. It contains:
- Detailed market-sizing and forecast models (2020–2032) with scenario analysis and sensitivity testing tuned for different adoption and reimbursement assumptions.
- Competitive benchmarking: vendor scorecards, technology roadmaps, go-to-market strategies, and comparative regulatory readiness assessments.
- Reimbursement and policy playbooks that translate DRG and subsidy constructs into commercial milestones and priceability thresholds.
- Clinical validation frameworks and sample study protocols that vendors and purchasers can adopt to accelerate hospital approval and payer acceptance.
- Acquisition and partnership radar: prioritised M&A targets and alliance archetypes for entrants seeking rapid scale or capability augmentation.
- Operational tools including ROI calculators, procurement spec templates, and deployment checklists tailored for hospital IT, clinical engineering, and vendor management teams.
Recommended 2026 actions by stakeholder
- VCs and strategic investors: Prioritize companies demonstrating verifiable clinical outcomes and clear pathways to reimbursement. Early-stage capital should favor firms with academic partnerships and defensible data assets.
- Device vendors and startups: Invest in clinical evidence generation and interoperability; structure pilots with hospitals under commercial terms that can be converted into long-term contracts tied to economic KPIs.
- Hospital and health system leaders: Treat intelligent TCM diagnostic systems as part of digital transformation and value-based care strategies — evaluate pilots not only for clinical fit but also for data governance and reimbursement alignment.
- Policy-makers and payers: Use phased, indication-based reimbursement pilots to accelerate standardization while preserving clinical autonomy; incentivize evidence generation that demonstrates both safety and efficiency gains.
Risk matrix and mitigation playbook
The principal risks to the market thesis are regulatory ambiguity, slow payer alignment, fragmented interoperability standards, and uneven clinical evidence. Mitigations include early engagement with regulators, co-designed reimbursement pilots with payers, adoption of open data standards, and multi-center clinical validation programs that reduce single-site bias.
Conclusion — why you should read the full report
2026 is a transition year: the underlying technologies have matured, policy frameworks are aligning, and commercial adoption is shifting from pilots to procurement cycles. PW Consulting’s full Worldwide Intelligent TCM Diagnosis System Market report converts these macro trends into actionable plans: who to partner with, how to structure pilots to be reimbursable, where consolidation may provide scale, and what performance metrics will unlock hospital budgets.
This preview surfaces the strategic contours. The complete report contains the granular segmentation, country-level breakouts, supplier scorecards, and executable templates that are essential for investment memos, procurement decisions, and product roadmaps. Accessing that content will materially reduce execution risk for stakeholders planning market entry or scale in 2026 and beyond.
Next steps
- Contact PW Consulting to schedule a briefing tailored to your organization’s role (investor, vendor, provider, or policymaker).
- Request the full report for the complete dataset, vendor profiles, and downloadable ROI models.
- Engage our advisory team to translate the report’s findings into a 90–180 day implementation plan customized for your market and technology posture.
For detailed analysis of this topic, please visit the official page: Worldwide Intelligent TCM Diagnosis System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Sound Cards Market Set to Expand at a 5.88% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Sound Cards Market — Strategic Outlook for 2026
Executive snapshot
PW Consulting’s latest Worldwide Sound Cards Market report positions the market as a resilient, innovation-driven segment within the broader audio-electronics ecosystem. Measured in our 2025 base year, the global sound cards market reached approximately USD 517.25 Million (Million USD). Our forecast indicates continued expansion through the 2026–2032 horizon, with a compound annual growth rate (CAGR) of 5.88%, bringing the market to an estimated USD 771.6 Million by 2032. Market concentration remains moderate: the top three vendors account for roughly 41% of revenue, and the top five for about 57% — an industry structure that supports both incumbent scale plays and targeted disruption by well-capitalized specialists.
Worldwide Security Risk Analysis Software Market
Why this report matters to 2026 decision-makers
-
Investment prioritization: We translate macro growth and driver alignment into a short-list of near-term investment opportunities that maximize return within the 2026 planning cycle.
Mobile Fetal Monitor Market -
Risk-aware sourcing: The report maps supply-chain fragilities and regulatory stress points directly to procurement levers, enabling purchasing and operations leaders to cost-effectively de-risk component flows.
Worldwide Lithium-Ion Battery ICs Market -
Product & channel strategy: For OEMs, consumer brands, and pro-audio companies, we provide a prioritized set of product features, channel experiments, and pricing tactics that have been stress-tested against alternative market scenarios.
-
M&A and partnership screening: We convert concentration metrics, technology roadmaps, and margin structures into an actionable M&A and teaming scorecard for active acquirers and strategic partners.
Market dynamics shaping 2026 strategy
Three macro-to-micro dynamics will dominate boardroom conversations in 2026 and beyond:
-
Supply-chain and regulatory friction. Continued U.S. export controls on advanced semiconductors, combined with tariff uncertainty, have introduced sourcing complexity across audio ICs and related components. Q4 2025 saw tightened lead times for certain passives and discrete devices, putting pressure on time-to-market for new SKUs and on component cost baselines.
-
Component and converter innovation. Improvements in ADC/DAC architectures — driven by specialized semiconductor houses — are raising the performance floor for entry-level and professional solutions alike. This is accelerating feature commoditization (e.g., higher dynamic range, lower latency) while opening premiumization opportunities where software and ecosystem lock-in add value.
-
Segmentation pull: gaming, professional studio/broadcast, and home entertainment continue to pull product roadmaps in different directions. Gaming and consumer segments prize low-latency, USB/PCIe convenience, DSP-enhanced experiences and software ecosystems; professional users demand multi-channel I/O, ultra-low-latency drivers, and studio-grade converters. These divergent needs create both cross-sell and cannibalization risks that require disciplined product-line architecture.
Competitive landscape — strategic implications
The market comprises several distinct player archetypes. Understanding which archetype you compete with or partner through will determine margin targets, route-to-market, and technology partnerships.
-
Consumer and gaming incumbents: Creative Technology and ASUS continue to exploit brand equity and platform integration to defend high-volume gaming and enthusiast segments. Creative’s January 2025 launch of a new Sound Blaster USB DAC/amp — with refreshed drivers and firmware optimizations — underscores incumbents’ playbook: iterative hardware updates combined with sustained software investment to extend lifecycle value.
-
Silicon and OEM suppliers: Realtek and C-Media operate at the foundational layer, providing codecs and controllers that underpin many onboard and aftermarket products. For buyers, close collaboration with these suppliers can materially reduce BOM risk and shorten NPI cycles; for challengers, optimizing around these chipsets is a path to cost leadership.
-
Professional audio specialists: Focusrite, Universal Audio, RME, MOTU, PreSonus, and others form a category characterized by high engineering differentiation, premium pricing, and close relationships with studios and creators. Their advantage is not only in hardware but in proprietary DSP, driver stability, and ecosystem tools that justify premium margins.
-
Value and niche players: Companies such as Sabrent, Behringer, HT Omega, and select boutique brands serve price-sensitive or very specialized pockets. These players can be opportunistic partners for distribution expansion or acquisition targets for incumbent brands seeking adjacent volume.
-
Implication for 2026 strategy: Scale matters for distribution and marketing, but differentiation still anchors premium segments. Winning strategies combine reliable supply-chain partnerships with selective feature investment (e.g., DSP toolkits, low-latency drivers, and seamless platform integrations) and a clear go-to-market for either mass or professional channels.
What the report contains — practical deliverables (high-level)
The report is crafted for immediate operational use by product, procurement, corporate development, and strategy teams. Key actionable elements include:
-
Consolidated market-sizing and validated growth scenarios (2020–2032) with transparent methodology and sensitivity testing.
-
Vendor heatmaps and capability matrices that map product features, software stacks, and channel strength — enabling rapid competitor benchmarking.
-
Supply-chain stress tests and cost-risk models that translate component lead-time variance and tariff scenarios into margin impact simulations.
-
Go-to-market playbooks for three archetypal business models: Consumer/Gaming OEM, Pro-Audio Specialist, and Component Supplier/ODM. Each playbook contains prioritized initiatives, expected ROI, and 90/180/540-day milestones.
-
M&A and partnership scorecards: an evidence-based shortlist of targets and partnering patterns, accompanied by valuation sensitivities tied to concentration metrics and forecast demand curves.
-
Regulatory and geopolitical risk dashboard that maps where export controls and domestic chip policies most materially affect sourcing and manufacturing options.
Note: To preserve strategic integrity and to support consultative follow-up, this press summary intentionally omits granular sub-segment revenue tables and regional/application-level breakouts. The full dataset and vendor-level tables are available through the PW Consulting report portal.
Using the intelligence across horizons — tactical guidance
Our report’s recommendations are organized by planning horizon to ensure they can be operationalized immediately.
-
0–90 days: Prioritize supplier audits for components with the tightest Q4 2025 lead-time exposures; lock flexible contracts or dual-source critical passives and converter ICs. Initiate driver-stability audits for any product slated for a 2026 refresh.
-
3–6 months: Decide on product architecture rationalization — consolidate SKU complexity where margins are thin, and accelerate development of modular hardware platforms that allow software-enabled differentiation (DSP suites, firmware features). Begin formal discussions with shortlisted silicon partners to secure allocation ahead of ramp cycles influenced by geopolitical restrictions.
-
6–18 months: Execute channel experiments (bundled software subscriptions, creator partnerships, pro-studio pilots) and refine pricing strategies using modeled elasticity insights in the report. For acquirers, run accelerated due diligence on targets identified in the M&A scorecard and structure contingent earn-outs linked to integration milestones.
Practical next steps for executives
-
Procurement leaders: Use our supply-chain risk matrix to re-score your BOM and prioritize dual-sourcing where chip or passive lead times pose >X-week delay risk.
-
Product and R&D leaders: Adopt a modular hardware + SaaS overlay approach to protect ASPs from commoditizing DAC improvements.
-
Commercial leaders: Re-allocate marketing spend toward creator-led programs and competitive demos that show measurable latency and fidelity gains — these convert faster in both consumer and studio channels.
-
Corporate development teams: Leverage our concentration metrics and vendor heatmaps to identify consolidation plays or capability tuck-ins that accelerate time-to-market for pro-level features.
Conclusion — strategic value in 2026
For stakeholders planning 2026 budgets and strategic moves, the sound cards market presents a hybrid opportunity: steady headline growth at a mid-single-digit CAGR, with pockets of high-margin premiumization driven by software and converter innovations. However, supply-chain and regulatory headwinds require a disciplined approach to sourcing and product planning. PW Consulting’s report converts these realities into executable initiatives — from procurement contingencies and NPI blueprints to M&A scorecards and channel experiments — while preserving the detailed subsegment datasets for clients who need the full evidentiary basis for decisive action.
To obtain the full report, including the vendor-level tables, scenario datasets, and downloadable Excel workbooks, visit our report page or contact PW Consulting’s industry practice. The detailed tables are intentionally gated to ensure you receive tailored interpretation and hands-on support for the 2026 decision cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Sound Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Bottom Anti-Reflective Coatings (BARC) Market Valued at USD 962.0 Million in 2025, Set to Grow at a 6.72% CAGR to USD 1,516.7 Million by 2032
By pmarketresearch, 2026-08-12
Worldwide Bottom Anti-Reflective Coatings (BARC) Market — Strategic Outlook for 2026: PW Consulting Industry Brief
PW Consulting’s latest market study on Worldwide Bottom Anti-Reflective Coatings (BARC) synthesizes five years of historical performance and a seven‑year forecast to deliver a decision-grade evidence base for semiconductor stakeholders preparing strategy and capital plans in 2026. Built on a 2025 base year with historical coverage from 2020–2025 and a forecasting horizon of 2026–2032, the report quantifies an accelerating market trajectory (CAGR 6.72%) and translates that trajectory into actionable options for procurement, R&D, manufacturing, and M&A teams.
Worldwide Technical Skills Development Software Market
Why this matters for 2026 decision-makers
-
Macro predictability with tactical complexity: The BARC market is moving from recovery into structurally higher demand driven by advanced lithography adoption and tighter overlay tolerances. Our consolidated market model places global revenues at roughly USD 962.0 Million in 2025, rising above USD 1.02 Billion in 2026 and projecting to approximately USD 1.52 Billion by 2032—a growth path that changes the economics of supply agreements, capacity investments, and vertical integration choices.
Worldwide Anhydrous Borax Market -
Concentration matters: The market exhibits material supplier concentration, with our CR3 and CR5 metrics indicating a marketplace where a small number of specialized chemical OEMs hold outsized influence on price, qualification lead times, and innovation cadence. That structural reality amplifies both supply‑risk and strategic opportunity.
Weather Broadcast Services Market -
Strategic timing: 2026 is a pivotal year for decisions on long‑lead capital, multi‑year supply contracts, and formulation roadmaps—choices made now will lock in cost structures and qualification paths for nodes and lithography platforms being deployed across 2027–2030.
Market trajectory and what the numbers signal
Our topline model captures steady expansion from the mid‑2020s into the early 2030s. After a mid‑cycle rebound through 2023–2025, demand scales meaningfully as fabs migrate toward tighter process windows and advanced lithography variants become more widely qualified. The consensus growth rate embedded in our forecast (CAGR 6.72% across the 2026–2032 horizon) is driven by a combination of fab tool upgrades, increased resist complexity, and differentiated BARC formulations required by next‑generation patterning.
For strategy teams, the implication is clear: vendors who can demonstrate reproducible qualification performance for high‑NA/EUV and immersion platforms will capture premium pricing and faster adoption curves. Conversely, suppliers with narrow product portfolios risk commoditization as customers prioritize multi‑node compatibility and supply security.
Key dynamics shaping supplier economics (operational and regulatory)
-
Raw material pressure: Central monomers and specialty solvents have shown step changes in cost and availability. For example, certain methacrylic derivatives experienced an approximate mid‑single digit percentage increase year‑over‑year due to supply constraints—impacts that are magnified for high‑purity chemistries used in BARC formulations. Procurement teams must model input cost pass‑through and negotiate clauses that reflect commodity and specialty chemical volatility.
-
Regulatory re‑formulation: New restrictions on select aromatic solvents under REACH Annex XVII are forcing European sales to be supported by reformulated product lines or alternative supply chains. R&D roadmaps should therefore prioritize solvent substitution pathways and validate performance parity under accelerated qualification cycles.
-
Trade and transport friction: Tariff actions (including a post‑review tariff structure imposed on certain imports) and shipping surcharges resulting from geopolitical disruptions have introduced incremental landed cost volatility. Even modest per‑kilogram surcharges materially affect small‑volume, high‑value chemicals economics and should be embedded into scenario planning across supplier tiers.
Report deliverables: what PW Consulting puts on your table
This study goes beyond top‑level forecasting. The report is designed as a practicable toolkit for 2026 strategic planning and includes:
-
Proprietary, node‑aware demand models that link lithography adoption curves to BARC demand drivers across the forecast period.
-
Supplier scorecards assessing technical breadth, qualification velocity, manufacturing footprint risk, and commercial flexibility—scored against PW’s procurement playbook.
-
Scenario playbooks for input‑cost shocks, regulatory restrictions, and trade disruptions—each with recommended contractual and operational mitigations.
-
Supplier negotiation tools including model clauses for price pass‑through, volume flex, and qualification cost allocation.
-
High‑level CAPEX needs analysis and a prioritization framework for fabs and chemical suppliers evaluating capacity expansions or backward integration.
To honor the “trailer” principle, we summarize the nature of these deliverables here while reserving the granular tables, plant‑level capacity maps, and downloadable scorecards for the full report—where readers will find the detailed splits and unit economics necessary for transactional decision making.
Competitive landscape — what the leaders are doing
The market is anchored by a set of specialist chemical companies that combine deep formulation expertise with high‑purity manufacturing capabilities. The competitive dynamic is driven by technology partnerships with lithography tool vendors, rapid qualification support for fab customers, and incremental product innovation for EUV and high‑NA systems.
-
JSR Corporation (Tokyo): A leading supplier with recent product introductions targeting EUV and high‑NA compatibility. JSR’s announced launch of a BARC material designed for next‑generation EUV systems in October 2025 signals a strategic bet on premium performance segments and early qualification wins.
-
Dow Electronic Materials / DuPont (Midland, Michigan): Brings broad commercial scale and established formulations for advanced nodes. Their portfolio and global reach make them a natural partner for large fabs seeking predictable qualification paths and supply continuity.
-
Tokyo Ohka Kogyo (TOK, Kawaguchi): TOK has demonstrated capacity commitment, including a targeted production expansion to serve sub‑3nm node demand. Their Kawasaki plant enlargement announced in mid‑2025 highlights the capital intensity and timing considerations for suppliers targeting aggressive node transitions.
-
Shin‑Etsu Chemical (Tokyo): Known for high‑purity materials and strong process support; recent certification activity underscores the ongoing emphasis on documented compliance and customer QA integration.
-
Nissan Chemical Corporation (Tokyo): Focused R&D on formulations adaptable to both 193nm and EUV process windows positions Nissan to participate across multiple lithography choices.
-
AZ Electronic Materials / Merck Group (Darmstadt): European presence and specialty chemistries complement global sourcing strategies, particularly for customers seeking multiple qualified sources.
Collectively these suppliers shape market structure: competitive on innovation, but with entry barriers linked to qualification cycles, cleanroom manufacturing investments, and regulatory compliance. The CR3 and CR5 indicators in our analysis show a market where a few vendors control the majority of volume—informing both supplier negotiation tactics and potential M&A surveillance strategies.
Actionable recommendations for 2026 (short checklist)
-
Lock strategic lead times now: Initiate multi‑year contracting conversations with preferred suppliers to secure qualification slots and capacity windows for 2027–2029 production ramps.
-
Hedge and diversify raw‑material exposure: Negotiate upstream supply agreements for critical monomers and implement dual‑sourcing for solvent classes under regulatory stress.
-
Prioritize reformulation funding: Allocate near‑term R&D budgets to solvent‑substitution and high‑NA compatibility testing to avoid downstream qualification delays in regulated markets.
-
Embed tariff and freight scenarios: Financial planning should include stress tests for import duty and shipping surcharge scenarios that materially alter landed cost calculations.
-
Monitor supplier concentration risk: Use bespoke scorecards (included in the full report) to track supplier health and create contingency plans for rapid requalification where feasible.
How to use this report
PW Consulting’s BARC market study is intended as a working instrument for commercial, operational, and capital allocators. It is tailored for head‑office strategy teams, procurement, fab process engineering, corporate development, and investment committees. The full report contains the granular segment models, supplier share matrices, pricing elasticities, and downloadable negotiation templates referenced in this brief.
For organizations that must transition from insight to action in 2026, the study provides both the forecast horizon and the tactical blueprints necessary to manage cost, quality, and time‑to‑market tradeoffs in a concentrated and technically demanding supply chain.
Next steps
-
Engage PW Consulting for a tailored briefing to map the report’s implications onto your specific node roadmap or supplier base.
-
Access the full dataset and annexes for transaction‑grade figures, supplier-level metrics, and scenario‑specific playbooks.
Contact PW Consulting to schedule a deep‑dive. Our team will walk through the models, validate assumptions against your internal data, and co‑design mitigation strategies that align with your 2026 strategic choices.
For detailed analysis of this topic, please visit the official page: Worldwide Bottom Anti-Reflective Coatings (BARC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Nefopam Hydrochloride Market Poised for 5.5% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Nefopam Hydrochloride Market — Strategic Insights for 2026 Decision-Making
Executive summary
PW Consulting’s latest Worldwide Nefopam Hydrochloride Market report equips executives with a compact, strategy-ready view of a specialty analgesic market entering a phase of measured expansion. The global market — valued at approximately USD 257.4 Million in 2025 — is forecast to grow at a steady compound annual growth rate (CAGR) of 5.5% over the 2026–2032 forecast window, reaching roughly USD 374.4 Million by 2032. Historical dynamics show a recovery and re-acceleration since 2020, underscoring the therapeutic niche’s resilience amid shifting clinical guidelines and regulatory frameworks.
Worldwide Enterprise Semantic Search Software Market
Why this report matters for 2026 planning
- Actionable intelligence for commercial planning: sales channel prioritization, pricing and tender playbooks, and product-form positioning.
- Regulatory and reimbursement context to inform market entry and lifecycle management, including country-level formulary shifts and off-label utilization risks.
- Supply-side diagnostics: supplier risk mapping, capacity assessments, and API sourcing strategies tailored to concentration and certification realities.
- Clinical and innovation landscape signals—patents, late-stage formulation programs, and pivotal trial readouts—that materially affect product differentiation and IP strategies.
What the report contains (practical chapter highlights)
- Market sizing & forecasting: an audited, bottom‑up model spanning 2020–2032 with sensitivity scenarios aligned to regulatory, clinical, and reimbursement inflection points.
- Commercial playbooks: segmented GTM scenarios (hospital-parenteral vs. outpatient-oral), tender tactics, and sample pricing frameworks calibrated to real-world procurement data.
- Regulatory & payer intelligence: dossier readiness checklists, national formulary snapshots, and reimbursement levers that influence uptake velocity.
- Supply-chain and manufacturing dossier: GMP/CEP/EDMF filing implications, secondary packaging constraints, and contingency sourcing for API and sterile injectable capacity.
- Risk & opportunity matrix: competitor moves, IP timelines, and clinical evidence milestones with quantified impact on revenue trajectories under conservative, base, and aggressive adoption cases.
- Due diligence toolkit: vendor scorecards, M&A valuation multipliers, and integration checklists for acquiring API or finished-product capabilities.
Market dynamics and strategic implications
The nefopam hydrochloride market sits at the intersection of several stable and structural trends: continued emphasis on opioid-sparing multimodal analgesia, pockets of high institutional demand (perioperative settings), and selective geographic reimbursement regimes that favor lower-cost, non-opioid options. The combination of clinical utility and relatively narrow therapeutic positioning produces steady demand growth rather than disruptive expansion.
Sterile Surgical Impervious Drape Market
- Demand drivers: Multimodal analgesia adoption and documented opioid-sparing effects are primary growth levers. Hospital protocols and perioperative analgesia pathways will remain the dominant adoption vector.
- Regulatory & reimbursement pressure: National formularies and drug tariff assessments have become decisive. While nefopam holds marketing authorizations across several European jurisdictions, it remains unapproved by the U.S. FDA — a factor that shapes global launch strategies and prioritization.
- Supply considerations: The market exhibits moderate concentration (CR3 ~58.4%, CR5 ~74.2%), indicating that a small number of suppliers account for the lion’s share of active ingredient and finished-product supply. This has meaningful implications for price volatility, qualification timelines, and strategic inventory planning.
- Clinical & IP dynamics: New patents and randomized clinical evidence — including recent hospital-led trials — are creating differentiation opportunities for reformulated products or novel fixed-dose combinations aimed at acute and chronic indications.
Competitive landscape — strategic read on key players
Our competitive assessment synthesizes manufacturing credentials, regulatory filings, and commercial footprints to highlight where value is concentrated and where gaps exist for new entrants or consolidators.
Elevator Speed Limiter Safety Clamp Market
- Polpharma (Poland) — A certified API producer with GMP credentials and regulatory filings supporting commercial-scale supply. Strategically positioned for European tender opportunities; attractive target for companies seeking EU-based API security and compliance provenance.
- Global Calcium (India) — Low-cost API manufacturer and exporter with global trade footprints. Their pricing and export capability make them an anchor supplier for cost-sensitive markets but raise diligence needs around long-lead-time qualification and secondary certification paths.
- PMC Isochem (France) — Offers regulatory filings such as CEP/COS and European dossier experience; a logical partner for companies prioritizing fast-track market access in regulated jurisdictions.
- Emcure Pharmaceuticals, Micro Labs, Maiden Group (India) — Integrated manufacturers with finished-product capability. These organizations can support both branded and generic plays, and they present M&A or contract-manufacturing opportunities for companies lacking finished-dose capacity.
- CF Pharma & PRG Pharma — Publicly listed suppliers and regional API vendors; useful options when diversifying supplier base to mitigate single-source risk.
- Taj Pharma (India) — Holds finished-dose offerings in both injectable and oral formats, making them a potential partner for rapid commercial scale-up in markets accepting imported finished products.
- Guangzhou Green Cross (China) — Adds capacity diversity but requires targeted regulatory and quality due diligence for scale supply in high-regulation markets.
Recent developments to watch (implications for 2026)
- Patent grants for optimized formulations (e.g., Maxona’s program) expand IP-led differentiation opportunities and may complicate generic substitution in markets where patents are enforced.
- New randomized clinical data (hospital-based perioperative trials) can reshape guideline language and accelerate formulary adoption in cardsurgical and orthopaedic pathways.
- Formulary reassessments and drug tariff updates in major national systems underscore that pricing decisions and reimbursement banding will materially influence uptake in the next 12–18 months.
Strategic playbook: five pragmatic moves for 2026
- Prioritize regulated markets via dossier readiness: For firms targeting high-reimbursement markets, invest early in CEP/EDMF/ASMF filings and alignment with national formularies to compress time-to-tender.
- Diversify API sourcing with tiered qualification: Maintain a primary certified supplier and two secondary sources (one low-cost exporter, one regional-certified manufacturer) to hedge against batch failures, export controls, or raw material shortages.
- Leverage clinical evidence to secure formulary positions: Sponsor targeted, high-quality investigator-initiated trials (e.g., perioperative analgesia, opioid-sparing endpoints) to build local guideline support and payer-case narratives.
- Assess acquisition targets in concentrated pockets: Given the market’s moderate concentration, selective M&A to add CEP/EDMF-certified API capability or finished-dose injectable capacity can create quick scale and margin uplift.
- Develop tender and pricing playbooks: Use a value-based pricing approach in hospital tenders that quantifies opioid-sparing benefits, length-of-stay reductions, and potential analgesia-related cost offsets.
What we intentionally withhold here (and why)
To preserve the report’s commercial utility as a primary source of truth, this press release deliberately omits downloadable segment-level tables and detailed regional/applicational breakdowns. The full report contains granular models — including regional demand curves, product-form mix, and application-specific uptake scenarios — which are essential for detailed financial modeling, tender response preparation, and M&A diligence. PW Consulting’s approach is to provide executives with high-fidelity strategic direction here while driving direct access to the complete datasets and modeling workbooks in the full report.
How to use this intelligence in your 2026 planning cycle
- Integrate the report’s demand scenarios into your 2026 budgeting and capacity planning cycles to avoid over- or under-investing in sterile injectable lines.
- Align regulatory investments (e.g., dossier filings) to the fastest-adopting markets identified in the full report; sequence commercial launches to maximize early cash flow.
- Use the supplier scorecards and risk heatmaps provided in the report during procurement negotiations and contingency planning with existing suppliers.
- If considering M&A, apply the report’s valuation framework and integration checklist to identify high-impact targets and realistic timelines for synergy capture.
Conclusion and next steps
The nefopam hydrochloride market will not produce headline-busting growth, but it offers steady, defendable value to companies that execute with clinical, regulatory, and supply-chain discipline. With a forecasted base-case CAGR of 5.5% and a projected market value north of USD 370 Million by 2032, opportunities exist for market share gains through differentiated formulations, robust clinical evidence generation, and supply consolidation.
For procurement teams, regulatory leads, and corporate strategists preparing 2026 roadmaps, PW Consulting’s complete Worldwide Nefopam Hydrochloride Market report supplies the data, tools, and playbooks needed to move from strategic intent to executable plans. Access to the full dataset and model is available via our report distribution channels — the detailed segmentation, regional allocations, and scenario workbooks are included only in the full product.
For detailed analysis of this topic, please visit the official page: Worldwide Nefopam Hydrochloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Venetoclax API Market Poised for Rapid Expansion at 12.51% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Venetoclax API Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
As oncology generics and contract manufacturing networks reposition for the next commercialization window, PW Consulting’s latest Worldwide Venetoclax API Market report establishes a fact-based runway for strategic investment, sourcing and portfolio decisions in 2026. The aggregated market for Venetoclax active pharmaceutical ingredient (API) has expanded rapidly over the past half-decade, rising from a modest baseline in 2020 to an estimated USD 260.17 Million in our base year (2025). Under our central-case assumptions the market grows at a compounded annual growth rate (CAGR) of 12.51% across the 2026–2032 forecast interval, reaching roughly USD 593.85 Million by 2032.
Worldwide Taxi & Limousine Software Market
This briefing highlights the operational and competitive inflection points we believe will matter most to manufacturers, CDMOs, investors and downstream formulators in 2026 — while preserving detailed, proprietary subsegment tables and contractual intelligence for the full report available on our site.
Parallel Constant Watt Heating Cable Market
Why 2026 is a strategic hinge year
-
Momentum into generic entry windows: Patent and exclusivity timelines for the reference drug create a predictable cadence for generic entrants, licensing activity and litigation risk. Key composition-of-matter and exclusivity expirations surface across the next several years and will shape supply-side timing for large-volume API contracts.
Worldwide Scuba Diving Clothing Market -
Accelerating market scale: From our historical series (2020–2025) and modeled scenarios, 2026 represents the first year in our forecast where absolute annual market growth meaningfully accelerates versus the historical average, reflecting both increased demand from anticipated generic launches and wider clinical use in hematologic indications.
-
Commercial readiness pressure on supply chains: Ramp plans for API producers, quality regulatory filings (DMFs/EDQMs/CEPs) and finished-dosage manufacturers must be aligned in 2026 to capture the fastest-growing share of the 2026–2032 opportunity.
Market trajectory — what the numbers mean for resource allocation
The transition from USD 260.17 Million in 2025 to an expected USD 290.78 Million in 2026 (our first forecasted year) reflects a market that is both expanding and undergoing structural change. At a 12.51% CAGR through 2032, total market value nearly doubles by the end of the forecast period — a growth path that rewards early capacity investment, robust quality systems, and commercial partnerships that ensure offtake.
For CFOs and corporate strategists, these aggregate values justify staged capital deployment: secure short-term capacity with modular footprints in 2026–2027, and plan for scale-out options (additional reactors, isolation suites, secondary purification lines) as demand crystallizes toward the latter half of the decade. For procurement and CMO sourcing leads, the implication is clear — begin multi-source qualification in 2026 to mitigate supplier concentration and logistics risk while locking favourable terms with capable suppliers.
Key market dynamics shaping near-term strategy
- Intellectual property and timing: The industry’s commercial calculus is governed by patent and exclusivity milestones. The central composition-of-matter patent remains a determinative factor for originator and generic strategies; pediatric and secondary exclusivities further extend windows in certain jurisdictions. These timelines should be embedded in go/no-go investment models and licensing term sheets.
- Raw material complexity and cost pressure: Venetoclax synthesis relies on advanced heterocyclic chemistry that uses specialized intermediates (indole- and pyrazole-based building blocks). These inputs inflate small-batch material costs substantially and penalize low-yield routes. Process chemistry optimization and backward integration or secured supplier relationships for these intermediates are proven levers to compress unit economics.
- Reimbursement and downstream economics: Branded and biosimilar pricing environments inform the ceiling for generic pricing and commercial margins. Reimbursement settings in core markets materially affect the demand profile for competitive offerings, and manufacturers should model multiple reimbursement scenarios when sizing their market-entry economics.
- Supply concentration and regulatory scrutiny: A majority of global Venetoclax API capacity is concentrated among manufacturers in Asia. This concentration delivers cost advantages but also raises sourcing risk in the event of regulatory actions or trade disruptions. Dual-sourcing strategies and proactive quality investments (e.g., timely DMF/CEP/EDQM filings and transparent inspection readiness) are essential mitigation tactics.
Competitive landscape — what separates winners from followers
Our market-concentration metrics indicate a focused supplier landscape: the top three firms control a sizeable majority of market share, and the top five command over four-fifths of the market by value. This level of concentration creates both barriers and opportunities. Established API manufacturers with regulatory dossiers and inspection-ready facilities are natural partners for finished-dosage producers seeking rapid entry; conversely, well-capitalized newcomers can capture share by offering differentiated guarantees — for example, capacity reservation, price hedging on critical intermediates, or enhanced quality/traceability provisions.
Representative profiles in the competitive set illustrate the different strategic postures we observe:
- MSN Laboratories (Hyderabad, India) : High-purity Venetoclax API production with multiple DMFs filed with major regulatory bodies. Their model emphasizes global generic supply, and their regulatory positioning makes them a prime counterparty for large-volume offtake agreements.
- Hetero Drugs (Hyderabad, India) : A commercial-scale API producer holding CEP certification, focusing on continuity of supply to finished-dosage manufacturers. Their certification profile reduces lead time for EU-bound partners.
- Aurobindo Pharma (Hyderabad, India) : Operates US FDA-approved facilities with a focus on oncology APIs for export markets. Their compliance track record is an asset in price-sensitive, regulation-intensive geographies.
- Senova Technology (Tianjin, China) : A specialist producer maintaining regional DMF filings and GMP compliance aimed at international supply chains. Their technical know-how supports customers seeking bespoke process development and supply continuity.
Notable transactional signals: a high-profile patent settlement in late 2022 clarified some pathways for generic entrants and has been an accelerant for API producers to scale capacity and file regulatory dossiers. Market participants should treat such settlements as leading indicators for supplier behaviour and contract timing.
What the PW Consulting report delivers — actionable intelligence
Our full report translates market dynamics into executable guidance across the commercial stack. Key practical components include:
- Scenario-modeled demand curves and capacity utilization templates that allow procurement, manufacturing and investment teams to simulate 12-, 24- and 36-month ramp trajectories.
- Supply-chain due diligence checklists tailored to high-complexity oncology APIs — encompassing regulatory dossier maturity, process route validation, impurity control strategies, and audit readiness.
- Contract structures and sample commercial clauses for capacity reservation, price escalation, quality deficiencies and force majeure specific to high-value oncology APIs.
- Regulatory intelligence — a readiness scorecard for DMF/EDQM/CEP filings and recommended timelines to support rapid market entry or defend against inbound generics.
- Risk-adjusted valuation models for M&A and minority investments in API producers and CDMOs, with sensitivity analyses for raw material price shifts and accelerated generic uptake.
For confidentiality and commercial reasons this briefing omits the granular regional and application-level breakdowns — those segment tables and supplier-level volumes are available in the full report and client dashboards.
Strategic imperatives for 2026
- Manufacturers and CDMOs: Finalize quality dossier readiness and pursue at least one regulatory filing in 2026 if you intend to serve major export markets by the 2027–2029 window. Invest selectively in route optimization to reduce reliance on expensive intermediates.
- Finished-dosage producers: Begin multi-vendor qualification in 2026 and negotiate staged offtake agreements tied to inspection milestones to avoid supply shocks while keeping unit costs competitive.
- Investors and M&A teams: Prioritize targets with validated DMFs/CEPs, demonstrated batch reproducibility and transparent quality systems; apply our scenario models to stress-test valuations under faster-than-expected generic penetration.
- Procurement and risk managers: Build inventory buffers for critical intermediates, and structure contracts with capacity options. Contingency playbooks for regulatory hold scenarios should be operational by mid-2026.
Conclusion — how PW Consulting helps you act in 2026
The Venetoclax API market presents a pronounced growth opportunity driven by therapeutic demand, patent dynamics and the readiness of a concentrated set of suppliers. Our analysis shows the market’s aggregate size and growth rate create strong incentives for well-coordinated action in 2026: firms that align regulatory, operational and commercial plans early will capture favorable positions across the 2026–2032 expansion.
PW Consulting’s full report contains the segment-level tables, regional breakdowns, supplier scorecards and transactional templates you need to convert strategy into execution. To access the complete dataset and interactive scenario tools — including supplier-level capacity schedules and contract playbooks — please visit our report page. Note: we intentionally withhold detailed subsegment figures in this public briefing to preserve the proprietary intelligence contained in the paid report.
For detailed analysis of this topic, please visit the official page: Worldwide Venetoclax API Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Pt Paste for Gas Sensor Market to Expand at a 6.45% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Pt Paste for Gas Sensor Market — Strategic Imperatives for 2026
Executive overview
PW Consulting’s new market study for Platinum (Pt) Paste used in gas sensors frames an operationally focused roadmap for executive teams planning programs and capital allocation in 2026. The market has demonstrated sustained expansion through the 2020–2025 period, rising from the low‑seventies to approximately USD 110 Million in the 2025 base year, and is forecast to continue growing into the 2030s. Our modeling shows a compound annual growth rate (CAGR) of 6.45% over the 2026–2032 forecast window, with the market approaching a materially larger scale by the end of the period. Those macro dynamics—combined with acute upstream supply tightness in platinum and accelerating price volatility—create both opportunity and execution risk for sensor OEMs, materials suppliers, and investors.
Greenhouse Solar System Market
Why this matters for 2026 decision-making
- Procurement & cost management: Platinum feedstock dominates cost of goods for Pt paste formulations. The market experienced supply contraction and sharp price moves in recent market cycles, creating a need for active hedging, long‑term offtake arrangements, and recycled stream programs. Companies that treat feedstock strategy as a strategic asset—rather than a purchasing line item—will protect margins and continuity in 2026.
- Product qualification timelines: Automotive and industrial sensor OEMs operate long qualification cycles. With the market trajectory and tighter materials availability, front‑loading material evaluation and dual‑sourcing strategies in 2026 will materially reduce time‑to‑market risk for new sensor platforms.
- R&D and formulation choices: Variations in firing profile, conductor resistance, and adhesion chemistry translate directly into sensor performance, yield and cost. Investing in co‑development with established Pt paste manufacturers—covering low and high‑temperature sintering routes and Pt‑alloyed formulations—will accelerate differentiation in next‑generation sensors.
- Supply chain resilience & sustainability: Recycling of PGM content and closed‑loop sourcing will move from CSR checkbox to operational necessity. In 2026, firms that invest in PGM recycling, strategic stockpiles, and supplier partnerships will gain negotiating leverage and reduce exposure to spot price shocks.
- Regulatory compliance & market access: Pt paste formulations for gas sensors are constrained by RoHS2 and related restricted‑substance standards. Ensuring materials and manufacturing processes meet these requirements is non‑negotiable for global automotive and consumer applications.
Report scope — what PW Consulting delivers (practical modules)
- Proprietary market sizing & forecast model (2020–2032) with scenario runs reflecting spot, constrained, and normalized PGM supply settings. Includes sensitivity tables for feedstock price and demand elasticity.
- Cost‑to‑serve and bill‑of‑materials (BOM) impact tools that translate platinum price movement into P&L stress points for common sensor architectures.
- Supplier benchmarking and technical scorecards — independent assessment of manufacturing footprints, core formulations (screen‑printable, fritted, thick film), firing temperature regimes, and qualification status against automotive and industrial standards.
- Product & process playbooks covering paste selection, firing profiles, printed line widths, adhesion testing, and accelerated life‑cycle protocols for engineers and procurement teams.
- Supply chain risk matrix and negotiation playbook addressing hedging, recycling, consignment stock, and collaborative product development agreements.
- M&A & partnership roadmap identifying priority targets and strategic partnering constructs for vertical integration or regional capacity expansion.
Competitive landscape — strategic positioning of core suppliers
The Pt paste supply chain is characterized by a mix of specialized PGM material houses and diversified electronic materials firms. Leading suppliers combine metallurgical know‑how with formulation capability and customer qualification track records. Key strategic observations:
Worldwide Blackcurrant Seed Oil Market
- TANAKA Precious Metals (Japan) — Strengths lie in integrated powder‑to‑paste manufacturing and a tranche of formulations tailored for heaters, leads and porous electrode structures. Their product families include low‑resistance and high‑resistance heater pastes, porous electrode pastes and Pt‑alloys (Pt/Pd, Pt/Rh, Pt/Au). This breadth supports deep co‑development with automotive sensor OEMs that prioritize long‑life performance and high‑temperature firing.
- Heraeus Electronics (Germany) — A leader in thick film conductor pastes, Heraeus combines metallurgical variants (pure Pt, noble‑metal alloys) with a focus on solderability and chemical resistance for fuel and oxygen sensing. Recent technical documentation updates reflect an emphasis on robustness for fuel‑sensor environments—an important signal for OEMs seeking proven qualification packages.
- Dycotec Materials (UK) and Ferro (US) — These players offer screen‑printable and thick film options optimized for practical manufacturing constraints: lower firing ranges, fine‑line printing capability, and repeatable fired resistivity. Their value proposition is speed to qualification and manufacturing yield improvement.
- Johnson Matthey & Umicore — With deep PGM portfolios, catalytic expertise, and recycling capability, these firms are strategic partners for clients seeking both feedstock security and advanced material formulations—especially where catalytic or electrochemical performance is a differentiator.
- MANA Metal & American Elements — Regional and specialty suppliers offering competitive electrodes and pastes; attractive for localized sourcing strategies and cost optimization where regional content or supply locality is prioritized.
Collectively, the supplier population skews toward a mid‑to‑high concentration profile: a handful of established suppliers command a substantial share of qualified, automotive‑grade capacity, while smaller specialists and regional producers address niche and cost‑competitive segments. Recent vendor moves—such as updated technical data sheets and upstream market commentary—underscore an industry adapting both product portfolios and go‑to‑market messaging to material market stress.
Worldwide Angle Valves Market
Dynamics to monitor in 2026
- Platinum supply & pricing volatility: Primary PGM supply contracted recently, pressuring stock levels and contributing to sharp price appreciation. These dynamics will materially affect procurement tactics, inventory policy and R&D prioritization in 2026.
- Regulatory and quality requirements: RoHS2 compliance and automotive qualification cycles continue to be gating factors for new entrants. Manufacturers should avoid shortcuts in materials certification to prevent costly rework.
- Formulation innovation: Alloying strategies (e.g., Pt/Pd, Pt/Rh) and firing‑profile adaptations present pathways to performance/cost tradeoffs. Targeted co‑development with suppliers can reduce reliance on pure‑Pt loadings while preserving sensor performance.
- Recycling & circularity: Practical recycling of PGM‑rich scrap (printed substrate, end‑of‑life sensors) is becoming a differentiator for cost and environmental reporting. 2026 is the year to operationalize recycling pilots into commercial flows.
Actionable 2026 playbook — five immediate moves
- Implement feedstock risk controls: combine long‑term purchase agreements, limited spot exposure, and recycled‑metal programs to stabilize cost of goods.
- Start dual‑qualification tracks for paste suppliers in parallel—prioritize suppliers with proven automotive/industrial qualification history and those offering co‑development resources.
- Invest 1–2 engineering cycles in paste optimization tied to yield improvement and miniaturization; small formulation gains cascade into substantial cost and performance benefits.
- Negotiate collaborative inventory models: consignment, vendor‑managed inventory, or buffer stock agreements at regional hubs to offset supply chain interruptions.
- Embed PGM sensitivity scenarios into product business cases and pricing models to ensure rapid commercial response if raw material dynamics shift.
Why PW Consulting’s report is a must‑have for 2026
The study blends granular technical insights (firing regimes, printing parameters, alloy options) with executable commercial playbooks (procurement structures, recycling implementation, supplier scorecards). Our forecast and scenario engine enables finance and product teams to stress‑test business plans against plausible platinum market outcomes. For leadership teams evaluating supplier strategies, qualification roadmaps or M&A plays in the materials tier, this report converts market intelligence into operational checklists and negotiation leverage.
To access the full dataset, supplier scorecards, and the interactive forecast model—designed to be embedded into procurement and product development workflows—visit the PW Consulting report page or contact our industry practice for a tailored briefing. The macro runway is constructive, but the 2026 battleground will be won by teams that pair technical differentiation with disciplined feedstock and supplier strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Pt Paste for Gas Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide PDMAT Market to Reach USD 638.7 Million by 2032, Growing at 7.5% CAGR (2026–2032); Asia Pacific Leads with USD 225M in 2025
By pmarketresearch, 2026-08-12
Worldwide PDMAT Market — Strategic Briefing (PW Consulting)
Executive summary
PW Consulting's latest Worldwide PDMAT Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032) delivers an actionable intelligence package for executives, procurement leads, R&D heads and investors preparing decisions in 2026 and beyond. Our bottom‑up model values the global market for pentakis(dimethylamino)tantalum (PDMAT) at USD 385.0 Million in 2025 and projects a steady trajectory to reach approximately USD 638.7 Million by 2032, implying a compound annual growth rate (CAGR) of 7.5% across the forecast window.
Worldwide DNS Protection Tool Market
This briefing highlights the strategic implications of those macro trends, synthesizes the technology and supply‑chain dynamics that matter to semiconductor supply‑chain decision makers, and summarizes competitive positioning among the leading suppliers—while deliberately withholding detailed subsegment allocations. This “trailer” approach demonstrates analytical depth and preserves the sensitive subsegment granularity for subscribers who visit the source portal for the full dataset and actionable tables.
Worldwide Express and Parcel (CEP) Market
Why this matters for 2026 decision cycles
- Capital planning and inventory strategy: The projected mid‑single‑digit to high‑single‑digit growth in aggregate PDMAT demand supports cautious capacity expansion for upstream precursor manufacturers and rational inventory stocking points for chipmakers. Buyers should calibrate safety stock and contractual volume options to avoid both supply shortages and costly overhangs as node transitions continue.
- Materials roadmap alignment: PDMAT remains a critical precursor for TaN barrier layers where copper interconnect scaling and reliability are required. Technology roadmaps for sub‑22nm and advanced interconnect integration mean that material purity, packaging, and delivery reliability will directly influence fab yield and qualification timelines.
- M&A and partnership signal: With market concentration skewed—our analysis shows the top three firms control roughly 65.5% of the market and the top five about 82.2%—strategic buyers and private equity should expect continued consolidation and selective vertical partnerships to secure supply in regions with increasing semiconductor build‑outs.
Market dynamics and growth drivers
The PDMAT market is principally driven by semiconductor wafer fab capacity growth, advanced node migration requiring robust Cu diffusion barriers, and increasing adoption of atomic layer deposition (ALD) and chemical vapor deposition (CVD) techniques. While absolute volumes remain small relative to other chemical markets, unit prices and purity requirements create outsized economic and technical impact across device BOMs.
Worldwide Amps & Effects Market
Key demand levers:
- Continued investment in advanced logic and memory fabs—accelerating demand for high‑purity TaN precursors.
- Technology retention benefits from ALD/CVD process control, which favors precursors that are well‑qualified across multiple toolsets.
- Regional fab build programs that create localized procurement dynamics and qualification cycles (details on region splits are reserved for the full report).
Technology, synthesis and high‑purity manufacturing
PDMAT synthesis and purification are core differentiators. The compound is commonly synthesized via a metathesis route (TaCl5 + LiNMe2) followed by multi‑stage purification to meet high‑volume manufacturing (HVM) specs. To be fit for advanced Cu barrier applications, manufacturers target ultra‑high purity levels—achieving specifications often reported in the literature (for example, chloride content in sub‑10 ppm ranges and oxygen at trace levels) through proprietary distillation, recrystallization and handling processes.
Two technical realities flow from this:
- Process compatibility: ALD/CVD tool vendors and fabs will prioritize precursors with demonstrated thermal stability, controlled vapor pressure behavior, and low impurity profiles that do not compromise dielectric integrity or leakage performance.
- Manufacturing scale‑up complexities: Scale‑up from research grades to HVM requires not only chemical synthesis expertise but also investments in inert‑atmosphere handling, containerization and qualification protocols—areas where incumbent suppliers have invested heavily.
Regulatory and handling constraints
PDMAT is highly air‑ and moisture‑sensitive and is generally classified for research and industrial use rather than consumer applications. As a result, logistics and packaging are not minor details; they are determinative. Industry practice includes supply in glass ampules, metal ampoules/bubblers, and other specialized containers to preserve purity and support safe integration into ALD/CVD tool chains.
For procurement and operations teams this translates into vendor selection criteria that include demonstrated cold‑chain/inert‑packaging capability, certified handling SOPs, and transparent material safety documentation to prevent contamination and ensure quick qualification cycles on production tools.
Competitive landscape — profiles and strategic positioning
PDMAT supply is dominated by a group of specialized chemical firms and advanced materials manufacturers. Our report evaluates capabilities across product purity, scale, geographic footprint, packaging and customer support. Selected industry participants reviewed include:
- Merck KGaA (EMD Group) — Global reach and a broad semiconductor materials portfolio; strength in supplying high‑purity PDMAT as a solid precursor for ALD/CVD with established distribution in major fab regions.
- Ereztech — U.S.‑based supplier notable for flexibility in small and bulk volumes and customization of packaging formats including glass ampules and metal bubblers, valuable for shorter qualification cycles and prototype throughputs.
- Strem Chemicals (Ascensus Specialties) — Research‑grade supplier with consistent quality for early‑stage development and academic collaborators.
- Northern and Taiwan‑based manufacturers (e.g., Nanmat Technology, TOPCO Scientific, PentaPro Materials) — Regional manufacturing proximity to major fabs, with product lines extending across ALD/CVD precursors that can shorten supply chains.
- China‑based suppliers (e.g., Argosun, Sinocompound) — Emerging contenders with focus on high‑purity offerings and competitive cost structures; attention needed on qualification support and logistics for HVM customers.
- Specialty European makers (e.g., DOCK Chemicals) — Ultra‑high purity producers addressing niche high‑reliability needs in advanced fabs.
Our competitive assessment emphasizes: product purity and consistency; supply security and scale; customer technical support; and packaging/handling competency. Buyers should layer these criteria into scorecards during 2026 sourcing rounds.
Supply‑chain risk map and mitigation
- Single‑sourcing risk: Given market concentration, reliance on single vendors for mission‑critical grades increases vulnerability. Mitigation includes multiple qualified sources, staggered delivery contracts and technology transfer agreements where appropriate.
- Logistics sensitivity: Air‑ and moisture‑sensitivity requires specialized transport and bonded inventory near fab sites. Investing in regional buffer stocks and local packaging partners reduces lead‑time risk.
- Raw material inputs: Feedstock availability and price volatility (for tantalum and organometallic precursors) necessitate forward purchasing and supplier hedging strategies for large fabs.
What the full report delivers (practical content)
The full PW Consulting report is structured for immediate operational use by purchasing, process integration, and strategy teams. Highlights include:
- Quantitative market model (historical 2020–2025; forecast 2026–2032) with scenario sensitivity analysis to reconcile capacity additions, fab ramp schedules and adoption rates of ALD vs CVD toolsets.
- Supplier scorecards with comparative assessments across purity, regulatory compliance, packaging options, geographic presence and qualification lead times.
- Supply‑chain playbooks—procurement levers, inventory optimization templates, and contracting language to secure both price and continuity for high‑value precursors.
- Risk heatmaps and contingency plans for logistics, raw material shocks and regulatory constraints affecting handling and transport of moisture‑sensitive organometallics.
- Executive decision frameworks and recommended KPIs for 12–36 month roadmaps, tailored to fab size and technology node profiles.
Note: To preserve commercial sensitivity and discourage misuse of granular subsegment tables, we intentionally withhold detailed regional and application breakdowns in public summaries. The full dataset, including downloadable spreadsheets and supplier qualification templates, is available to report subscribers.
FAQ — practicalities procurement teams ask
- How is PDMAT typically supplied? — Suppliers utilize specialized packaging such as glass ampules, metal ampoules/bubblers and sealed bottles under inert atmosphere to maintain purity and ease integration into ALD/CVD delivery systems.
- What purity targets are required for HVM? — Ultra‑high purity profiles with extremely low chloride and oxygen contamination are expected; many HVM customers demand multi‑stage purification benchmarks and trace impurity analytics as part of qualification.
- Are there regulatory limits on use? — Beyond chemical safety classifications, PDMAT handling requirements (inert atmosphere, specialized packaging, transport controls) are the principal compliance considerations for industrial use. It is generally not intended for medicinal or consumer uses.
How to use this intelligence in 2026 planning
For 2026, executives should prioritize three immediate actions:
- Fast‑track multi‑vendor qualification for at least one alternate supplier per critical precursors group and codify packaging and handling acceptance criteria.
- Align capital procurement timing with the forecasted market trajectory—use our mid‑case model as a base and test two downside/upside scenarios for procurement commitments.
- Integrate supplier scorecards into supplier development programs to close gaps in analytics, packaging capability and regional logistics ahead of planned ramp windows.
Methodology note
PW Consulting’s market sizing synthesizes supplier shipment data, vendor financial disclosures, production capacity mapping and primary interviews with fab process engineers and procurement leads. Base year is 2025; historical series covers 2020–2025; our forecast extends 2026–2032 and assumes a blended CAGR of 7.5% across the forecast period. Market concentration metrics shown in this briefing reflect our assessment of share distribution among leading suppliers and are included to help stakeholders gauge competitive intensity and sourcing risk.
Conclusion — strategic takeaway
PDMAT remains a strategic materials segment: small in physical volume but highly consequential for semiconductor yield, reliability and scaling. The projected growth to the end of the decade reinforces the need for disciplined supplier strategies, proactive qualification of alternate sources and investment in packaging and logistics. PW Consulting’s full Worldwide PDMAT Market report equips leaders with the quantitative scenarios, supplier scorecards and procurement playbooks needed to convert market forecasts into robust 2026 tactical plans.
For access to the full dataset, supplier matrices and downloadable procurement templates, please visit our report page or contact our industry practice team for an executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide PDMAT Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Natural Aroma Chemicals Market to Expand at 6.8% CAGR, Surging to USD 3,968.75 Million by 2032
By pmarketresearch, 2026-08-12
Worldwide Natural Aroma Chemicals Market 2026: Strategic Imperatives for Leaders — A PW Consulting Preview
As companies prepare their 2026 strategic plans, natural aroma chemicals have moved from niche premium positioning to a mainstream operating imperative across flavor, fragrance, and personal-care value chains. Our latest market study, based on a comprehensive historical series (2020–2025) and a seven‑year forecast (2026–2032), demonstrates that the global natural aroma chemicals market is maturing into a resilient growth engine. The market reached approximately USD 2.50 billion in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 6.8%, driving the sector toward an expected near‑USD 4.0 billion by 2032. For senior executives evaluating portfolio prioritization, supplier strategies, or M&A in 2026, the implications are immediate and actionable.
Industrial Process Fine Bubble Generator Market
Why this preview matters for 2026 decision cycles
-
Evidence‑based momentum: The mid‑cycle acceleration captured between 2022 and 2025 signals structural demand — not a short‑lived fad — underpinned by reformulation mandates, consumer clean‑label preferences, and substitution of petrochemical routes.
LED Poultry Light Market -
Policy and procurement convergence: Regulatory constraints (notably IFRA and REACH) are compressing innovation cycles and supplier qualification timelines. Procurement and regulatory teams must align earlier in R&D to avoid costly late‑stage swaps.
Worldwide Church Presentation Software Market -
Value chain re‑engineering: Feedstock volatility and trade policy (including new reciprocal tariff layers implemented in 2025) are prompting a reconsideration of sourcing geographies, inventory strategies, and localized production versus global centralized supply.
Market trajectory: What the headline numbers tell us
Between 2020 and 2025 the market roughly doubled in scale from the low‑billion area to USD ~2.5 billion in 2025, reflecting a combination of rising unit demand in personal care and food & beverage, price mix effects toward premium natural extracts, and early commercialisation of biotech‑derived molecules. Our base‑case forecast — 2026–2032 at a 6.8% CAGR — implies steady expansion to just under USD 4.0 billion by 2032 under current policy and technology trajectories. The path is not linear: the model embeds mid‑term inflection points tied to regulatory updates, raw material shocks, and commercial ramp‑ups of precision‑fermentation players.
Key market dynamics shaping 2026 strategies
-
Regulatory reformulation pressure: IFRA and REACH remain primary drivers of reformulation toward cleaner, natural, and lower‑risk molecules. Companies with proactive regulatory intelligence and reformulation playbooks will shorten time‑to‑shelf and protect gross margin.
-
Feedstock and input cost volatility: Essential oils — the primary upstream feedstock — continue to exhibit price and availability swings. A complementary data point: the global essential oils market registered multi‑billion USD scale in 2025 and is forecast to grow further in 2026. Ingredient manufacturers must hedge exposure and redesign contracts that share risk across suppliers and buyers.
-
Biotechnology is crossing the chasm: Precision fermentation and biotech production routes are moving from pilot to commercial scale, delivering high‑purity natural compounds with potentially lower carbon footprints. Early adopters of biotech sourcing are positioning for cost and sustainability leadership.
-
Sustainability credentials as market currency: Lifecycle metrics (including product carbon footprint and rPCF disclosures) are becoming table stakes for enterprise customers. Recent commercial launches with reduced product carbon footprints demonstrate how suppliers are using rPCF to win shelf space and long‑term contracts.
-
Trade and tariff risk: New tariff constructs introduced in 2025 add granularity to sourcing decisions. For many buyers, the optimal supply network is becoming a hybrid of regional production hubs and strategic global suppliers to manage duty exposure and service levels.
Competitive landscape — strategic takeaways
The market exhibits moderate concentration: the top three and top five players control meaningful but not dominant shares (CR3 at roughly 28.5% and CR5 at roughly 42.2%). That structure creates a competitive field where scale matters for R&D and distribution reach, yet niches remain defendable for focused specialists.
-
Global integrators (e.g., longstanding flavor and fragrance majors) continue to leverage multi‑channel distribution, deep formulation expertise, and sustainability investments to secure strategic CPG partnerships. These players are expanding portfolios via biotech routes and targeted product launches that foreground carbon and traceability metrics.
-
Specialist natural houses and essential‑oil specialists retain advantages in botanical sourcing, provenance storytelling, and high‑margin fine fragrance segments. Their value proposition is strengthened by vertical integration into farm‑level sourcing and seasonal harvest management.
-
Regional and emerging suppliers are increasingly relevant for localized supply and cost competitiveness — especially where tariff exposure and just‑in‑time requirements favor near‑shoring.
Recent strategic moves illustrate these dynamics. Major suppliers have launched reduced‑product‑carbon‑footprint (rPCF) ingredients and expanded biotech‑derived portfolios, while others have invested in new production capacity for bio‑sourced musks and pine‑based ingredients. Such developments are not isolated product announcements; they represent a reallocation of R&D, capital, and commercial effort toward traceable, lower‑carbon supply chains.
What PW Consulting’s full report delivers (actionable, not academic)
-
Proprietary market model: Scenario‑driven forecasts (base, downside, and accelerated biotech adoption) with sensitivity levers for raw material prices, tariff shocks, and regulatory tightening.
-
Supplier strategic heatmap: Comparative assessment of >15 global suppliers across capability metrics — sustainability credentials, biotech readiness, geographic footprint, and customer concentration — plus a roadmap for supplier consolidation or diversification.
-
Commercial playbooks: Tailored go‑to‑market and procurement playbooks for CPGs, ingredient manufacturers, and contract manufacturers, including negotiation templates for rPCF claims and seasonal pricing clauses.
-
Regulatory risk matrix: Practical guidance for IFRA/REACH compliance, reformulation triggers, and timelines for supplier qualification to minimize reformulation cost and time to market.
-
M&A and partnership screening: A screened list of strategic acquisition targets and biotech partnerships, with financial and integration checklists designed to shorten diligence cycles.
-
Implementation tools: KPI dashboards for sustainability reporting, supplier scorecards, and an inventory‑to‑sourcing migration plan with estimated capex and payback horizons.
Practical 2026 playbook — recommended actions by stakeholder
-
For CPG and brand teams: Prioritize dual‑track reformulation (short‑term substitutions and long‑term platform changes). Require lifecycle metrics (including rPCF) from suppliers in RFPs and build 18‑month windows into launch timelines for high‑risk materials.
-
For ingredient suppliers: Accelerate certification of biotech routes and rPCF disclosures; pilot customer co‑innovation programs to lock in offtake; and consider near‑shoring critical volumes to mitigate tariff exposure and logistics risk.
-
For investors and PE sponsors: Target assets with validated botanical sourcing, proprietary purification technology, or biotech IP; valuation premia will accrue to suppliers that can demonstrate traceable supply and predictable scale‑up.
-
For procurement and risk teams: Rebalance supply portfolios to include strategic regional sources, implement hedging for key essential oil feedstocks, and embed tariff scenario planning in supplier scorecards.
Risks to monitor in 2026
-
Raw material shocks: Weather, crop disease, or rapid demand shifts in essential oils can produce price spikes that compress margins unless pass‑through mechanisms are in place.
-
Regulatory tightening: Faster than expected IFRA/REACH changes could force fast and costly reformulations across portfolios.
-
Biotech commercialization pace: While precision fermentation offers upside, commercialization bottlenecks (scale‑up failures, CAPEX overruns, or IP disputes) would delay expected cost advantages.
-
Trade policy shifts: Tariff and non‑tariff measures remain a tail risk for cross‑border supply chains; diversified sourcing and regional hubs reduce exposure.
Why PW Consulting’s report is strategically different
Many studies offer high‑level forecasts; our deliverable is designed for execution. We combine granular supplier benchmarking, regulatory timelines, and scenario models that link to procurement contracts and product launch calendars. The report is intentionally prescriptive — not just descriptive — offering checklists, contract language, and quantified scenarios to cut months off decision cycles and provide defensible inputs for board‑level strategy reviews.
Next steps — how to use this preview in your 2026 planning
-
Incorporate the 6.8% CAGR and near‑term supply risk assumptions into your 2026 budget and three‑year capex plans.
-
Commission a condensed supplier audit aligned to our heatmap methodology to rapidly identify single‑point vulnerabilities and near‑term strategic partners.
-
Mandate rPCF and traceability disclosures for all new supplier approvals to embed sustainability into procurement decision rules.
This preview outlines the strategic contours you will need for 2026. For the full market model, supplier heatmap, regulatory matrix, and the complete set of actionable playbooks — including scenario sensitivities and downloadable implementation tools — access the PW Consulting Worldwide Natural Aroma Chemicals Market report. The full intelligence package is designed to convert insights into executable plans and to de‑risk decisions in an increasingly volatile, sustainability‑driven market.
Contact PW Consulting to request the full report and accompanying executive workshop to align your 2026 roadmap with market realities.
For detailed analysis of this topic, please visit the official page: Worldwide Natural Aroma Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com