

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide PDMAT Market to Reach USD 638.7 Million by 2032, Growing at 7.5% CAGR (2026–2032); Asia Pacific Leads with USD 225M in 2025

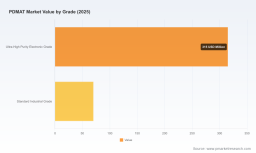
Worldwide PDMAT Market — Strategic Briefing (PW Consulting)
Executive summary
PW Consulting's latest Worldwide PDMAT Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032) delivers an actionable intelligence package for executives, procurement leads, R&D heads and investors preparing decisions in 2026 and beyond. Our bottom‑up model values the global market for pentakis(dimethylamino)tantalum (PDMAT) at USD 385.0 Million in 2025 and projects a steady trajectory to reach approximately USD 638.7 Million by 2032, implying a compound annual growth rate (CAGR) of 7.5% across the forecast window.
Worldwide DNS Protection Tool Market
This briefing highlights the strategic implications of those macro trends, synthesizes the technology and supply‑chain dynamics that matter to semiconductor supply‑chain decision makers, and summarizes competitive positioning among the leading suppliers—while deliberately withholding detailed subsegment allocations. This “trailer” approach demonstrates analytical depth and preserves the sensitive subsegment granularity for subscribers who visit the source portal for the full dataset and actionable tables.
Worldwide Express and Parcel (CEP) Market
Why this matters for 2026 decision cycles
- Capital planning and inventory strategy: The projected mid‑single‑digit to high‑single‑digit growth in aggregate PDMAT demand supports cautious capacity expansion for upstream precursor manufacturers and rational inventory stocking points for chipmakers. Buyers should calibrate safety stock and contractual volume options to avoid both supply shortages and costly overhangs as node transitions continue.
- Materials roadmap alignment: PDMAT remains a critical precursor for TaN barrier layers where copper interconnect scaling and reliability are required. Technology roadmaps for sub‑22nm and advanced interconnect integration mean that material purity, packaging, and delivery reliability will directly influence fab yield and qualification timelines.
- M&A and partnership signal: With market concentration skewed—our analysis shows the top three firms control roughly 65.5% of the market and the top five about 82.2%—strategic buyers and private equity should expect continued consolidation and selective vertical partnerships to secure supply in regions with increasing semiconductor build‑outs.
Market dynamics and growth drivers
The PDMAT market is principally driven by semiconductor wafer fab capacity growth, advanced node migration requiring robust Cu diffusion barriers, and increasing adoption of atomic layer deposition (ALD) and chemical vapor deposition (CVD) techniques. While absolute volumes remain small relative to other chemical markets, unit prices and purity requirements create outsized economic and technical impact across device BOMs.
Worldwide Amps & Effects Market
Key demand levers:
- Continued investment in advanced logic and memory fabs—accelerating demand for high‑purity TaN precursors.
- Technology retention benefits from ALD/CVD process control, which favors precursors that are well‑qualified across multiple toolsets.
- Regional fab build programs that create localized procurement dynamics and qualification cycles (details on region splits are reserved for the full report).
Technology, synthesis and high‑purity manufacturing
PDMAT synthesis and purification are core differentiators. The compound is commonly synthesized via a metathesis route (TaCl5 + LiNMe2) followed by multi‑stage purification to meet high‑volume manufacturing (HVM) specs. To be fit for advanced Cu barrier applications, manufacturers target ultra‑high purity levels—achieving specifications often reported in the literature (for example, chloride content in sub‑10 ppm ranges and oxygen at trace levels) through proprietary distillation, recrystallization and handling processes.
Two technical realities flow from this:
- Process compatibility: ALD/CVD tool vendors and fabs will prioritize precursors with demonstrated thermal stability, controlled vapor pressure behavior, and low impurity profiles that do not compromise dielectric integrity or leakage performance.
- Manufacturing scale‑up complexities: Scale‑up from research grades to HVM requires not only chemical synthesis expertise but also investments in inert‑atmosphere handling, containerization and qualification protocols—areas where incumbent suppliers have invested heavily.
Regulatory and handling constraints
PDMAT is highly air‑ and moisture‑sensitive and is generally classified for research and industrial use rather than consumer applications. As a result, logistics and packaging are not minor details; they are determinative. Industry practice includes supply in glass ampules, metal ampoules/bubblers, and other specialized containers to preserve purity and support safe integration into ALD/CVD tool chains.
For procurement and operations teams this translates into vendor selection criteria that include demonstrated cold‑chain/inert‑packaging capability, certified handling SOPs, and transparent material safety documentation to prevent contamination and ensure quick qualification cycles on production tools.
Competitive landscape — profiles and strategic positioning
PDMAT supply is dominated by a group of specialized chemical firms and advanced materials manufacturers. Our report evaluates capabilities across product purity, scale, geographic footprint, packaging and customer support. Selected industry participants reviewed include:
- Merck KGaA (EMD Group) — Global reach and a broad semiconductor materials portfolio; strength in supplying high‑purity PDMAT as a solid precursor for ALD/CVD with established distribution in major fab regions.
- Ereztech — U.S.‑based supplier notable for flexibility in small and bulk volumes and customization of packaging formats including glass ampules and metal bubblers, valuable for shorter qualification cycles and prototype throughputs.
- Strem Chemicals (Ascensus Specialties) — Research‑grade supplier with consistent quality for early‑stage development and academic collaborators.
- Northern and Taiwan‑based manufacturers (e.g., Nanmat Technology, TOPCO Scientific, PentaPro Materials) — Regional manufacturing proximity to major fabs, with product lines extending across ALD/CVD precursors that can shorten supply chains.
- China‑based suppliers (e.g., Argosun, Sinocompound) — Emerging contenders with focus on high‑purity offerings and competitive cost structures; attention needed on qualification support and logistics for HVM customers.
- Specialty European makers (e.g., DOCK Chemicals) — Ultra‑high purity producers addressing niche high‑reliability needs in advanced fabs.
Our competitive assessment emphasizes: product purity and consistency; supply security and scale; customer technical support; and packaging/handling competency. Buyers should layer these criteria into scorecards during 2026 sourcing rounds.
Supply‑chain risk map and mitigation
- Single‑sourcing risk: Given market concentration, reliance on single vendors for mission‑critical grades increases vulnerability. Mitigation includes multiple qualified sources, staggered delivery contracts and technology transfer agreements where appropriate.
- Logistics sensitivity: Air‑ and moisture‑sensitivity requires specialized transport and bonded inventory near fab sites. Investing in regional buffer stocks and local packaging partners reduces lead‑time risk.
- Raw material inputs: Feedstock availability and price volatility (for tantalum and organometallic precursors) necessitate forward purchasing and supplier hedging strategies for large fabs.
What the full report delivers (practical content)
The full PW Consulting report is structured for immediate operational use by purchasing, process integration, and strategy teams. Highlights include:
- Quantitative market model (historical 2020–2025; forecast 2026–2032) with scenario sensitivity analysis to reconcile capacity additions, fab ramp schedules and adoption rates of ALD vs CVD toolsets.
- Supplier scorecards with comparative assessments across purity, regulatory compliance, packaging options, geographic presence and qualification lead times.
- Supply‑chain playbooks—procurement levers, inventory optimization templates, and contracting language to secure both price and continuity for high‑value precursors.
- Risk heatmaps and contingency plans for logistics, raw material shocks and regulatory constraints affecting handling and transport of moisture‑sensitive organometallics.
- Executive decision frameworks and recommended KPIs for 12–36 month roadmaps, tailored to fab size and technology node profiles.
Note: To preserve commercial sensitivity and discourage misuse of granular subsegment tables, we intentionally withhold detailed regional and application breakdowns in public summaries. The full dataset, including downloadable spreadsheets and supplier qualification templates, is available to report subscribers.
FAQ — practicalities procurement teams ask
- How is PDMAT typically supplied? — Suppliers utilize specialized packaging such as glass ampules, metal ampoules/bubblers and sealed bottles under inert atmosphere to maintain purity and ease integration into ALD/CVD delivery systems.
- What purity targets are required for HVM? — Ultra‑high purity profiles with extremely low chloride and oxygen contamination are expected; many HVM customers demand multi‑stage purification benchmarks and trace impurity analytics as part of qualification.
- Are there regulatory limits on use? — Beyond chemical safety classifications, PDMAT handling requirements (inert atmosphere, specialized packaging, transport controls) are the principal compliance considerations for industrial use. It is generally not intended for medicinal or consumer uses.
How to use this intelligence in 2026 planning
For 2026, executives should prioritize three immediate actions:
- Fast‑track multi‑vendor qualification for at least one alternate supplier per critical precursors group and codify packaging and handling acceptance criteria.
- Align capital procurement timing with the forecasted market trajectory—use our mid‑case model as a base and test two downside/upside scenarios for procurement commitments.
- Integrate supplier scorecards into supplier development programs to close gaps in analytics, packaging capability and regional logistics ahead of planned ramp windows.
Methodology note
PW Consulting’s market sizing synthesizes supplier shipment data, vendor financial disclosures, production capacity mapping and primary interviews with fab process engineers and procurement leads. Base year is 2025; historical series covers 2020–2025; our forecast extends 2026–2032 and assumes a blended CAGR of 7.5% across the forecast period. Market concentration metrics shown in this briefing reflect our assessment of share distribution among leading suppliers and are included to help stakeholders gauge competitive intensity and sourcing risk.
Conclusion — strategic takeaway
PDMAT remains a strategic materials segment: small in physical volume but highly consequential for semiconductor yield, reliability and scaling. The projected growth to the end of the decade reinforces the need for disciplined supplier strategies, proactive qualification of alternate sources and investment in packaging and logistics. PW Consulting’s full Worldwide PDMAT Market report equips leaders with the quantitative scenarios, supplier scorecards and procurement playbooks needed to convert market forecasts into robust 2026 tactical plans.
For access to the full dataset, supplier matrices and downloadable procurement templates, please visit our report page or contact our industry practice team for an executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide PDMAT Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com