

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Venetoclax API Market Poised for Rapid Expansion at 12.51% CAGR Through 2032

Worldwide Venetoclax API Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
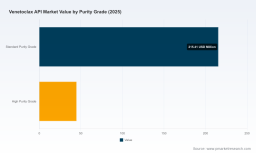
As oncology generics and contract manufacturing networks reposition for the next commercialization window, PW Consulting’s latest Worldwide Venetoclax API Market report establishes a fact-based runway for strategic investment, sourcing and portfolio decisions in 2026. The aggregated market for Venetoclax active pharmaceutical ingredient (API) has expanded rapidly over the past half-decade, rising from a modest baseline in 2020 to an estimated USD 260.17 Million in our base year (2025). Under our central-case assumptions the market grows at a compounded annual growth rate (CAGR) of 12.51% across the 2026–2032 forecast interval, reaching roughly USD 593.85 Million by 2032.
Worldwide Taxi & Limousine Software Market
This briefing highlights the operational and competitive inflection points we believe will matter most to manufacturers, CDMOs, investors and downstream formulators in 2026 — while preserving detailed, proprietary subsegment tables and contractual intelligence for the full report available on our site.
Parallel Constant Watt Heating Cable Market
Why 2026 is a strategic hinge year
-
Momentum into generic entry windows: Patent and exclusivity timelines for the reference drug create a predictable cadence for generic entrants, licensing activity and litigation risk. Key composition-of-matter and exclusivity expirations surface across the next several years and will shape supply-side timing for large-volume API contracts.
Worldwide Scuba Diving Clothing Market -
Accelerating market scale: From our historical series (2020–2025) and modeled scenarios, 2026 represents the first year in our forecast where absolute annual market growth meaningfully accelerates versus the historical average, reflecting both increased demand from anticipated generic launches and wider clinical use in hematologic indications.
-
Commercial readiness pressure on supply chains: Ramp plans for API producers, quality regulatory filings (DMFs/EDQMs/CEPs) and finished-dosage manufacturers must be aligned in 2026 to capture the fastest-growing share of the 2026–2032 opportunity.
Market trajectory — what the numbers mean for resource allocation
The transition from USD 260.17 Million in 2025 to an expected USD 290.78 Million in 2026 (our first forecasted year) reflects a market that is both expanding and undergoing structural change. At a 12.51% CAGR through 2032, total market value nearly doubles by the end of the forecast period — a growth path that rewards early capacity investment, robust quality systems, and commercial partnerships that ensure offtake.
For CFOs and corporate strategists, these aggregate values justify staged capital deployment: secure short-term capacity with modular footprints in 2026–2027, and plan for scale-out options (additional reactors, isolation suites, secondary purification lines) as demand crystallizes toward the latter half of the decade. For procurement and CMO sourcing leads, the implication is clear — begin multi-source qualification in 2026 to mitigate supplier concentration and logistics risk while locking favourable terms with capable suppliers.
Key market dynamics shaping near-term strategy
- Intellectual property and timing: The industry’s commercial calculus is governed by patent and exclusivity milestones. The central composition-of-matter patent remains a determinative factor for originator and generic strategies; pediatric and secondary exclusivities further extend windows in certain jurisdictions. These timelines should be embedded in go/no-go investment models and licensing term sheets.
- Raw material complexity and cost pressure: Venetoclax synthesis relies on advanced heterocyclic chemistry that uses specialized intermediates (indole- and pyrazole-based building blocks). These inputs inflate small-batch material costs substantially and penalize low-yield routes. Process chemistry optimization and backward integration or secured supplier relationships for these intermediates are proven levers to compress unit economics.
- Reimbursement and downstream economics: Branded and biosimilar pricing environments inform the ceiling for generic pricing and commercial margins. Reimbursement settings in core markets materially affect the demand profile for competitive offerings, and manufacturers should model multiple reimbursement scenarios when sizing their market-entry economics.
- Supply concentration and regulatory scrutiny: A majority of global Venetoclax API capacity is concentrated among manufacturers in Asia. This concentration delivers cost advantages but also raises sourcing risk in the event of regulatory actions or trade disruptions. Dual-sourcing strategies and proactive quality investments (e.g., timely DMF/CEP/EDQM filings and transparent inspection readiness) are essential mitigation tactics.
Competitive landscape — what separates winners from followers
Our market-concentration metrics indicate a focused supplier landscape: the top three firms control a sizeable majority of market share, and the top five command over four-fifths of the market by value. This level of concentration creates both barriers and opportunities. Established API manufacturers with regulatory dossiers and inspection-ready facilities are natural partners for finished-dosage producers seeking rapid entry; conversely, well-capitalized newcomers can capture share by offering differentiated guarantees — for example, capacity reservation, price hedging on critical intermediates, or enhanced quality/traceability provisions.
Representative profiles in the competitive set illustrate the different strategic postures we observe:
- MSN Laboratories (Hyderabad, India) : High-purity Venetoclax API production with multiple DMFs filed with major regulatory bodies. Their model emphasizes global generic supply, and their regulatory positioning makes them a prime counterparty for large-volume offtake agreements.
- Hetero Drugs (Hyderabad, India) : A commercial-scale API producer holding CEP certification, focusing on continuity of supply to finished-dosage manufacturers. Their certification profile reduces lead time for EU-bound partners.
- Aurobindo Pharma (Hyderabad, India) : Operates US FDA-approved facilities with a focus on oncology APIs for export markets. Their compliance track record is an asset in price-sensitive, regulation-intensive geographies.
- Senova Technology (Tianjin, China) : A specialist producer maintaining regional DMF filings and GMP compliance aimed at international supply chains. Their technical know-how supports customers seeking bespoke process development and supply continuity.
Notable transactional signals: a high-profile patent settlement in late 2022 clarified some pathways for generic entrants and has been an accelerant for API producers to scale capacity and file regulatory dossiers. Market participants should treat such settlements as leading indicators for supplier behaviour and contract timing.
What the PW Consulting report delivers — actionable intelligence
Our full report translates market dynamics into executable guidance across the commercial stack. Key practical components include:
- Scenario-modeled demand curves and capacity utilization templates that allow procurement, manufacturing and investment teams to simulate 12-, 24- and 36-month ramp trajectories.
- Supply-chain due diligence checklists tailored to high-complexity oncology APIs — encompassing regulatory dossier maturity, process route validation, impurity control strategies, and audit readiness.
- Contract structures and sample commercial clauses for capacity reservation, price escalation, quality deficiencies and force majeure specific to high-value oncology APIs.
- Regulatory intelligence — a readiness scorecard for DMF/EDQM/CEP filings and recommended timelines to support rapid market entry or defend against inbound generics.
- Risk-adjusted valuation models for M&A and minority investments in API producers and CDMOs, with sensitivity analyses for raw material price shifts and accelerated generic uptake.
For confidentiality and commercial reasons this briefing omits the granular regional and application-level breakdowns — those segment tables and supplier-level volumes are available in the full report and client dashboards.
Strategic imperatives for 2026
- Manufacturers and CDMOs: Finalize quality dossier readiness and pursue at least one regulatory filing in 2026 if you intend to serve major export markets by the 2027–2029 window. Invest selectively in route optimization to reduce reliance on expensive intermediates.
- Finished-dosage producers: Begin multi-vendor qualification in 2026 and negotiate staged offtake agreements tied to inspection milestones to avoid supply shocks while keeping unit costs competitive.
- Investors and M&A teams: Prioritize targets with validated DMFs/CEPs, demonstrated batch reproducibility and transparent quality systems; apply our scenario models to stress-test valuations under faster-than-expected generic penetration.
- Procurement and risk managers: Build inventory buffers for critical intermediates, and structure contracts with capacity options. Contingency playbooks for regulatory hold scenarios should be operational by mid-2026.
Conclusion — how PW Consulting helps you act in 2026
The Venetoclax API market presents a pronounced growth opportunity driven by therapeutic demand, patent dynamics and the readiness of a concentrated set of suppliers. Our analysis shows the market’s aggregate size and growth rate create strong incentives for well-coordinated action in 2026: firms that align regulatory, operational and commercial plans early will capture favorable positions across the 2026–2032 expansion.
PW Consulting’s full report contains the segment-level tables, regional breakdowns, supplier scorecards and transactional templates you need to convert strategy into execution. To access the complete dataset and interactive scenario tools — including supplier-level capacity schedules and contract playbooks — please visit our report page. Note: we intentionally withhold detailed subsegment figures in this public briefing to preserve the proprietary intelligence contained in the paid report.
For detailed analysis of this topic, please visit the official page: Worldwide Venetoclax API Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com