

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Sound Cards Market Set to Expand at a 5.88% CAGR Through 2032

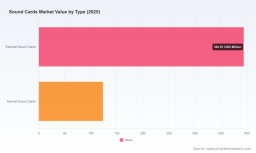
Worldwide Sound Cards Market — Strategic Outlook for 2026
Executive snapshot
PW Consulting’s latest Worldwide Sound Cards Market report positions the market as a resilient, innovation-driven segment within the broader audio-electronics ecosystem. Measured in our 2025 base year, the global sound cards market reached approximately USD 517.25 Million (Million USD). Our forecast indicates continued expansion through the 2026–2032 horizon, with a compound annual growth rate (CAGR) of 5.88%, bringing the market to an estimated USD 771.6 Million by 2032. Market concentration remains moderate: the top three vendors account for roughly 41% of revenue, and the top five for about 57% — an industry structure that supports both incumbent scale plays and targeted disruption by well-capitalized specialists.
Worldwide Security Risk Analysis Software Market
Why this report matters to 2026 decision-makers
-
Investment prioritization: We translate macro growth and driver alignment into a short-list of near-term investment opportunities that maximize return within the 2026 planning cycle.
Mobile Fetal Monitor Market -
Risk-aware sourcing: The report maps supply-chain fragilities and regulatory stress points directly to procurement levers, enabling purchasing and operations leaders to cost-effectively de-risk component flows.
Worldwide Lithium-Ion Battery ICs Market -
Product & channel strategy: For OEMs, consumer brands, and pro-audio companies, we provide a prioritized set of product features, channel experiments, and pricing tactics that have been stress-tested against alternative market scenarios.
-
M&A and partnership screening: We convert concentration metrics, technology roadmaps, and margin structures into an actionable M&A and teaming scorecard for active acquirers and strategic partners.
Market dynamics shaping 2026 strategy
Three macro-to-micro dynamics will dominate boardroom conversations in 2026 and beyond:
-
Supply-chain and regulatory friction. Continued U.S. export controls on advanced semiconductors, combined with tariff uncertainty, have introduced sourcing complexity across audio ICs and related components. Q4 2025 saw tightened lead times for certain passives and discrete devices, putting pressure on time-to-market for new SKUs and on component cost baselines.
-
Component and converter innovation. Improvements in ADC/DAC architectures — driven by specialized semiconductor houses — are raising the performance floor for entry-level and professional solutions alike. This is accelerating feature commoditization (e.g., higher dynamic range, lower latency) while opening premiumization opportunities where software and ecosystem lock-in add value.
-
Segmentation pull: gaming, professional studio/broadcast, and home entertainment continue to pull product roadmaps in different directions. Gaming and consumer segments prize low-latency, USB/PCIe convenience, DSP-enhanced experiences and software ecosystems; professional users demand multi-channel I/O, ultra-low-latency drivers, and studio-grade converters. These divergent needs create both cross-sell and cannibalization risks that require disciplined product-line architecture.
Competitive landscape — strategic implications
The market comprises several distinct player archetypes. Understanding which archetype you compete with or partner through will determine margin targets, route-to-market, and technology partnerships.
-
Consumer and gaming incumbents: Creative Technology and ASUS continue to exploit brand equity and platform integration to defend high-volume gaming and enthusiast segments. Creative’s January 2025 launch of a new Sound Blaster USB DAC/amp — with refreshed drivers and firmware optimizations — underscores incumbents’ playbook: iterative hardware updates combined with sustained software investment to extend lifecycle value.
-
Silicon and OEM suppliers: Realtek and C-Media operate at the foundational layer, providing codecs and controllers that underpin many onboard and aftermarket products. For buyers, close collaboration with these suppliers can materially reduce BOM risk and shorten NPI cycles; for challengers, optimizing around these chipsets is a path to cost leadership.
-
Professional audio specialists: Focusrite, Universal Audio, RME, MOTU, PreSonus, and others form a category characterized by high engineering differentiation, premium pricing, and close relationships with studios and creators. Their advantage is not only in hardware but in proprietary DSP, driver stability, and ecosystem tools that justify premium margins.
-
Value and niche players: Companies such as Sabrent, Behringer, HT Omega, and select boutique brands serve price-sensitive or very specialized pockets. These players can be opportunistic partners for distribution expansion or acquisition targets for incumbent brands seeking adjacent volume.
-
Implication for 2026 strategy: Scale matters for distribution and marketing, but differentiation still anchors premium segments. Winning strategies combine reliable supply-chain partnerships with selective feature investment (e.g., DSP toolkits, low-latency drivers, and seamless platform integrations) and a clear go-to-market for either mass or professional channels.
What the report contains — practical deliverables (high-level)
The report is crafted for immediate operational use by product, procurement, corporate development, and strategy teams. Key actionable elements include:
-
Consolidated market-sizing and validated growth scenarios (2020–2032) with transparent methodology and sensitivity testing.
-
Vendor heatmaps and capability matrices that map product features, software stacks, and channel strength — enabling rapid competitor benchmarking.
-
Supply-chain stress tests and cost-risk models that translate component lead-time variance and tariff scenarios into margin impact simulations.
-
Go-to-market playbooks for three archetypal business models: Consumer/Gaming OEM, Pro-Audio Specialist, and Component Supplier/ODM. Each playbook contains prioritized initiatives, expected ROI, and 90/180/540-day milestones.
-
M&A and partnership scorecards: an evidence-based shortlist of targets and partnering patterns, accompanied by valuation sensitivities tied to concentration metrics and forecast demand curves.
-
Regulatory and geopolitical risk dashboard that maps where export controls and domestic chip policies most materially affect sourcing and manufacturing options.
Note: To preserve strategic integrity and to support consultative follow-up, this press summary intentionally omits granular sub-segment revenue tables and regional/application-level breakouts. The full dataset and vendor-level tables are available through the PW Consulting report portal.
Using the intelligence across horizons — tactical guidance
Our report’s recommendations are organized by planning horizon to ensure they can be operationalized immediately.
-
0–90 days: Prioritize supplier audits for components with the tightest Q4 2025 lead-time exposures; lock flexible contracts or dual-source critical passives and converter ICs. Initiate driver-stability audits for any product slated for a 2026 refresh.
-
3–6 months: Decide on product architecture rationalization — consolidate SKU complexity where margins are thin, and accelerate development of modular hardware platforms that allow software-enabled differentiation (DSP suites, firmware features). Begin formal discussions with shortlisted silicon partners to secure allocation ahead of ramp cycles influenced by geopolitical restrictions.
-
6–18 months: Execute channel experiments (bundled software subscriptions, creator partnerships, pro-studio pilots) and refine pricing strategies using modeled elasticity insights in the report. For acquirers, run accelerated due diligence on targets identified in the M&A scorecard and structure contingent earn-outs linked to integration milestones.
Practical next steps for executives
-
Procurement leaders: Use our supply-chain risk matrix to re-score your BOM and prioritize dual-sourcing where chip or passive lead times pose >X-week delay risk.
-
Product and R&D leaders: Adopt a modular hardware + SaaS overlay approach to protect ASPs from commoditizing DAC improvements.
-
Commercial leaders: Re-allocate marketing spend toward creator-led programs and competitive demos that show measurable latency and fidelity gains — these convert faster in both consumer and studio channels.
-
Corporate development teams: Leverage our concentration metrics and vendor heatmaps to identify consolidation plays or capability tuck-ins that accelerate time-to-market for pro-level features.
Conclusion — strategic value in 2026
For stakeholders planning 2026 budgets and strategic moves, the sound cards market presents a hybrid opportunity: steady headline growth at a mid-single-digit CAGR, with pockets of high-margin premiumization driven by software and converter innovations. However, supply-chain and regulatory headwinds require a disciplined approach to sourcing and product planning. PW Consulting’s report converts these realities into executable initiatives — from procurement contingencies and NPI blueprints to M&A scorecards and channel experiments — while preserving the detailed subsegment datasets for clients who need the full evidentiary basis for decisive action.
To obtain the full report, including the vendor-level tables, scenario datasets, and downloadable Excel workbooks, visit our report page or contact PW Consulting’s industry practice. The detailed tables are intentionally gated to ensure you receive tailored interpretation and hands-on support for the 2026 decision cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Sound Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com