

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Fire and Gas Detection Systems Market to Rise from USD 7,500 Million in 2025 to USD 11,654.9 Million by 2032 at a 6.5% CAGR

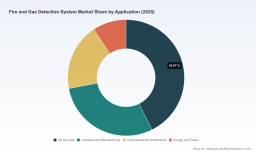
Worldwide Fire and Gas Detection System Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market research, "Worldwide Fire and Gas Detection System Market — 2026 Outlook and 2026–2032 Forecast," provides executive teams with a rigorous, forward-looking evidence base to shape capital allocation, product strategy, M&A screening, and regulatory compliance planning in 2026. Built on a 2025 base year and a detailed historical run (2020–2025), the report projects the market through 2032 and quantifies a sustained growth trajectory at a compound annual growth rate (CAGR) of 6.5% across the forecast horizon. Our bottom-up model places the market at approximately USD 7.5 billion in 2025, expanding toward an estimated USD 11.65 billion by 2032.
Worldwide Database Assessment Service Market
Why this report matters for 2026 strategic decisions
-
Timing: 2026 is a pivotal year for firms that need to translate near-term regulatory shifts, supply-chain realignments, and sensor-technology inflections into competitive advantage. The PW Consulting forecast crystallises those inflection points into revenue and risk scenarios that are actionable within board planning cycles.
Sleeper Chair For Hospital Market -
Risk-aware growth planning: With the market forecast growing at 6.5% CAGR, management teams must balance growth capture against margin pressure from component cost volatility (semiconductor and precision optics inputs) and increasing compliance costs in high-risk sectors. Our scenario modules enable trade-off analysis between premium integrated solutions and cost-competitive modular offerings.
Worldwide Mechanical Booster Pumps Market -
Capital allocation and M&A prioritisation: The market’s moderate concentration (CR3 ~42.5%; CR5 ~58.75%) suggests a landscape where leading incumbents hold substantial influence but meaningful consolidation opportunities remain. That concentration profile supports an active M&A playbook targeting technology tuck-ins, regional scale, and solutions that accelerate digitisation of installed bases.
What’s inside PW Consulting’s report (practical deliverables)
-
Proprietary market model and forecast (2026–2032) — delivered in an interactive format that lets users stress-test revenue trajectories under alternative macro and regulatory scenarios.
-
Executive decision-support dashboards — including CAPEX implication matrices, IRR simulations for technology investments, and playbooks for pricing and bundling strategies tied to installed base monetisation.
-
Competitive heat maps and capability gap analyses — positioning the major global suppliers by technology stack, service footprint, and solution integration depth to help prioritise partnerships, OEM relationships, and M&A targets.
-
Channel and go-to-market playbooks — tactical guidance for OEMs, system integrators, and industrial end-users on accelerating adoption of wireless, IoT-enabled, and AI-driven predictive maintenance offerings.
-
Regulatory impact assessments — scenario-based analysis of how evolving standards (including recent NFPA updates) materially alter certification timelines, product roadmaps, and liability exposure.
-
Supply-chain sensitivity analysis — identifying critical raw material and component bottlenecks (e.g., semiconductor-grade sensors, precision optics) with mitigation strategies and alternative sourcing frameworks.
Key themes shaping the market in 2026
-
Standards convergence and certification complexity: The adoption of broader integration expectations in fire alarm standards — for example, updated guidance that brings gas detection, open path, ultrasonic gas, and smoke detection closer together — is changing product architectures and certification timelines. Companies that proactively align R&D roadmaps with standards evolution will shorten time-to-market and capture premium positions in regulated sectors.
-
Sensor and electronics supply dynamics: Fire and gas systems are increasingly reliant on advanced sensor technologies (electrochemical cells, infrared and IR3 optics, semiconductor-based sensing elements), and the upstream supply chain remains susceptible to capacity constraints and pricing swings. Strategic suppliers will need to secure multi-year supply agreements or invest in vertical integration to stabilise margins.
-
Digitalisation and predictive maintenance: Miniaturisation, IoT connectivity, wireless mesh deployments, and AI-driven analytics are transitioning many deployments from reactive alarm systems to predictive safety ecosystems. This shift unlocks new recurring revenue streams (SaaS, managed detection) and changes how capital is deployed across product, services, and software.
-
Segmentation-driven go-to-market: Demand drivers differ materially by end market (e.g., oil & gas vs. commercial buildings). The most successful vendors will tailor solution bundles and service SLAs to the risk profiles and procurement practices of each vertical while maintaining a modular product architecture to limit product proliferation costs.
Competitive landscape — who matters and why
The market is controlled by a mix of diversified industrial conglomerates, focused safety specialists, and nimble technology challengers. PW Consulting’s analysis profiles each major participant along three dimensions: technology breadth, systems integration capability, and go-to-market reach.
-
Honeywell International Inc. — A global, diversified player with broad fixed and portable portfolios and deep channel penetration across oil & gas, chemical, and industrial end-users. Its strength lies in integrated safety ecosystems and the ability to bundle detection with automation and building management services.
-
MSA Safety Incorporated — Focused on industrial safety, MSA’s product set spans fixed and portable detection and open-path technologies. Its compliance-centric approach and active role in standards discourse (including NFPA-focused activities) keep it well-positioned among safety-conscious buyers.
-
Drägerwerk AG & Co. KGaA — Known for high-reliability optical and multi-gas detection technologies, with a strong footprint in maritime and petrochemical installations. Dräger’s engineering heritage supports premium-priced, specification-driven contracts.
-
Emerson Electric Co. — Integrates detection solutions within broader process automation and safety instrumented systems, targeting end-users that prioritise unified control and safety architectures.
-
Siemens AG — Combines fire detection components with industrial and building management systems; suited to large-scale, multi-site deployments requiring centralised monitoring and lifecycle services.
-
Autronica Fire and Security AS, ABB Ltd., Johnson Controls International — Each offers differentiated capabilities in maritime, industrial automation, and building safety respectively. These players compete on service depth, regional presence, and integration with adjacent safety systems.
-
Specialists and challengers (Teledyne, FGD, ESP Safety, Industrial Scientific, etc.) — These firms provide focused technical advantages (e.g., advanced UV/IR flame detection, portable connected gas monitors) and represent high-value acquisition targets for larger integrators seeking rapid capability upgrades.
Recent market signals — what to watch in 2026
-
Standardisation and industry forums: High-visibility engagements, such as MSA Safety’s presentations at the NFPA Conference & Expo, signal that standards evolution is not only regulatory but also a commercial battleground. Firms that shape and anticipate standard updates can influence procurement criteria and interoperability requirements.
-
Product innovation at trade shows: Recent launches of long-range, optically enhanced flame detectors and targeted HVACR-focused gas detection offerings underscore the pace of sensor innovation and the widening universe of addressable use-cases.
-
Channel activations and trade-show activity: Active participation by midsize specialists at major expos highlights the importance of relationship selling and the continuing relevance of demonstration-led procurement, especially for safety-critical applications.
How to use the report — recommended executive actions for 2026
-
Board-level scenario planning: Use the report’s forecast scenarios to stress-test capital spending paths under different regulatory and supply conditions, and align R&D budgets to the most likely adoption curves for IoT-enabled and AI-enhanced offerings.
-
M&A target screening: Deploy our competitive heat maps to identify acquisition targets that provide complementary sensor technologies, regional footholds, or service capability that accelerate recurring revenue models.
-
Portfolio rebalancing: Apply our margin-pressure and supply-risk modules to decide where to invest in vertical integration (e.g., sensor manufacturing), where to pursue partnerships, and where to de-emphasise legacy product lines.
-
Commercial optimisation: Adopt the go-to-market playbooks to design outcome-based contracts (e.g., uptime guarantees, performance-based maintenance) that capture more of the installed-base value chain.
Access to full intelligence
PW Consulting has deliberately structured this briefing to present the strategic contours and decision-useful implications of the market while preserving the granular subsegment tables, regional breakdowns, and vendor share matrices that are part of the full report. Executives, investors, and technology leaders who require detailed breakdowns (including model-level forecasts by product type, application, and region; vendor-level revenue estimations; and downloadable datasets) should obtain the full research package.
For organisations preparing budgets, negotiating supplier agreements, or evaluating acquisition targets in 2026, the full report is designed to be directly operational — supplying the datasets, scenario workbooks, and playbooks needed to convert insight into action. Contact PW Consulting or visit our report landing page to request the full dataset, custom briefing, or a tailored workshop for your leadership team.
About PW Consulting
PW Consulting specialises in strategic analysis and operational guidance for industrial technology markets. Our cross-functional teams combine market modelling, primary research with industry stakeholders, and practical scenario planning to deliver intelligence that executives can act on immediately. Our Worldwide Fire and Gas Detection System Market study integrates proprietary supply-chain analysis, standards-impact assessment, and vendor capability audits to help clients make confident decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Fire and Gas Detection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com