

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Pt Paste for Gas Sensor Market to Expand at a 6.45% CAGR Through 2032

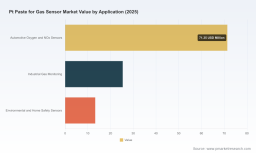
Worldwide Pt Paste for Gas Sensor Market — Strategic Imperatives for 2026
Executive overview
PW Consulting’s new market study for Platinum (Pt) Paste used in gas sensors frames an operationally focused roadmap for executive teams planning programs and capital allocation in 2026. The market has demonstrated sustained expansion through the 2020–2025 period, rising from the low‑seventies to approximately USD 110 Million in the 2025 base year, and is forecast to continue growing into the 2030s. Our modeling shows a compound annual growth rate (CAGR) of 6.45% over the 2026–2032 forecast window, with the market approaching a materially larger scale by the end of the period. Those macro dynamics—combined with acute upstream supply tightness in platinum and accelerating price volatility—create both opportunity and execution risk for sensor OEMs, materials suppliers, and investors.
Greenhouse Solar System Market
Why this matters for 2026 decision-making
- Procurement & cost management: Platinum feedstock dominates cost of goods for Pt paste formulations. The market experienced supply contraction and sharp price moves in recent market cycles, creating a need for active hedging, long‑term offtake arrangements, and recycled stream programs. Companies that treat feedstock strategy as a strategic asset—rather than a purchasing line item—will protect margins and continuity in 2026.
- Product qualification timelines: Automotive and industrial sensor OEMs operate long qualification cycles. With the market trajectory and tighter materials availability, front‑loading material evaluation and dual‑sourcing strategies in 2026 will materially reduce time‑to‑market risk for new sensor platforms.
- R&D and formulation choices: Variations in firing profile, conductor resistance, and adhesion chemistry translate directly into sensor performance, yield and cost. Investing in co‑development with established Pt paste manufacturers—covering low and high‑temperature sintering routes and Pt‑alloyed formulations—will accelerate differentiation in next‑generation sensors.
- Supply chain resilience & sustainability: Recycling of PGM content and closed‑loop sourcing will move from CSR checkbox to operational necessity. In 2026, firms that invest in PGM recycling, strategic stockpiles, and supplier partnerships will gain negotiating leverage and reduce exposure to spot price shocks.
- Regulatory compliance & market access: Pt paste formulations for gas sensors are constrained by RoHS2 and related restricted‑substance standards. Ensuring materials and manufacturing processes meet these requirements is non‑negotiable for global automotive and consumer applications.
Report scope — what PW Consulting delivers (practical modules)
- Proprietary market sizing & forecast model (2020–2032) with scenario runs reflecting spot, constrained, and normalized PGM supply settings. Includes sensitivity tables for feedstock price and demand elasticity.
- Cost‑to‑serve and bill‑of‑materials (BOM) impact tools that translate platinum price movement into P&L stress points for common sensor architectures.
- Supplier benchmarking and technical scorecards — independent assessment of manufacturing footprints, core formulations (screen‑printable, fritted, thick film), firing temperature regimes, and qualification status against automotive and industrial standards.
- Product & process playbooks covering paste selection, firing profiles, printed line widths, adhesion testing, and accelerated life‑cycle protocols for engineers and procurement teams.
- Supply chain risk matrix and negotiation playbook addressing hedging, recycling, consignment stock, and collaborative product development agreements.
- M&A & partnership roadmap identifying priority targets and strategic partnering constructs for vertical integration or regional capacity expansion.
Competitive landscape — strategic positioning of core suppliers
The Pt paste supply chain is characterized by a mix of specialized PGM material houses and diversified electronic materials firms. Leading suppliers combine metallurgical know‑how with formulation capability and customer qualification track records. Key strategic observations:
Worldwide Blackcurrant Seed Oil Market
- TANAKA Precious Metals (Japan) — Strengths lie in integrated powder‑to‑paste manufacturing and a tranche of formulations tailored for heaters, leads and porous electrode structures. Their product families include low‑resistance and high‑resistance heater pastes, porous electrode pastes and Pt‑alloys (Pt/Pd, Pt/Rh, Pt/Au). This breadth supports deep co‑development with automotive sensor OEMs that prioritize long‑life performance and high‑temperature firing.
- Heraeus Electronics (Germany) — A leader in thick film conductor pastes, Heraeus combines metallurgical variants (pure Pt, noble‑metal alloys) with a focus on solderability and chemical resistance for fuel and oxygen sensing. Recent technical documentation updates reflect an emphasis on robustness for fuel‑sensor environments—an important signal for OEMs seeking proven qualification packages.
- Dycotec Materials (UK) and Ferro (US) — These players offer screen‑printable and thick film options optimized for practical manufacturing constraints: lower firing ranges, fine‑line printing capability, and repeatable fired resistivity. Their value proposition is speed to qualification and manufacturing yield improvement.
- Johnson Matthey & Umicore — With deep PGM portfolios, catalytic expertise, and recycling capability, these firms are strategic partners for clients seeking both feedstock security and advanced material formulations—especially where catalytic or electrochemical performance is a differentiator.
- MANA Metal & American Elements — Regional and specialty suppliers offering competitive electrodes and pastes; attractive for localized sourcing strategies and cost optimization where regional content or supply locality is prioritized.
Collectively, the supplier population skews toward a mid‑to‑high concentration profile: a handful of established suppliers command a substantial share of qualified, automotive‑grade capacity, while smaller specialists and regional producers address niche and cost‑competitive segments. Recent vendor moves—such as updated technical data sheets and upstream market commentary—underscore an industry adapting both product portfolios and go‑to‑market messaging to material market stress.
Worldwide Angle Valves Market
Dynamics to monitor in 2026
- Platinum supply & pricing volatility: Primary PGM supply contracted recently, pressuring stock levels and contributing to sharp price appreciation. These dynamics will materially affect procurement tactics, inventory policy and R&D prioritization in 2026.
- Regulatory and quality requirements: RoHS2 compliance and automotive qualification cycles continue to be gating factors for new entrants. Manufacturers should avoid shortcuts in materials certification to prevent costly rework.
- Formulation innovation: Alloying strategies (e.g., Pt/Pd, Pt/Rh) and firing‑profile adaptations present pathways to performance/cost tradeoffs. Targeted co‑development with suppliers can reduce reliance on pure‑Pt loadings while preserving sensor performance.
- Recycling & circularity: Practical recycling of PGM‑rich scrap (printed substrate, end‑of‑life sensors) is becoming a differentiator for cost and environmental reporting. 2026 is the year to operationalize recycling pilots into commercial flows.
Actionable 2026 playbook — five immediate moves
- Implement feedstock risk controls: combine long‑term purchase agreements, limited spot exposure, and recycled‑metal programs to stabilize cost of goods.
- Start dual‑qualification tracks for paste suppliers in parallel—prioritize suppliers with proven automotive/industrial qualification history and those offering co‑development resources.
- Invest 1–2 engineering cycles in paste optimization tied to yield improvement and miniaturization; small formulation gains cascade into substantial cost and performance benefits.
- Negotiate collaborative inventory models: consignment, vendor‑managed inventory, or buffer stock agreements at regional hubs to offset supply chain interruptions.
- Embed PGM sensitivity scenarios into product business cases and pricing models to ensure rapid commercial response if raw material dynamics shift.
Why PW Consulting’s report is a must‑have for 2026
The study blends granular technical insights (firing regimes, printing parameters, alloy options) with executable commercial playbooks (procurement structures, recycling implementation, supplier scorecards). Our forecast and scenario engine enables finance and product teams to stress‑test business plans against plausible platinum market outcomes. For leadership teams evaluating supplier strategies, qualification roadmaps or M&A plays in the materials tier, this report converts market intelligence into operational checklists and negotiation leverage.
To access the full dataset, supplier scorecards, and the interactive forecast model—designed to be embedded into procurement and product development workflows—visit the PW Consulting report page or contact our industry practice for a tailored briefing. The macro runway is constructive, but the 2026 battleground will be won by teams that pair technical differentiation with disciplined feedstock and supplier strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Pt Paste for Gas Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com