

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Bottom Anti-Reflective Coatings (BARC) Market Valued at USD 962.0 Million in 2025, Set to Grow at a 6.72% CAGR to USD 1,516.7 Million by 2032

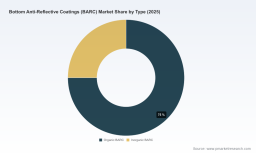
Worldwide Bottom Anti-Reflective Coatings (BARC) Market — Strategic Outlook for 2026: PW Consulting Industry Brief
PW Consulting’s latest market study on Worldwide Bottom Anti-Reflective Coatings (BARC) synthesizes five years of historical performance and a seven‑year forecast to deliver a decision-grade evidence base for semiconductor stakeholders preparing strategy and capital plans in 2026. Built on a 2025 base year with historical coverage from 2020–2025 and a forecasting horizon of 2026–2032, the report quantifies an accelerating market trajectory (CAGR 6.72%) and translates that trajectory into actionable options for procurement, R&D, manufacturing, and M&A teams.
Worldwide Technical Skills Development Software Market
Why this matters for 2026 decision-makers
-
Macro predictability with tactical complexity: The BARC market is moving from recovery into structurally higher demand driven by advanced lithography adoption and tighter overlay tolerances. Our consolidated market model places global revenues at roughly USD 962.0 Million in 2025, rising above USD 1.02 Billion in 2026 and projecting to approximately USD 1.52 Billion by 2032—a growth path that changes the economics of supply agreements, capacity investments, and vertical integration choices.
Worldwide Anhydrous Borax Market -
Concentration matters: The market exhibits material supplier concentration, with our CR3 and CR5 metrics indicating a marketplace where a small number of specialized chemical OEMs hold outsized influence on price, qualification lead times, and innovation cadence. That structural reality amplifies both supply‑risk and strategic opportunity.
Weather Broadcast Services Market -
Strategic timing: 2026 is a pivotal year for decisions on long‑lead capital, multi‑year supply contracts, and formulation roadmaps—choices made now will lock in cost structures and qualification paths for nodes and lithography platforms being deployed across 2027–2030.
Market trajectory and what the numbers signal
Our topline model captures steady expansion from the mid‑2020s into the early 2030s. After a mid‑cycle rebound through 2023–2025, demand scales meaningfully as fabs migrate toward tighter process windows and advanced lithography variants become more widely qualified. The consensus growth rate embedded in our forecast (CAGR 6.72% across the 2026–2032 horizon) is driven by a combination of fab tool upgrades, increased resist complexity, and differentiated BARC formulations required by next‑generation patterning.
For strategy teams, the implication is clear: vendors who can demonstrate reproducible qualification performance for high‑NA/EUV and immersion platforms will capture premium pricing and faster adoption curves. Conversely, suppliers with narrow product portfolios risk commoditization as customers prioritize multi‑node compatibility and supply security.
Key dynamics shaping supplier economics (operational and regulatory)
-
Raw material pressure: Central monomers and specialty solvents have shown step changes in cost and availability. For example, certain methacrylic derivatives experienced an approximate mid‑single digit percentage increase year‑over‑year due to supply constraints—impacts that are magnified for high‑purity chemistries used in BARC formulations. Procurement teams must model input cost pass‑through and negotiate clauses that reflect commodity and specialty chemical volatility.
-
Regulatory re‑formulation: New restrictions on select aromatic solvents under REACH Annex XVII are forcing European sales to be supported by reformulated product lines or alternative supply chains. R&D roadmaps should therefore prioritize solvent substitution pathways and validate performance parity under accelerated qualification cycles.
-
Trade and transport friction: Tariff actions (including a post‑review tariff structure imposed on certain imports) and shipping surcharges resulting from geopolitical disruptions have introduced incremental landed cost volatility. Even modest per‑kilogram surcharges materially affect small‑volume, high‑value chemicals economics and should be embedded into scenario planning across supplier tiers.
Report deliverables: what PW Consulting puts on your table
This study goes beyond top‑level forecasting. The report is designed as a practicable toolkit for 2026 strategic planning and includes:
-
Proprietary, node‑aware demand models that link lithography adoption curves to BARC demand drivers across the forecast period.
-
Supplier scorecards assessing technical breadth, qualification velocity, manufacturing footprint risk, and commercial flexibility—scored against PW’s procurement playbook.
-
Scenario playbooks for input‑cost shocks, regulatory restrictions, and trade disruptions—each with recommended contractual and operational mitigations.
-
Supplier negotiation tools including model clauses for price pass‑through, volume flex, and qualification cost allocation.
-
High‑level CAPEX needs analysis and a prioritization framework for fabs and chemical suppliers evaluating capacity expansions or backward integration.
To honor the “trailer” principle, we summarize the nature of these deliverables here while reserving the granular tables, plant‑level capacity maps, and downloadable scorecards for the full report—where readers will find the detailed splits and unit economics necessary for transactional decision making.
Competitive landscape — what the leaders are doing
The market is anchored by a set of specialist chemical companies that combine deep formulation expertise with high‑purity manufacturing capabilities. The competitive dynamic is driven by technology partnerships with lithography tool vendors, rapid qualification support for fab customers, and incremental product innovation for EUV and high‑NA systems.
-
JSR Corporation (Tokyo): A leading supplier with recent product introductions targeting EUV and high‑NA compatibility. JSR’s announced launch of a BARC material designed for next‑generation EUV systems in October 2025 signals a strategic bet on premium performance segments and early qualification wins.
-
Dow Electronic Materials / DuPont (Midland, Michigan): Brings broad commercial scale and established formulations for advanced nodes. Their portfolio and global reach make them a natural partner for large fabs seeking predictable qualification paths and supply continuity.
-
Tokyo Ohka Kogyo (TOK, Kawaguchi): TOK has demonstrated capacity commitment, including a targeted production expansion to serve sub‑3nm node demand. Their Kawasaki plant enlargement announced in mid‑2025 highlights the capital intensity and timing considerations for suppliers targeting aggressive node transitions.
-
Shin‑Etsu Chemical (Tokyo): Known for high‑purity materials and strong process support; recent certification activity underscores the ongoing emphasis on documented compliance and customer QA integration.
-
Nissan Chemical Corporation (Tokyo): Focused R&D on formulations adaptable to both 193nm and EUV process windows positions Nissan to participate across multiple lithography choices.
-
AZ Electronic Materials / Merck Group (Darmstadt): European presence and specialty chemistries complement global sourcing strategies, particularly for customers seeking multiple qualified sources.
Collectively these suppliers shape market structure: competitive on innovation, but with entry barriers linked to qualification cycles, cleanroom manufacturing investments, and regulatory compliance. The CR3 and CR5 indicators in our analysis show a market where a few vendors control the majority of volume—informing both supplier negotiation tactics and potential M&A surveillance strategies.
Actionable recommendations for 2026 (short checklist)
-
Lock strategic lead times now: Initiate multi‑year contracting conversations with preferred suppliers to secure qualification slots and capacity windows for 2027–2029 production ramps.
-
Hedge and diversify raw‑material exposure: Negotiate upstream supply agreements for critical monomers and implement dual‑sourcing for solvent classes under regulatory stress.
-
Prioritize reformulation funding: Allocate near‑term R&D budgets to solvent‑substitution and high‑NA compatibility testing to avoid downstream qualification delays in regulated markets.
-
Embed tariff and freight scenarios: Financial planning should include stress tests for import duty and shipping surcharge scenarios that materially alter landed cost calculations.
-
Monitor supplier concentration risk: Use bespoke scorecards (included in the full report) to track supplier health and create contingency plans for rapid requalification where feasible.
How to use this report
PW Consulting’s BARC market study is intended as a working instrument for commercial, operational, and capital allocators. It is tailored for head‑office strategy teams, procurement, fab process engineering, corporate development, and investment committees. The full report contains the granular segment models, supplier share matrices, pricing elasticities, and downloadable negotiation templates referenced in this brief.
For organizations that must transition from insight to action in 2026, the study provides both the forecast horizon and the tactical blueprints necessary to manage cost, quality, and time‑to‑market tradeoffs in a concentrated and technically demanding supply chain.
Next steps
-
Engage PW Consulting for a tailored briefing to map the report’s implications onto your specific node roadmap or supplier base.
-
Access the full dataset and annexes for transaction‑grade figures, supplier-level metrics, and scenario‑specific playbooks.
Contact PW Consulting to schedule a deep‑dive. Our team will walk through the models, validate assumptions against your internal data, and co‑design mitigation strategies that align with your 2026 strategic choices.
For detailed analysis of this topic, please visit the official page: Worldwide Bottom Anti-Reflective Coatings (BARC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com