

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Natural Aroma Chemicals Market to Expand at 6.8% CAGR, Surging to USD 3,968.75 Million by 2032

Worldwide Natural Aroma Chemicals Market 2026: Strategic Imperatives for Leaders — A PW Consulting Preview
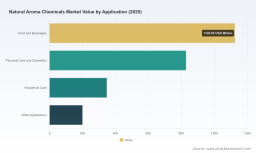
As companies prepare their 2026 strategic plans, natural aroma chemicals have moved from niche premium positioning to a mainstream operating imperative across flavor, fragrance, and personal-care value chains. Our latest market study, based on a comprehensive historical series (2020–2025) and a seven‑year forecast (2026–2032), demonstrates that the global natural aroma chemicals market is maturing into a resilient growth engine. The market reached approximately USD 2.50 billion in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 6.8%, driving the sector toward an expected near‑USD 4.0 billion by 2032. For senior executives evaluating portfolio prioritization, supplier strategies, or M&A in 2026, the implications are immediate and actionable.
Industrial Process Fine Bubble Generator Market
Why this preview matters for 2026 decision cycles
-
Evidence‑based momentum: The mid‑cycle acceleration captured between 2022 and 2025 signals structural demand — not a short‑lived fad — underpinned by reformulation mandates, consumer clean‑label preferences, and substitution of petrochemical routes.
LED Poultry Light Market -
Policy and procurement convergence: Regulatory constraints (notably IFRA and REACH) are compressing innovation cycles and supplier qualification timelines. Procurement and regulatory teams must align earlier in R&D to avoid costly late‑stage swaps.
Worldwide Church Presentation Software Market -
Value chain re‑engineering: Feedstock volatility and trade policy (including new reciprocal tariff layers implemented in 2025) are prompting a reconsideration of sourcing geographies, inventory strategies, and localized production versus global centralized supply.
Market trajectory: What the headline numbers tell us
Between 2020 and 2025 the market roughly doubled in scale from the low‑billion area to USD ~2.5 billion in 2025, reflecting a combination of rising unit demand in personal care and food & beverage, price mix effects toward premium natural extracts, and early commercialisation of biotech‑derived molecules. Our base‑case forecast — 2026–2032 at a 6.8% CAGR — implies steady expansion to just under USD 4.0 billion by 2032 under current policy and technology trajectories. The path is not linear: the model embeds mid‑term inflection points tied to regulatory updates, raw material shocks, and commercial ramp‑ups of precision‑fermentation players.
Key market dynamics shaping 2026 strategies
-
Regulatory reformulation pressure: IFRA and REACH remain primary drivers of reformulation toward cleaner, natural, and lower‑risk molecules. Companies with proactive regulatory intelligence and reformulation playbooks will shorten time‑to‑shelf and protect gross margin.
-
Feedstock and input cost volatility: Essential oils — the primary upstream feedstock — continue to exhibit price and availability swings. A complementary data point: the global essential oils market registered multi‑billion USD scale in 2025 and is forecast to grow further in 2026. Ingredient manufacturers must hedge exposure and redesign contracts that share risk across suppliers and buyers.
-
Biotechnology is crossing the chasm: Precision fermentation and biotech production routes are moving from pilot to commercial scale, delivering high‑purity natural compounds with potentially lower carbon footprints. Early adopters of biotech sourcing are positioning for cost and sustainability leadership.
-
Sustainability credentials as market currency: Lifecycle metrics (including product carbon footprint and rPCF disclosures) are becoming table stakes for enterprise customers. Recent commercial launches with reduced product carbon footprints demonstrate how suppliers are using rPCF to win shelf space and long‑term contracts.
-
Trade and tariff risk: New tariff constructs introduced in 2025 add granularity to sourcing decisions. For many buyers, the optimal supply network is becoming a hybrid of regional production hubs and strategic global suppliers to manage duty exposure and service levels.
Competitive landscape — strategic takeaways
The market exhibits moderate concentration: the top three and top five players control meaningful but not dominant shares (CR3 at roughly 28.5% and CR5 at roughly 42.2%). That structure creates a competitive field where scale matters for R&D and distribution reach, yet niches remain defendable for focused specialists.
-
Global integrators (e.g., longstanding flavor and fragrance majors) continue to leverage multi‑channel distribution, deep formulation expertise, and sustainability investments to secure strategic CPG partnerships. These players are expanding portfolios via biotech routes and targeted product launches that foreground carbon and traceability metrics.
-
Specialist natural houses and essential‑oil specialists retain advantages in botanical sourcing, provenance storytelling, and high‑margin fine fragrance segments. Their value proposition is strengthened by vertical integration into farm‑level sourcing and seasonal harvest management.
-
Regional and emerging suppliers are increasingly relevant for localized supply and cost competitiveness — especially where tariff exposure and just‑in‑time requirements favor near‑shoring.
Recent strategic moves illustrate these dynamics. Major suppliers have launched reduced‑product‑carbon‑footprint (rPCF) ingredients and expanded biotech‑derived portfolios, while others have invested in new production capacity for bio‑sourced musks and pine‑based ingredients. Such developments are not isolated product announcements; they represent a reallocation of R&D, capital, and commercial effort toward traceable, lower‑carbon supply chains.
What PW Consulting’s full report delivers (actionable, not academic)
-
Proprietary market model: Scenario‑driven forecasts (base, downside, and accelerated biotech adoption) with sensitivity levers for raw material prices, tariff shocks, and regulatory tightening.
-
Supplier strategic heatmap: Comparative assessment of >15 global suppliers across capability metrics — sustainability credentials, biotech readiness, geographic footprint, and customer concentration — plus a roadmap for supplier consolidation or diversification.
-
Commercial playbooks: Tailored go‑to‑market and procurement playbooks for CPGs, ingredient manufacturers, and contract manufacturers, including negotiation templates for rPCF claims and seasonal pricing clauses.
-
Regulatory risk matrix: Practical guidance for IFRA/REACH compliance, reformulation triggers, and timelines for supplier qualification to minimize reformulation cost and time to market.
-
M&A and partnership screening: A screened list of strategic acquisition targets and biotech partnerships, with financial and integration checklists designed to shorten diligence cycles.
-
Implementation tools: KPI dashboards for sustainability reporting, supplier scorecards, and an inventory‑to‑sourcing migration plan with estimated capex and payback horizons.
Practical 2026 playbook — recommended actions by stakeholder
-
For CPG and brand teams: Prioritize dual‑track reformulation (short‑term substitutions and long‑term platform changes). Require lifecycle metrics (including rPCF) from suppliers in RFPs and build 18‑month windows into launch timelines for high‑risk materials.
-
For ingredient suppliers: Accelerate certification of biotech routes and rPCF disclosures; pilot customer co‑innovation programs to lock in offtake; and consider near‑shoring critical volumes to mitigate tariff exposure and logistics risk.
-
For investors and PE sponsors: Target assets with validated botanical sourcing, proprietary purification technology, or biotech IP; valuation premia will accrue to suppliers that can demonstrate traceable supply and predictable scale‑up.
-
For procurement and risk teams: Rebalance supply portfolios to include strategic regional sources, implement hedging for key essential oil feedstocks, and embed tariff scenario planning in supplier scorecards.
Risks to monitor in 2026
-
Raw material shocks: Weather, crop disease, or rapid demand shifts in essential oils can produce price spikes that compress margins unless pass‑through mechanisms are in place.
-
Regulatory tightening: Faster than expected IFRA/REACH changes could force fast and costly reformulations across portfolios.
-
Biotech commercialization pace: While precision fermentation offers upside, commercialization bottlenecks (scale‑up failures, CAPEX overruns, or IP disputes) would delay expected cost advantages.
-
Trade policy shifts: Tariff and non‑tariff measures remain a tail risk for cross‑border supply chains; diversified sourcing and regional hubs reduce exposure.
Why PW Consulting’s report is strategically different
Many studies offer high‑level forecasts; our deliverable is designed for execution. We combine granular supplier benchmarking, regulatory timelines, and scenario models that link to procurement contracts and product launch calendars. The report is intentionally prescriptive — not just descriptive — offering checklists, contract language, and quantified scenarios to cut months off decision cycles and provide defensible inputs for board‑level strategy reviews.
Next steps — how to use this preview in your 2026 planning
-
Incorporate the 6.8% CAGR and near‑term supply risk assumptions into your 2026 budget and three‑year capex plans.
-
Commission a condensed supplier audit aligned to our heatmap methodology to rapidly identify single‑point vulnerabilities and near‑term strategic partners.
-
Mandate rPCF and traceability disclosures for all new supplier approvals to embed sustainability into procurement decision rules.
This preview outlines the strategic contours you will need for 2026. For the full market model, supplier heatmap, regulatory matrix, and the complete set of actionable playbooks — including scenario sensitivities and downloadable implementation tools — access the PW Consulting Worldwide Natural Aroma Chemicals Market report. The full intelligence package is designed to convert insights into executable plans and to de‑risk decisions in an increasingly volatile, sustainability‑driven market.
Contact PW Consulting to request the full report and accompanying executive workshop to align your 2026 roadmap with market realities.
For detailed analysis of this topic, please visit the official page: Worldwide Natural Aroma Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com