

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Worldwide Mine Shaft Elevator Market Poised for a 5.25% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Mine Shaft Elevator Market — Strategic Preview for 2026 Decisions
Executive snapshot
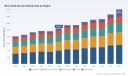
The worldwide mine shaft elevator market has moved from a niche safety and access technology to a strategic lever for operations, capital allocation, and downstream processing efficiency. After recovering from pandemic-era disruptions, the market reached roughly USD 1,050 million in 2025 and is forecast to exceed USD 1,140 million in 2026, with a compound annual growth rate (CAGR) of approximately 5.25% through 2032, when the market is projected to be close to USD 1,500 million. For executive teams planning capital programs, procurement windows, or M&A activity in 2026, these headline dynamics change the calculus: hoisting systems are no longer just engineering line items, they are portfolio-level decisions affecting safety, throughput, and long-dated operating cost profiles.
Heavy Duty Cable Protector Market
Why this report matters for 2026 strategic planning
-
Timing of capital deployment: The market’s steady growth and replacement cycles for mature shaft infrastructure create discrete windows where procurement costs, delivery lead times, and contractor availability materially affect project IRR. Our forecast identifies these windows and models sensitivity to lead times and component scarcity.
Worldwide Environment, Health and Safety (EHS) Management Software Market -
Risk-adjusted total cost of ownership (TCO): Hoist systems are capital-intensive and long-lived. Small design or supplier differences translate to meaningful lifecycle cost variance once safety upgrades, regulatory-driven retrofits, and rope replacement schedules are integrated. The report provides TCO frameworks that prioritize decisions which reduce lifecycle cash drag rather than simply minimizing upfront CAPEX.
Worldwide WeatherProof Outside Television Market -
Regulatory and compliance-driven replacement: New and updated safety requirements—most notably recent MSHA updates and existing federal rules that mandate overspeed, overwind, and automatic stop controls—accelerate upgrade cycles in some jurisdictions. Compliance timelines and the cost of non-compliance are modelled so executives can plan CAPEX and operational budgets with confidence.
What’s inside the PW Consulting report (practical, implementable contents)
-
Market sizing and scenario modelling — A transparent, bottom-up market-sizing methodology with alternate scenarios for commodity cycles, deepening of ore bodies, and regional capex shifts. The report provides scenario outputs for 2026 planning that can be embedded in capital approval packs.
-
Supplier benchmarking and procurement playbooks — Scorecards covering technical capability, service networks, delivery lead times, and aftermarket economics. We translate supplier attributes into procurement strategies (single-supplier vs multi-sourcing; buy-build vs partner; OPEX-based service contracts).
-
Regulatory compliance matrix — A practical matrix that maps common regulatory obligations (e.g., inspection regimes, motor-driven equipment standards, and hoist-specific safety requirements) to design and operational mitigations, with timelines to align compliance capex with broader mine plans.
-
Retrofit and replacement decision trees — Actionable decision frameworks to decide whether to retrofit, rebuild, or replace hoisting systems, incorporating lifecycle rope management, controller/software upgrades, and energy-efficiency retrofits.
-
Digital diagnostics and predictive maintenance playbook — Guidance on deploying nondestructive testing, rope-monitoring sensors, and predictive analytics to extend safe service life and rationalize spare-part inventories.
Competitive landscape — what to watch in 2026
The market exhibits moderate concentration: the top three suppliers account for a meaningful portion of market supply, while the top five capture a clear majority. That structure creates both supply-side leverage and opportunities for differentiated entrants who can address retrofit economics or specialized narrow-shaft applications.
-
Alimak Group (Stockholm, Sweden) — Known for rack-and-pinion industrial elevators and temporary/permanent vertical access solutions, Alimak’s strength is in modular, safety-certified platforms designed for personnel and materials in confined shaft environments. For buyers, Alimak represents a low-friction option for retrofit or vertical access projects where standardization and safety certification are priorities.
-
ABB (Zurich, Switzerland) — With a long history in complete hoist systems, ABB brings integrated electromechanical packages and control systems that enable higher automation and regenerative-energy capabilities. ABB’s recent collaboration to demonstrate novel vertical-bucket elevator concepts highlights the company’s push into capital-productive innovations that can reduce installation complexity and time.
-
SIEMAG TECBERG (Haiger, Germany) — A specialist in shaft hoisting systems with full mechanical and electrical solutions for production and service hoists. Recent project deliveries for multi-shaft systems indicate robust orderflow in certain markets and underline the importance of delivery orchestration in large, multi-system contracts.
-
Century Elevators (United States) — Focused on narrow-shaft permanent mining elevators with an emphasis on control systems and drives that meet mine safety codes. For operators with constrained shaft geometry, Century offers tailored solutions that minimize shaft modifications.
-
KONE Corporation (Espoo, Finland) — Applies elevator R&D and deep-shaft testing capability to mining applications, emphasizing energy-efficient hoists and extensive testing for deep vertical profiles. KONE’s approach benefits mines where energy consumption and deep-shaft performance are significant cost drivers.
Recent vendor moves and implications
-
SIEMAG TECBERG’s multi-system deliveries (May 2025) underline contractor capability as a differentiator: suppliers who can coordinate multiple shaft installs for a single client capture higher margin and reduce integration risk for operators.
-
ABB’s collaboration (Nov 2024) on vertical-bucket demonstrators signals vendor-led innovation aimed at reducing CAPEX and construction time. Buyers should evaluate demonstrator risk and partner early to capture first-mover retrofit economics where appropriate.
Regulatory and operational dynamics that will drive 2026 decisions
-
Regulation is a near-term driver: training programs and updated safety standards for electric motor-driven mine equipment, as well as prescriptive hoist inspection requirements, will push some operators to accelerate upgrades.
-
Component maintenance regimes matter more than ever: steel wire ropes and other critical components are subject to regular nondestructive testing and visual inspection regimes that change life-expectancy profiles and spare-part strategies. Investing in digital inspection and rope-monitoring technologies produces outsized returns on safety and uptime.
-
Service and aftermarket economics will shape supplier selection: with higher concentration among the largest suppliers, operators must balance immediate supplier reliability with the value of open-architecture controls and local service partnerships.
Recommendations for 2026 corporate decision-makers
-
Adopt a scenario-first CAPEX plan — incorporate sensitivity to delivery lead times, rope supply constraints, and regulatory acceleration when approving hoist-related capital budgets; small shifts in timing can change NPV materially given long asset lives.
-
Prioritize TCO over lowest-bid procurement — require lifecycle costing in all RFPs, including rope-change schedules, energy recovery options, and remote diagnostics; reward suppliers that demonstrate measurable lifecycle savings.
-
Invest in digital monitoring pilots — deploy rope- and gearbox-monitoring sensors on one critical shaft as a prelude to a systematic retrofit program; data from pilots will reduce uncertainty and support risk-based maintenance.
-
Defensive supplier strategy — given a market where top players command a significant share, lock in service agreements and consider staged supplier diversification for critical components to reduce single-point failure risk.
-
Explore strategic partnerships — engaging with vendors on demonstrator projects (as seen with ABB and vertical-bucket concepts) can reduce capital intensity and shorten project schedules if proven at scale.
How PW Consulting can help
PW Consulting’s Worldwide Mine Shaft Elevator Market report is designed as a practical decision-support tool for 2026 planning cycles. Our offering includes the full dataset and underlying models, supplier scorecards, executable procurement playbooks, and bespoke workshops that align hoist-investment decisions with broader mine planning and ESG objectives.
We intentionally provide this preview to highlight the strategic implications and practical outputs you can expect. To access full segmentation tables, regional breakout models, and supplier-level datasets that are essential to transactional diligence and procurement, please visit the report landing page or contact our client services team to commission a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Mine Shaft Elevator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Hydrochar Market Set to Climb from USD 285.5 Million in 2025 to USD 505.37 Million by 2032, Forecasting 8.5% CAGR
By pmarketresearch, 2026-08-12
Worldwide Hydrochar Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
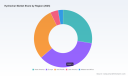
PW Consulting’s latest market study—anchored on 2025 as the base year and projecting through 2032—distills the strategic intelligence energy, waste and agriculture executives need to make decisive moves in 2026. The hydrochar market has shifted from niche technology to a commercial-scale value pool: global revenue rose from approximately USD 195 million in 2020 to USD 285 million in 2025, and our model now forecasts a trajectory to just over USD 505 million by 2032 at a compound annual growth rate (CAGR) of 8.5% (USD, revenue unit: Million). This report is designed as an operational playbook for boardrooms and deal teams—providing the analytical scaffolding required to convert emerging policy and feedstock advantages into sustainable competitive advantage.
Industrial Tilting Devices Market
Why 2026 is a Pivotal Year
-
Policy inflection points translate into commercial windows. Recent regulatory updates across major markets are tightening organic waste streams and creating clearer pathways for hydrothermal carbonization (HTC) outputs to access incentives designed for low‑carbon fuels and soil amendments. These policy drivers collapse uncertainty that had previously slowed capital deployment.
Worldwide Car Sensors Market -
Feedstock dynamics are converging with technology maturation. Availability of wet biomass residues and municipal biowaste at industrial scales is enabling project bankability in ways not present five years ago—meaning that feasibility studies completed today can be shovel‑ready within typical project development timelines.
Worldwide Chlortetracycline Market -
Investor appetite for carbon‑removal adjacent solutions has increased materially. Hydrochar’s dual role as a fuel substitute and durable carbon product accelerates its appeal to corporates seeking both scope‑reduction and carbon‑storage pathways.
Market Dynamics and Strategic Implications
-
Feedstock supply and logistics determine project economics. While the available tonnages of wet biomass are large, localized collection efficiency, seasonality, pre‑processing costs, and competing valorization routes (anaerobic digestion, composting) create winner‑takes‑most corridors for early movers who integrate supply chains.
-
Technology choice matters for market positioning. HTC variants and competing thermochemical routes diverge on capital intensity, yield, and product specs (energy density, ash content). Strategic buyers must stress‑test vendor claims against independent yield assumptions and downstream handling costs.
-
Market concentration remains low. The sector is populated with specialist technology providers and vertically integrated operators; the top players collectively occupy less than one‑third of the market today—indicating both fragmentation and opportunity for consolidation over the forecast period.
-
Policy‑linked revenue mechanisms are a double‑edged sword. Carbon credit streams and co‑firing incentives materially improve returns but introduce policy risk. Scenario planning across policy outcomes should be embedded in all capital allocation decisions.
Competitive Landscape: Who’s Deploying at Scale and What It Signals
Our fieldwork and primary interviews confirm a cohort of technology and project developers that are setting commercial benchmarks. PW Consulting’s competitive assessment evaluates these firms on technology maturity, feedstock flexibility, route‑to‑market, and financing models.
-
Ingelia (Barcelona, Spain) — Focused on HTC plants that convert sewage sludge and other biowaste into hydrochar for fertilizer and fuel applications. Their recent commercial plant start in Italy demonstrates a move from pilot to repeatable commercial installations, signaling a template for municipal partnerships.
-
TerraNova Energy GmbH (Münster, Germany) — Developer of the HTCycle platform with pipeline commitments for industrial‑scale plants. Partnerships announced for sizeable plants indicate a business model leaning on strategic alliances with waste aggregators and municipal authorities.
-
BlackCarbon GmbH (St. Pölten, Austria) — Produces premium hydrochar from lignocellulosic feedstocks aimed at industrial boiler replacement. Their recent capacity expansion speaks to demand from heavy industry seeking rapid coal substitution pathways.
-
Arbaflame A/S (Aarhus, Denmark) — Builds pelletized hydrochar for co‑firing in power plants. Their positioning illustrates the near‑term commercial opportunity in the power generation sector where co‑firing standards are clear.
-
Haffner Energy (Vitry‑le‑François, France) — Operator of the ERC process producing SynChar; certification of pilot plants shows intent to capture both energy and carbon sequestration use cases.
-
Antaco (Santiago, Chile) — Regional player converting forestry residues and sludge into marketable hydrochar, underscoring geographic diversification and the ability to tap forestry value chains in South America.
Taken together, these players illustrate two convergent strategies: (1) vertically integrated operators that control feedstock and offtake, and (2) technology licensors and OEMs seeking high‑margin equipment and licensing revenue. Investors should evaluate which model aligns to their time horizon—asset‑heavy, lower‑risk cash flows versus asset‑light IP plays with scalability upside.
Regulation, Science and the Value Equation
-
Regulatory tailwinds: Recent updates—such as stricter separate collection rules and clearer ETS treatment for co‑fired hydrochar—are reducing policy ambiguity in key markets and accelerating offtake negotiations for projects that can demonstrate lifecycle emissions reductions.
-
Performance metrics: Independent literature shows hydrochar can deliver high carbon yields from wet biomass and substantial energy densification, making it competitive as both a fuel substitute and a soil amendment—though specifications vary by feedstock and process conditions.
-
Feedstock scale: Large volumes of wet biomass residues are technically available in several regions, but economic capture of these volumes requires logistics integration, contract standardization, and often co‑investment with municipal or agricultural stakeholders.
What PW Consulting’s Report Delivers (Practical Tools for 2026 Actions)
This research is constructed to be operational. Highlights of the deliverables include:
-
A calibrated market model from 2020–2032 with base‑year (2025) reconciliation and scenario variants that stress policy, feedstock cost, and yield assumptions—built for sensitivity testing by CFOs and strategists.
-
Technology comparison matrix and vendor scorecards—benchmarks for CAPEX/OPEX, yields, and product specs to inform procurement and partner selection.
-
Supply‑chain maps and contract templates—practical tools for securing feedstock volumes and structuring offtake agreements, including recommended KPIs and pricing collars.
-
Regulatory impact matrix—translated into quantifiable P&L levers for project financial models and permitting timelines by jurisdiction.
-
M&A and JV playbook—target screens, valuation heuristics, and due diligence checklists tailored to hydrochar assets and technology providers.
-
Commercial go‑to‑market playbooks for utilities, waste companies and industrial end‑users—detailing pilot design, scale‑up milestones, and stakeholder engagement templates.
Actionable Recommendations by Stakeholder
-
Corporate investors and strategics: Lock in feedstock supply through long‑dated contracts or upstream equity, and prioritize technologies with independent yield validation. Layer policy scenarios into valuation—don’t rely on a single incentive mechanism to validate returns.
-
Waste managers and municipalities: Evaluate HTC partnerships as part of an integrated waste‑valorization portfolio. Use demonstrations to validate seasonal collection models and offtake aggregations before committing to full‑scale plants.
-
Utility and power producers: Fast‑track co‑firing pilots where permitting and fuel handling are clearly defined, and use hydrochar as a transitional lever to reduce coal exposure while assessing feedstock price volatility.
-
Equipment manufacturers and EPCs: Standardize modular designs to reduce project timelines and bill‑of‑materials costs; aftermarket service contracts will be an important recurring revenue stream.
-
Policy makers: Harmonize quality standards for hydrochar products and create transparent carbon accounting rules to lower market entry barriers and foster investment.
Methodology and the “Trailer” Principle
PW Consulting’s analysis synthesizes proprietary interviews, plant‑level performance data, vendor disclosures and third‑party literature. The report provides granular spreadsheets and project‑level cashflow models for subscribers. In line with our “trailer” approach, this press release communicates high‑confidence directional findings and strategic recommendations, while detailed segmental splits, regional breakdowns, and proprietary unit‑cost tables are reserved for the full report accessible via our website.
Next Steps for Decision Makers
If 2026 is when your organization moves from study to execution, the right inputs today can determine who captures value tomorrow. PW Consulting’s Worldwide Hydrochar Market report is engineered to shorten the learning curve, de‑risk capital allocation, and identify the most promising corridors for roll‑out and consolidation. For teams preparing investment memos, RFPs, or regulatory filings this year, the models, vendor scorecards and contract templates in the full report will be indispensable.
To explore the full dataset, segmental forecasts and our proprietary project models, visit the PW Consulting report page or contact our hydrochar practice for a briefing and tailored scenario analysis.
For detailed analysis of this topic, please visit the official page: Worldwide Hydrochar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Canine Mammary Tumor Treatment Market Poised for 7.58% CAGR, Eyes USD 1.41 Billion by 2032
By pmarketresearch, 2026-08-12
Worldwide Canine Mammary Tumor Treatment Market: Strategic Imperatives for 2026
By PW Consulting — Chief Industry Analyst
Worldwide Blackcurrant Seed Oil Market
Executive snapshot
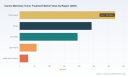
The global market for canine mammary tumor treatment is transitioning from a fragmented, surgery-dominant landscape into a multi-modal, innovation-driven healthcare market. Our new PW Consulting report—anchored to a 2025 base year and projecting through 2032—finds the market valued in the high hundreds of millions of USD in 2025 and growing at a compound annual growth rate of roughly 7.6% through the forecast horizon. Under that trajectory, the market moves into the low‑billion dollar range by the end of the forecast period, reflecting sustained clinical demand, technology diffusion in specialty care, and an expanding therapeutic pipeline that spans surgery, chemotherapy, radiation, and next‑generation targeted and immune therapies.
Worldwide Industrial Arc Furnaces Market
Why 2026 is a pivotal year for corporate strategy
- Regulatory inflection points and designation pathways are lowering barriers for veterinary oncology assets, enabling companies to accelerate commercialization strategies that were previously constrained by regulatory ambiguity.
- Precision diagnostics and genomics are shifting oncologic decision‑making from empiric to targeted approaches—creating new pricing, reimbursement, and revenue model opportunities for diagnostics–therapy bundles.
- Capital allocation choices (organic R&D vs. acquisition/partnership) made in 2026 will determine which players secure durable access to high‑margin specialty channels in the veterinary ecosystem over the next five to seven years.
Core market dynamics and clinical context
Surgical resection remains the recognized gold standard for most canine mammary tumors, with adjuvant systemic therapies applied selectively for high‑risk or metastatic disease. That clinical orthodoxy coexists with growing use of off‑label targeted agents and precision radiotherapy in specialized centers, producing a two‑tier market: broad surgical care delivered across general practice and veterinary hospitals, and concentrated, higher‑value care delivered through specialty oncology clinics, referral centers, and dedicated radiation providers.
Worldwide Agile and DevOps Services Market
Two important structural features drive the market’s outlook:
- Comparative oncology: Canine mammary tumors function as a spontaneous model for human breast cancer, creating bidirectional research value. This accelerates translational opportunities (and investor interest) in PI3K inhibitors, tyrosine kinase inhibitors, and vaccine/immunotherapy platforms.
- Service convergence: Diagnostic genomics, targeted systemic agents, and precision radiotherapy are coalescing into bundled care pathways—heightening the strategic importance of cross‑sector partnerships (pharma, device, diagnostics, and service providers).
Competitive landscape — who matters and why
The market is characterized by an ecosystem of large animal-health incumbents, specialized veterinary oncology innovators, and human‑oncology players translating assets into veterinary use. The competitive map is best understood as overlapping clusters: broad animal-health firms with deep commercialization channels; niche biologics and small‑molecule developers innovating in targeted veterinary oncology; precision-radiotherapy system vendors enabling advanced non‑surgical care; and diagnostic/precision‑medicine providers connecting molecular insights to treatment decisions.
Key strategic profiles covered in our analysis:
- Established animal-health leaders that leverage scale, distribution, and portfolio breadth to commercialize oncology-supportive products and in some cases targeted agents (examples profiled in the report include major multinational animal‑health companies).
- Small to mid‑cap biotech firms that advance veterinary‑first molecules (e.g., tyrosine kinase inhibitors and novel immunotherapies) and pursue accelerated or conditional regulatory pathways to establish early clinical footholds.
- Precision‑medicine platforms and genomic diagnostics businesses that create differentiated clinical value by matching existing and emerging therapies to tumor biology—enabling premium pricing and improved outcomes.
- Radiation‑technology and service providers delivering stereotactic radiosurgery and advanced radiotherapy—these providers are central to non‑surgical therapeutic expansion in tertiary veterinary centers.
Our competitive chapter synthesizes public filings, device adoption trends, clinical registries, and direct interviews to produce practical competitor playbooks—mapping each major player’s strengths, capability gaps, go‑to‑market channels, and near‑term catalysts.
Recent industry developments with immediate strategic consequences
- Regulatory momentum: Recent regulatory designations for veterinary oncology molecules underscore the viability of accelerated development paths. Companies should re‑assess their regulatory strategy to determine whether designations such as conditional approvals or minor‑use pathways can be pursued to shorten time‑to‑market.
- Surgical precision and intraoperative innovation: Emerging intraoperative imaging modalities are improving margin assessment and reducing local recurrence risk—altering surgical standards of care and influencing referral patterns to centers of excellence.
- Clinical translation: Advances in oral targeted agents and immunotherapies originally developed for other canine cancers are being evaluated for mammary tumors; this creates both competitive risk and partnership opportunity for animal‑health firms and biotech sponsors.
What the PW Consulting report delivers — practical, decision‑ready content
This study is built to inform capital allocation, portfolio prioritization, M&A diligence, and commercial planning for 2026. The deliverables include:
- A transparent market‑sizing model (base year 2025) with scenario analysis and a modeled CAGR to 2032—designed for integration into corporate financial planning.
- Therapeutic and service pathway maps that translate clinical guidelines into commercializable care bundles and pricing templates.
- Pipeline and clinical evidence compendia that align candidate molecules and devices to unmet clinical needs, recommended trial endpoints, and pragmatic trial designs optimized for veterinary regulatory pathways.
- Channel and capability assessments that show where to invest (clinical training, specialty center buildouts, vendor partnerships) to capture higher‑value care segments.
- Negotiation playbooks and term‑sheet templates for licensing, co‑development, and distribution agreements—customized for veterinary oncology’s stakeholder map.
- Financial benchmarking and ROI calculators for investment in advanced radiotherapy equipment, genomic testing platforms, and new molecular entities.
Strategic options for executives in 2026
Based on our analysis, executive teams should evaluate a mix of the following moves—each accompanied in the report by tactical checklists and implementation timelines:
- Prioritize translational assets that have a realistic regulatory pathway for conditional/accelerated approval in veterinary indications; pursue early engagement with regulators to de‑risk development timelines.
- Form strategic alliances between diagnostics providers and systemic‑therapy sponsors to create bundled offerings—coupling genomic tests with therapy access programs and outcome tracking to justify premium pricing.
- Invest selectively in specialty radiotherapy capacity or partner with existing service providers to capture referrals for non‑surgical cases; financial models contained in the report demonstrate payback timelines under conservative utilization assumptions.
- Use targeted M&A to acquire capability gaps—diagnostics, translational oncology expertise, or regional specialty networks—rather than broad, horizontal deals that dilute focus.
- Build center‑of‑excellence pilots to gather real‑world evidence and case series that support product differentiation, pricing, and payor conversations.
Risk and mitigation framework
While the growth profile is attractive, decision‑makers must manage several risks: regulatory uncertainty for label expansions, variability in owner willingness to pay for advanced interventions, and channel fragmentation between general practice and specialty centers. The report provides a mitigation matrix that links specific near‑term investments (e.g., outcomes registries, tiered pricing, and education programs) to measurable KPIs to reduce these risks.
Why our dataset matters
PW Consulting’s market model synthesizes multi‑source demand indicators, procedure volumes, pricing benchmarks, and adoption curves. It quantifies total addressable demand at the market level and generates bottom‑up revenue scenarios tied to adoption levers—without exposing proprietary, directionally sensitive segment-level tables in this preview. For commercial teams and corporate strategists, the model serves as a deterministic starting point for scenario planning and for stress‑testing business cases under multiple reimbursement and utilization assumptions.
Call to action
For executives preparing 2026 budgets, our report converts clinical trends into executable commercial initiatives. If you are evaluating product investments, potential partnerships, or regional expansion in veterinary oncology, the full PW Consulting study contains the granular data, competitive intelligence, and playbooks you need to move from strategy to execution. Visit our report page to access the complete dataset, company profiles, and customizable financial models that underpin the findings summarized here.
Contact PW Consulting to schedule a proprietary briefing and a hands‑on workshop that translates these insights into a 90‑day action plan tailored to your organization’s capabilities and strategic objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Canine Mammary Tumor Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 4.52% CAGR for Worldwide Pigment-Grade Titanium Dioxide Market Through 2032
By pmarketresearch, 2026-08-12
Worldwide Pigment-grade Titanium Dioxide Market — Strategic Outlook for 2026 Decision-Makers
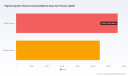
PW Consulting’s newest industry briefing, “Worldwide Pigment-grade Titanium Dioxide Market,” provides a concise, forward-looking synthesis intended to sharpen executive decision-making as companies plan for 2026. Drawing on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study places the pigment-grade TiO2 market in a tight, policy- and cost-driven context. In short: after a recovery from pandemic-era volatility the market reached USD 24,157.8 Million in 2025 and is projected to grow at a steady 4.52% CAGR through the forecast window, with an anticipated market scale exceeding USD 32.9 Billion by 2032.
Workstation Power Supply Market
Why this report matters for 2026 strategy
-
Timing: 2026 will be a hinge year where the interaction of regulatory tightening, raw material stress, and investment cycles will determine who can compete effectively in both price-sensitive and premium coatings segments.
Niti Memory Alloy Stent Market -
Risk Visibility: Several structural risks—feedstock price volatility, energy cost inflation tied to decarbonization, and trade-policy frictions—will meaningfully re-shape procurement, supply chain design, and pricing power in 2026. Our briefing quantifies these forces and models downside scenarios to inform contingency planning.
SAW Grade Lithium Niobate Thin Film Market -
Competitive Leverage: The market shows moderate concentration (CR3 ~38.5%; CR5 ~52.1%), implying that mid-tier players can still capture niches if they align investments with emerging technical and regulatory requirements. The report identifies those niches and the capabilities needed to exploit them.
What decision-makers will find in the briefing
The report is structured to be immediately operational for leadership teams preparing 2026 plans. Key deliverables include:
-
Market sizing and trend diagnostics — an audited baseline (2020–2025), a 2026 opening-position, and scenario-driven projections to 2032 that stress-test growth against raw material and regulatory shocks.
-
Segment playbooks — practical guidance on choosing process and product pathways (chloride vs. sulfate processes; rutile vs. anatase formulations), with decision trees that map capital intensity, feedstock exposure and downstream value capture without revealing confidential subsegment datapoints in this summary.
-
Price and cost analytics — an independent assessment of the primary cost drivers, including ilmenite and synthetic feedstock dynamics, energy surcharges, and processing differentials. The briefing includes sensitivity matrices that translate commodity moves into margin impacts for typical cost structures.
-
Supply-chain resilience templates — supplier scorecards, inventory strategy variants (JIT, buffer-stock, multi-sourcing), and trade-risk playbooks that factor in tariffs, force majeure scenarios and logistics bottlenecks.
-
Regulatory & ESG roadmap — compliance checklists for key markets, implications of recent EU and Chinese measures, and an emissions-control investment calculator that quantifies payback periods on energy-efficiency and decarbonization upgrades.
-
Competitive and M&A radar — benchmarking tools that position incumbents and challengers on capacity, process mix, and product focus to help identify attractive acquisition or partnership targets.
Market dynamics shaping 2026 decisions
Several converging forces make 2026 a defining year:
-
Feedstock pressure. Ilmenite prices rose materially into late 2024, reflecting supply tightness from major sources. This has direct pass-through potential for producers and will be a top-line risk for buyers planning procurement contracts in 2026.
-
Production footprint rationalization. Chinese regulatory moves to eliminate older sulfate-process capacity have realigned global supply chains. That structural rebalancing amplifies the strategic value of flexible capacity and of investments that shift production toward lower-emission chloride routes where feasible.
-
Trade policy frictions. Remaining tariffs in the US and other trade measures continue to alter regional sourcing economics. Procurement teams must factor tariff scenarios into 2026 supplier selection and near-shore vs. global sourcing trade-offs.
-
Energy and decarbonization costs. Electricity and carbon-control measures have pushed production surcharges higher in some markets; energy-efficiency upgrades and alternative energy contracts will therefore be central to cost competitiveness for plants running in 2026 and beyond.
-
Regulatory compliance complexity. Changes to REACH and other chemical import regimes have tightened the requirements for certain nano-forms and high-performance grades, necessitating updated compliance strategies and potential reformulation roadmaps.
Competitive landscape: key players and strategic takeaways
The briefing includes executive profiles and strategy implications for the major manufacturing and specialty players. Highlights for executives preparing 2026 action plans:
-
The Chemours Company — continues to leverage brand and formulation innovation (notably new water‑based optimized grades) to sustain premium positioning in coatings. Strategy implication: prioritize R&D collaborations with downstream formulators to secure specification lock-in in waterborne systems.
-
Tronox Holdings — is expanding capacity in select geographies, reinforcing its chloride-process play. Strategy implication: evaluate partnerships or offtake arrangements to ensure access to chloride-route product as demand for higher-performance rutile grades rises.
-
Lomon Billions Group — with broad global pricing influence, recent price increases underscore the pass-through levers large integrated producers possess. Strategy implication: buyers and smaller competitors should model supplier price-shock scenarios and explore hedging or longer-term contracts.
-
CNNC Hua Yuan & other Chinese producers — the interplay of force majeure events and regional capacity adjustments highlights the need for multi-regional supply strategies. Strategy implication: diversify supplier base and maintain dual-sourcing where tariffs and local restrictions create single-supplier risk.
-
Regional specialists (e.g., ISK, Tayca, Precheza) — retain advantages in high-end automotive and specialty applications where product performance trumps raw-material cost. Strategy implication: target premium niches with differentiated product claims and certification support.
Recent industry developments — implications for 2026
-
Price adjustments and input-cost inflation (notably energy and ilmenite) indicate that contract structures signed in 2025 could be re-opened or contested in 2026. Procurement teams must build flexible indexation clauses and dispute-resolution paths into supply agreements.
-
Capacity expansion projects completed in 2024–2025 materially alter regional availability in certain grades and routes; firms must map their exposure to those facilities and stress-test their commercial forecasts against accelerated ramp-ups or delayed startups.
-
Regulatory enforcement in major markets creates certification and label risks for non-compliant grades — requiring immediate investment in testing, traceability, and documentation workflows if companies intend to maintain market access in 2026.
How PW Consulting supports execution
Beyond the printed analysis, PW Consulting’s deliverables are designed for immediate use in 2026 planning cycles:
-
Customizable Excel models: interactive topline and margin scenarios, supplier-stress simulators, and investment appraisal templates.
-
Board-ready slide decks: concise diagnostics and recommended strategic moves for procurement, operations, and corporate development teams.
-
Supplier risk matrices and RFP templates: to accelerate re-sourcing and to introduce contractual protections against price, capacity and regulatory shocks.
-
Regulatory compliance playbooks and emissions investment calculators: to quantify both compliance costs and potential operational savings from energy modernization.
What we are not releasing publicly (and why)
In keeping with the “trailer” approach to this briefing, we are intentionally withholding the granular subsegment tables, full regional and application splits, and the detailed company-level revenue bridges from this summary. Those data elements are central to transactional decisions and M&A valuation work, and they are available in the full report package and accompanying data license. The summary above outlines the strategic contours and actionable insights needed to decide whether to procure the full dataset for 2026 planning.
Recommended 90‑day actions for 2026 preparedness
-
Initiate a rapid supplier-exposure audit focused on feedstock origin, process type (chloride vs. sulfate) and tariff risk to identify single points of failure.
-
Stress-test product margins under ±20% ilmenite and ±15% electricity-cost scenarios and create contingency pricing playbooks for customer contracts.
-
Accelerate compliance and testing programs for EU and key export markets to avoid market-access interruptions tied to recent regulatory updates.
-
Evaluate strategic partnership opportunities with chloride-route capacity owners or specialty players to secure access to high-margin grades.
Next steps
For procurement, operations, R&D and corporate development leaders planning 2026 moves, PW Consulting’s full “Worldwide Pigment-grade Titanium Dioxide Market” report provides the data tables, scenario models and supplier dossiers needed to convert strategic options into executable plans. For a sample executive summary, licensing options, or to arrange a briefing with our lead analysts, please contact PW Consulting via our official channels. The complete dataset and interactive models are available to licensed subscribers and advisory clients.
PW Consulting — equipping leaders with the market intelligence needed to make high-consequence, time-sensitive decisions in the evolving pigment-grade titanium dioxide landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Pigment-grade Titanium Dioxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Copper Hollow Conductors Market Poised to Reach USD 403.9 Million by 2032
By pmarketresearch, 2026-08-12
Worldwide Copper Hollow Conductors Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market intelligence on the Worldwide Copper Hollow Conductors market distills five years of historical performance, an actionable 2026–2032 forecast horizon, and a set of practical tools designed to shape boardroom decisions in 2026. This brief provides a high‑signal orientation for executives — highlighting market momentum, supply‑chain pressure points, competitive dynamics, and high‑payoff strategic moves — while preserving the granular segmentation and financial models for our full report and interactive dashboards.
Worldwide Smart Home Displays Market
Market trajectory at a glance
Using 2025 as the analytical base year, the market has demonstrated steady expansion through the historical window and is projected to maintain mid-single‑digit growth across the seven‑year forecast period. Key macro metrics from our model: the market has grown from the low‑hundreds (USD Million) in 2020 to an expanded base in 2025, and our scenario-anchored forecast projects continued growth through 2032 at a compound annual growth rate of approximately 5.49%. PW Consulting’s topline and scenario tables (expressed in USD Million) are included in the full report and permit roll‑forward analyses under alternative copper price and demand scenarios.
Worldwide Lithium-Ion Battery ICs Market
What’s driving the market in 2026
-
Electrification and heavy current applications: Rising deployment of infrastructure and industrial systems that require high‑performance water‑cooled conductors continues to sustain demand for hollow copper shapes designed for low-loss, high‑current density environments.
Video Security SoC Market -
Medical and scientific capital equipment: Investment cycles in MRI systems and high‑energy physics facilities keep premium, specification‑driven hollow conductors in stable demand, favoring suppliers who can deliver strict tolerances and traceable metallurgy.
-
Industrial heating and specialty manufacturing: Induction heating and process furnaces remain reliable pockets of demand for custom profiles and internally cooled channels, creating value for producers with flexible tooling platforms.
-
Price and supply‑side volatility: Commodity copper price swings — which reached record highs in early 2026 before moderating — and evolving midstream economics (including unusually low treatment and refining charges in recent quarters) are reshaping cost structures across the value chain and pressuring margins for downstream fabricators.
Supply‑side dynamics and risk vectors
-
Raw material volatility: The copper price environment entered 2026 with exceptional volatility, driven by accelerated electrification demand and cyclical manufacturing dynamics. Short‑term price spikes and divergent market forecasts from major banks underline the need for active procurement strategies and dynamic pass‑through pricing clauses in supply contracts.
-
Midstream margin compression: Despite price spikes at the metal level, treatment and refining charges for smelters recently hit multi‑year lows — an unusual combination that tightens the window for margin recovery across the midstream and amplifies execution risk for producers without disciplined cost control.
-
Concentration and bargaining power: The market exhibits a moderate level of supplier concentration — three players account for a meaningful share of production capacity and the top five further increase that share. This concentration creates structural advantages for leading producers around scale, specialized tooling, and customer relationships, but also leaves space for regional specialists and low‑cost manufacturers to compete on speed and customization.
-
Regulatory and sustainability pressures: Tighter environmental standards and buyer expectations on traceability (from ore to conductor) are raising compliance costs and favoring manufacturers with robust sustainability roadmaps and digital traceability systems.
Competitive landscape — capabilities that matter in 2026
Across global manufacturers, several recurring capability patterns determine competitive advantage: precision tooling for complex cross‑sections, capacity for internally cooled channels, rapid prototyping and short lead times, alloy expertise (including oxygen‑free and high‑conductivity grades), and geographically diversified production footprints to serve capital equipment OEMs and utilities.
-
Luvata (Pori, Finland) — Recognized for highly configurable tooling and a deep focus on high‑magnetic‑field applications. Their product breadth and short lead time model make them a preferred partner for MRI and laboratory magnet customers where specification and delivery reliability are non‑negotiable.
-
KME (Germany) — A multi‑plant European player with integrated capability across bars, profiles and hollow conductors. Recent R&D outputs demonstrate an institutional commitment to digitalization of the copper value chain, which can lower lead times and improve traceability.
-
Proterial Metals (Japan) — Legacy metallurgy and manufacturing competence with a focus on tough‑pitch copper grades and applications in large‑scale generators and high‑energy physics, where material performance under extreme conditions is critical.
-
cunova and regional specialists — Firms that combine modern machinery and process control with localized customer service are increasingly effective at winning industrial and regional OEM business.
-
Fabmann , Oriental Copper , Extube , S&W Wire Co. , and Channel Metal — These companies each play to specific strengths: complex profile machining, extrusion/drawing quality, ultra‑high conductivity grades, seamless tubing for water‑cooling, and customized microwave or magnet solutions. Buyers commonly select suppliers from this cohort when the priority is either price competitiveness or a narrowly defined technical capability.
Recent corporate actions underscore these capability bets: KME’s BMBF‑backed project on production chain data collection and Luvata’s product positioning for demanding induction furnace applications both reflect the industry’s twin focus on digital traceability and application‑specific productization.
What PW Consulting’s report delivers (practical, executable content)
-
Verified market sizing and forward scenarios (USD Million) with sensitivity to copper price, demand shock, and policy shifts — ready to insert into investor models and procurement playbooks.
-
Competitive benchmarking and supplier scorecards that map technical capability, capacity, lead time, and sustainability credentials — enabling rapid short‑lists for sourcing and strategic partnerships.
-
Cost‑to‑serve and margin decomposition templates that quantify the impact of copper price swings, TC/RC variations, and regional labor/energy differentials on unit economics.
-
Commercial diligence modules and an M&A playbook for acquirers that includes pro forma valuation ranges, integration red flags, and synergies specific to hollow conductor manufacturing.
-
Go‑to‑market and product roadmap recommendations for suppliers seeking to move up the value chain (e.g., internal cooling, high‑precision MRI coils, EV stator cooling solutions), plus regulatory and sustainability checklists for compliant scale‑up.
-
Interactive dashboards and raw data appendices (2020–2025 historicals; 2026–2032 forecasts) that preserve confidentiality around granular splits while enabling client‑side drilldowns under NDA.
Strategic imperatives for 2026
-
Procurement: Implement dynamic hedging and strategically diversified sourcing. Given commodity volatility and midstream margin pressure, procurement teams should combine rolling hedges, fixed‑price components, and volume‑tiered contracts to stabilize unit costs.
-
Product strategy: Prioritize development of internally cooled profiles and tailored alloys that address emerging needs in electrified infrastructure and high‑field medical equipment — these features command premium pricing and improve customer stickiness.
-
Operations and footprint: Reassess capacity allocation against regional demand clusters and logistic cost curves. For capital planners, modest near‑term capacity expansion in lower‑cost jurisdictions plus selective automation of finishing operations delivers the best risk‑adjusted returns.
-
M&A and partnerships: Target bolt‑on acquisitions that add tooling depth, rapid prototyping capabilities, or regional distribution channels rather than broad horizontal scale plays. Strategic alliances with foundries and precision machining houses can create differentiated integrated offers.
-
Sustainability and traceability: Invest in digital traceability and supplier auditing now; buyers increasingly require chain‑of‑custody data and emissions disclosures. Early investment reduces tender friction and unlocks premium contracts with OEMs in medical and scientific segments.
Immediate next steps for executives
-
Request PW Consulting’s full dataset and model pack (2020–2032) to run bespoke scenarios against your cost base and product mix. The summary here is deliberately non‑exhaustive to preserve competitive value — the full report contains the granular inputs and downloadable spreadsheets used in our models.
-
Commission a rapid supplier audit focused on delivery reliability, tooling flexibility, and alloy traceability — ideally delivered as a two‑week diagnostic that produces a prioritized action plan.
-
For investors and M&A teams: engage our commercial diligence team for a targeted valuation and integration risk assessment aligned with the current price volatility and projected demand paths through 2032.
PW Consulting’s Worldwide Copper Hollow Conductors Market report is built to be immediately operational for procurement, product, and corporate strategy teams preparing for 2026. To access the full analysis, interactive visualizations, and the confidential segmentation tables that underpin our recommendations, please visit our report page or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Worldwide Copper Hollow Conductors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Wheel Balancer With Touchscreen Market Hits USD 391.0 Million in 2025, Poised for Further Growth
By pmarketresearch, 2026-08-12
Worldwide Wheel Balancer With Touchscreen Market — Strategic Outlook for 2026: Why C-Suites and Product Leaders Need PW Consulting’s New Report
Executive summary
PW Consulting’s latest market research report on the Worldwide Wheel Balancer With Touchscreen Market (base year 2025, historical 2020–2025, forecast 2026–2032) delivers a pragmatic, decision-focused view for executives planning capital allocation, product roadmaps, and M&A activity in 2026. Our analysis finds the market at a clear inflection point: after robust recovery through 2020–2025, the installed-base upgrade cycle and rising demand for digitally enabled shop equipment will sustain growth through the forecast period at a compounded annual growth rate (CAGR) of approximately 6.55%.
Worldwide Thermal Conductive Sheet Market
Why this matters for 2026 strategy
-
Market momentum entering 2026 supports confident investment but requires selective prioritization. With the global market size measured at the 2025 base year and modeled through 2032, players must choose between competing near-term returns and long-term platform plays (connectivity, diagnostics, and automation).
Worldwide Flotation Cell Market -
Touchscreen-enabled balancing equipment has migrated from “nice-to-have” to a productivity and diagnostic hub in professional workshops. Decisions in product development, channel incentives, and aftermarket service investments in 2026 will determine who captures the high-value upgrade cycle.
Digital Pathology Image Analysis Software for Clinical Market -
Supply-chain and material considerations—particularly steel and electronic components—introduce cost and lead-time variability that will affect 2026 procurement strategies and pricing policies.
Market trajectory and sizing: what the numbers mean
Our bottom-up model synthesizes equipment shipments, replacement cycles, average selling prices, and aftermarket demand to project the market through 2032. The 2025 market midpoint is a practical decision benchmark: it quantifies the absolute scale of opportunity while the 6.55% CAGR provides the growth tempo buyers and investors should expect. Together these metrics help stretch internal business cases beyond anecdote to a defensible financial plan for 2026 investments — whether funding an R&D sprint, expanding distribution, or underwriting a tuck-in acquisition.
Key market dynamics shaping 2026 choices
-
Technology convergence: Touchscreen interfaces have become table stakes; value differentiation now comes from embedded diagnostics, 3D imaging, laser-guided workflows, and seamless connectivity with dealer/shop management systems. OEMs and independent manufacturers are converging on platform-level features that increase workshop throughput and service ticket depth.
-
Automation spectrum: The market is bifurcated between high-throughput fully automatic systems and flexible semi-automatic solutions. Each segment maps to distinct buyer economics — from large multi-bay tire shops and vehicle manufacturers to smaller independent service centers — and therefore requires different go-to-market plays.
-
Raw material and component exposure: Steel, sensors, motors, and electronic subsystems are core inputs. Our sector analysis indicates procurement volatility and concentrated component supply chains; contract manufacturers and OEMs should embed scenario-based sourcing strategies into 2026 operating plans.
-
Regulatory and sustainability pressures: Environmental rules are accelerating the shift to recyclable weighting materials. Zinc-based balancing weights are gaining share because of recyclability, despite carrying a price premium versus legacy alternatives — a factor that intersects with product positioning and customer education requirements for 2026.
-
Aftermarket expansion: Rising vehicle parc and ongoing aftermarket demand are durable tailwinds. However, the revenue mix is evolving: sales of diagnostic-capable balancers, recurring software subscriptions, and service contracts are becoming material contributors to lifetime value.
Competitive landscape — patterns, not playbooks
The vendor ecosystem is populated by long-established workshop-equipment manufacturers and fast-moving innovators. Our qualitative and quantitative assessment highlights three practical takeaways for 2026 planning:
-
Differentiation through integration: Firms that package touchscreen hardware with advanced diagnostic suites and automated workflows create stickier customer relationships. Leaders are layering features such as laser weight placement, 3D/2D imaging, and guided user interfaces to reduce service time and up-sell consumables and diagnostics.
-
Margin pressure and premiumization: Vendors targeting high-volume professional shops are investing in direct drive architectures and diagnostic-capable models to justify premium pricing. Conversely, semi-automatic, cost-efficient platforms remain essential to capture smaller service centers where capital budgets are constrained.
-
Service and channel economics: Companies that strengthen dealer training, remote diagnostic support, and spare parts logistics gain a competitive edge. Aftermarket service contracts are fast becoming a principal lever to improve gross margins and customer retention.
Our competitor profiles evaluate product portfolios, go-to-market footprints, and innovation cadence across the vendor set. The analysis examines strengths such as specialized diagnostic offerings, touchscreen ergonomics, and digital ecosystems, and highlights where gaps exist for entrants and incumbents alike.
What PW Consulting’s report contains — practical assets for 2026 execution
The report is designed as an operational toolkit for executives, deploying robust methodology and deliverables you can act on immediately. Key components include:
-
Market sizing and near-term forecasts (base year 2025; forecast 2026–2032) with scenario sensitivity to macro and commodity shocks.
-
Competitive benchmarking and capability maps that assess product features (touchscreen size, diagnostics, automation), channel strength, and service ecosystems.
-
Technology and product roadmaps: an innovations matrix that ranks features by adoption risk, implementation complexity, and ROI potential.
-
Supply-chain risk register and mitigation playbook, with stress-tested sourcing scenarios for steel, motors, and electronic subsystems.
-
Commercial playbooks for three buyer segments (high-volume professional shops, independent service centers, and OEMs) that translate market signals into pricing, bundling, and distribution tactics.
-
M&A watchlist and target scoring framework—prioritized using strategic fit, product synergies, and integration risk metrics.
-
Financial models and an ROI calculator to evaluate product investment, channel expansion, and aftersales subscription strategies under multiple market-growth assumptions.
Recent developments and implications
Notable vendor-level activity reinforces the market themes we identify. For example, a recent product launch from a U.S. equipment manufacturer introduced a diagnostic-heavy balancer targeted at high-volume shops, illustrating the competitive premium being placed on embedded diagnostics and workflow efficiency. Such moves underscore the importance of aligning 2026 product roadmaps with shop productivity metrics and software-enabled service monetization.
Strategic recommendations for 2026 (actionable priorities)
-
Prioritize modular architecture: Build touchscreen platforms with modular software and sensor interfaces to accelerate feature rollouts and reduce upgrade friction for customers.
-
Invest in aftermarket economics: Bundle diagnostics, remote support, and consumables to shift revenue toward higher-margin, recurring streams.
-
Hedge component risk: Enter strategic supply agreements for critical electronic modules and steel, and qualify alternate vendors to reduce single-source exposure.
-
Segment GTM by buyer economics: Align pricing and feature sets to the economics of distinct buyer groups—fully automatic platforms for high-throughput shops; semi-automatic, cost-efficient models for independents.
-
Use M&A tactically: Target acquisitions that fill capability gaps (software, connectivity, diagnostics) more often than scale alone; integration speed should be a gating criterion in 2026.
How to use this report in board-level conversations
Bring the report’s scenario models and ROI tool to your next strategic planning session. Use our sensitivity analyses to stress-test capital allocation decisions against commodity price swings and aftermarket adoption curves. For boards considering inorganic growth, the M&A scoring framework converts qualitative fit into quantitative trade-offs, making it easier to evaluate competing bids or divestiture options.
Conclusion — the strategic edge PW Consulting provides
For executives making pivotal 2026 decisions, the balance between speed and selectivity is decisive. PW Consulting’s report translates market scale and growth tempo into executable commercial and product strategies while exposing supply-chain and regulatory hazards that can erode margins if unaddressed. The report is not a replacement for internal analysis; it is a force-multiplier: validated market sizing, competitor insight, and operational playbooks that accelerate confident, defensible choices.
Next steps
Access the full report for detailed company profiles, the complete forecast model, customizable ROI tools, and the supplier risk register that we intentionally summarized here. For executive briefings, customized workshops, or to license our forecast dataset, please visit the official PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Worldwide Wheel Balancer With Touchscreen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Shape Memory Alloys for Civil Engineering Market Poised to Grow at an 8.5% CAGR
By pmarketresearch, 2026-08-12
Worldwide Shape Memory Alloys for Civil Engineering Market — Strategic Intelligence to Guide 2026 Decisions
Executive snapshot
PW Consulting’s latest market study, Worldwide Shape Memory Alloys for Civil Engineering Market (base year 2025), equips infrastructure leaders with the strategic context they need to make disciplined investments in 2026. The global market has expanded from USD 165.2 Million in 2020 to USD 245.5 Million in 2025 (USD, Million) and is forecast to reach approximately USD 434.58 Million by 2032, reflecting a compounded annual growth rate of 8.5% across the 2026–2032 forecast window. These headline figures underscore a sustained, commercially meaningful adoption curve as owners, contractors and technology providers move from laboratory demonstrations to operational deployments across civil infrastructure applications.
RVs Lithium-Ion Energy Storage Batteries Market
Why this matters for 2026 decision‑makers
-
Accelerating retrofit and resilience agendas: Aging asset pools and more stringent resilience requirements make shape memory alloys (SMAs) an increasingly attractive lever for cost-effective strengthening, damping and adaptive elements in bridges, tunnels and building envelopes.
Worldwide Cotton Underwear Market -
Time‑to‑value becomes a competitive vector: SMA-enabled prestressing and thermal activation techniques can materially reduce on‑site labour, shorten outage windows and simplify sequencing for complex interventions — factors that change procurement calculus in 2026.
Worldwide Auxiliary Locks Market -
Material and regulatory dynamics are shaping opportunity windows: Nickel and titanium feedstock volatility is pressuring cost structures for NiTi solutions, while iron‑based SMAs (Fe‑SMA) are gaining traction because they can be produced using conventional metallurgical routes and are better positioned for large-scale civil deployments.
-
Standards and interoperability: Industry standards (including ASTM guidance applicable to SMA evaluation) are maturing, lowering technical risk and creating procurement benchmarks that buyers can use to specify performance and acceptance tests.
What PW Consulting’s report delivers — operational, decision‑ready content
This study is designed as a practitioner’s toolkit. It combines market intelligence with hands‑on instruments that procurement, engineering and strategy teams can deploy immediately:
-
Validated market sizing and a seven‑year forecast model (2026–2032) with scenario functionality so teams can stress‑test plans under alternative adoption and price paths.
-
Adoption curve maps and maturity matrices that show where different SMA technologies sit in the commercialization lifecycle — from early demonstrations to scale‑ready designs.
-
Use‑case ROI templates and decision trees that quantify expected downtime savings, labour reductions and life‑cycle benefits for retrofit, prestressing and damping applications.
-
Procurement playbooks and supplier due‑diligence checklists aligned to ASTM testing regimes and field acceptance protocols.
-
Supply chain heatmaps that identify single‑point material risks, cost drivers (including nickel/titanium exposure) and on‑shore/off‑shore production considerations.
-
Technical annexes translating laboratory measures (actuation temperatures, recovery stress, fatigue performance) into engineering acceptance criteria for design specifications.
-
Commercial model templates for win‑win contracting: EPC+SMA bundles, performance warranties and staged rollouts to de‑risk first‑of‑a‑kind projects.
-
Competitive landscaping with company profiles, capability scoring and partnership playbooks to support supplier selection and co‑development strategies.
Note: The report purposefully reserves granular revenue splits and detailed regional/application tables for subscribers; the “trailer” here highlights depth while directing practitioners to the full report for segment‑level intelligence and downloadable model files.
Competitive landscape — a strategic read on core suppliers
The SMA ecosystem for civil engineering is a mix of specialist innovators, materials manufacturers and component suppliers. Market concentration metrics indicate a horizontally fragmented market with consolidation potential: the top three suppliers account for a meaningful minority share while the top five widen that footprint further, signaling both room for new entrants and opportunity for strategic partnerships.
-
re‑fer AG (Brunnen, Switzerland) — Strengths: Proven iron‑based (Fe‑SMA) memory®‑steel solutions and a portfolio of real‑world civil applications (bridges, masonry repair, prestressing). Tactical implications: Owners seeking low‑temperature, scalable prestressing and retrofit solutions should prioritize pilot partnerships with Fe‑SMA specialists to validate lifecycle economics. Limitations: niche supplier scale compared with large metals manufacturers; co‑development and licensing deals may be required for mass deployment.
-
Ingpuls GmbH (Bochum, Germany) — Strengths: Customizable SMEs and integrated systems covering actuators, sensing and damping; full‑chain capability from specification to assembly. Tactical implications: Systems integrators and façade/MEP contractors should evaluate Ingpuls for turnkey actuator/detection prototypes that couple SMA hardware with building automation. Limitations: Transitioning from component to infrastructure scale requires strategic alliances with civil contractors and precasters.
-
SMA CORES Inc. (Champaign, USA) — Strengths: Focus on thermal prestressing and super‑elastic applications that can shorten construction time. Tactical implications: North American owners with compressed schedules should pilot SMA CORES’ approaches in targeted prestressing tasks to capture schedule and labour efficiencies.
-
SAES Getters S.p.A. (Lainate, Italy) — Strengths: Vertical integration across NiTi production, enabling tight quality control and component supply. Tactical implications: Buyers looking to manage material quality and traceability should engage vertically integrated producers for long‑lead contracts; caveat is NiTi exposure to raw material price swings.
-
Dynalloy Inc. (Irvine, USA) & Memry Corporation (Bethel, USA) — Strengths: Established suppliers of NiTi actuator wires, tubing and components used in actuation/damping niche applications. Tactical implications: These vendors are logical partners for integration into valve/ventilation/shading systems or for embedding sensing and actuation in civil structures where precision actuation is required.
Industry catalysts and near‑term developments
-
Research traction: Swiss researchers in collaboration with Empa demonstrated a heat‑activated Fe‑SMA method for strengthening ageing bridge decks, lowering the barrier to field adoption by validating activation protocols and performance in a civil context.
-
Knowledge consolidation: The Transportation Infrastructure Precast Innovation Center (TRANS‑IPIC) is convening the first International Symposium on Shape Memory Alloys in Infrastructure — a focal event expected to accelerate cross‑discipline knowledge transfer and standardization conversations.
-
Applied innovation: memory®‑steel has been used in digitally fabricated concrete elements (e.g., a staircase application in a research building), signaling that SMA incorporation into modern construction methods is not only possible but practical.
Key risks and regulatory levers
-
Raw material volatility: Nickel and titanium supply chains remain exposed to geopolitical and mining constraints — boards should bake material‑price stress tests into project cost models and consider hedging or long‑term supplier agreements.
-
Standards and acceptance: ASTM and related test methods are increasingly relevant; buyers should define acceptance criteria tied to standardized testing to mitigate performance disputes and to accelerate insurer and regulator confidence.
-
Scale and manufacturability: Fe‑SMA’s compatibility with conventional metallurgical processes offers a scale advantage for large civil elements; however, implementation logistics (activation equipment, thermal control) require operational readiness planning.
Strategic imperatives for 2026
-
Run focused pilot programmes on critical assets with measurable KPIs (downtime reduction, labour hours saved, life‑extension value) and a clear escalation path to portfolio rollout.
-
Design procurement around performance specifications linked to ASTM‑aligned tests rather than prescriptive material clauses — this opens competition while ensuring adequate quality control.
-
Diversify supplier exposure across NiTi and Fe‑SMA producers and build long‑term offtake clauses to manage feedstock pricing risk.
-
Invest in in‑house integration capability — small teams that can translate lab output into construction workflows (activation, monitoring, maintenance) will be a differentiator.
-
Negotiate collaboration agreements with specialty suppliers to secure IP access for scaling, and consider licensing or co‑development for site‑specific solutions.
-
Engage with standards bodies and symposiums to shape acceptance criteria and to accelerate insurer and regulator recognition.
Conclusion — how executives should use this study in 2026
For asset owners, contractors and materials investors, the 8.5% CAGR outlook and the trajectory from USD 245.5 Million (2025) toward mid‑hundreds of millions by 2032 signal the transition from niche experiments to selective mainstreaming. The strategic question for 2026 is not whether SMAs have technical merit, but how organisations will operationalise them: which pilot projects to fund, how to allocate procurement risk, who to partner with, and how to embed acceptance testing into contract packages.
PW Consulting’s report provides the forecast, the tools and the competitive analysis to answer those questions — and it reserves the granular segment and regional tables, along with downloadable financial models and procurement templates, for report subscribers. To access the full dataset, supplier scorecards and decision models that will directly support your 2026 investment and procurement decisions, please visit PW Consulting’s report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide Shape Memory Alloys for Civil Engineering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Niraparib Market Reaches USD 1,180.5 Million in 2025, Poised for a 12.43% CAGR to USD 2,680.5 Million by 2032
By pmarketresearch, 2026-08-12
Worldwide Niraparib Market: Strategic Imperatives for 2026 Decision‑Makers
As oncology portfolios and oncology-adjacent supply chains become defining pillars of biopharma growth strategies, niraparib has emerged from a specialist PARP inhibitor into a multi-indication strategic asset. PW Consulting’s latest Worldwide Niraparib Market report — with 2025 as the base year and a 2026–2032 forecast horizon — shows a market that reached roughly USD 1.18 billion in 2025 and is on track to approximately USD 2.68 billion by 2032, reflecting a compound annual growth rate (CAGR) of 12.43%. For executives preparing 2026 budgets, pipeline prioritization, licensing negotiations, or manufacturing investments, these headline dynamics translate into concrete choices that can materially affect shareholder value and patient access over the coming decade.
Medical Power Strip Market
Executive snapshot: why niraparib matters now
-
From maintenance therapy in ovarian cancer to newly approved prostate cancer combinations, niraparib has crossed from niche oncology drug to a diversified therapeutic platform with multiple commercial pathways.
Off-Grid Solar Lighting Market -
High market concentration around a small number of originator and license-holding firms creates both stability and strategic bottlenecks: a concentrated supplier and commercialization landscape amplifies the impact of regulatory decisions, label updates, and partnership shifts.
Worldwide Digital Manometer Market -
Regulatory and diagnostic advancements in late 2025–early 2026 materially changed the addressable population and payer dialogue — requiring rapid re-assessment of access models and commercial roll‑outs for 2026.
What this means for 2026 planning
-
Prioritize regulatory-readiness and label optimization. Recent label updates and the extension of indications into prostate cancer broaden the clinical use case, but also require updated HCP engagement, new value dossiers, and targeted payer evidence generation during 2026.
-
Refresh companion diagnostic strategies. The approval of an HRD companion diagnostic linked to niraparib use heightens the importance of diagnostic access, sample logistics, and co‑marketing agreements — all levers that influence uptake curves in the first 18 months post-approval.
-
Stress-test supply chains. A market trajectory that doubles within the forecast window increases demand volatility for both API and finished-dose forms. Organizations should model multi‑scenario capacity needs and validate secondary suppliers to mitigate single‑source exposure.
-
Revisit partnership and exclusivity timelines. Patent protection and exclusive licensing footprints remain central strategic constraints; organizations should align M&A, out‑licensing, and geographic expansion timelines to these IP and collaborator windows.
Report deliverables — practical, decision‑ready content
Our report is built as a playbook for commercial, regulatory, and manufacturing leadership. Key operational modules include:
-
Market-sizing and scenario modeling: Transparent methodology, sensitivity analyses, and regional uptake scenarios that map to different reimbursement and diagnostic penetration trajectories.
-
Go‑to‑market playbooks: Segmented launch strategies by stakeholder (oncologists, urologists, payers), channel tactics, and recommended evidence generation plans for label expansions.
-
Competitive intelligence and partner maps: Deep profiles of originators, licensees, and active API/FDF suppliers, with strategic implications for pricing, tendering, and co‑promotion opportunities.
-
Regulatory and HTA tracker: Rolling timeline of approvals, label updates, diagnostic authorizations, and payer coverage decisions that influence near‑term access.
-
Manufacturing and sourcing playbook: API capacity assessments, quality/regulatory audit priorities, and contingency sourcing strategies for rapid scale‑up.
-
M&A and licensing scorecards: Value drivers, downside scenarios, and negotiation playbooks tailored to acquirers, licensors, and regional partners.
Competitive landscape: players, positions, and strategic levers
The competitive field for niraparib is shaped by a mix of originator companies, regional licensees, and specialist API suppliers. The market is highly concentrated among a few leading commercial principals — a dynamic we quantify in the report and that materially raises the strategic value of control over commercialization rights and label breadth.
-
Originator and global commercial steward: The originator remains the primary commercial force behind ZEJULA (niraparib), managing global brand stewardship, lifecycle management, and evidence generation in core indications. Their stewardship dictates global messaging, safety updates, and the timing of major labelling changes.
-
Prostate‑focused collaborator: A major multinational holds exclusive rights (outside certain territories) to advance niraparib combinations in prostate cancer and has successfully brought a dual‑action combination to approval in late 2025. This creates a parallel commercial track that complements ovarian cancer maintenance use and expands prescriber audiences.
-
Regional licensees and partners: Strategic commercialization partners in Greater China and Japan retain critical in-market capabilities and distribution networks — decisions on promotional investments and diagnostic partnerships in these territories will determine near-term market penetration.
-
API and manufacturing base: A set of established API manufacturers and regional suppliers underpin global production. Their capabilities, GMP certifications, and willingness to scale are determining factors in the cost curve and supply resilience during peak demand periods.
Recent developments that alter the playbook
-
Late‑stage regulatory approvals and Priority Review actions in 2025 materially shift the addressable population and accelerate commercialization plans for combination regimens in prostate cancer.
-
Companion diagnostic authorization in early 2026 refocuses market access conversations around biomarker-driven reimbursement and necessitates integrated diagnostic‑drug launch plans.
-
Originator label updates and updated prescribing information (2025) change clinical positioning and risk mitigation communications, which should be reflected in medical affairs roadmaps and safety monitoring strategies.
Risk map for 2026 decisions
-
IP timeline sensitivity: Core composition and formulation patents extend into the late 2030s, shaping generic entry timing and informing licensing valuations. Executives must model multiple scenarios for post‑patent competitive intensity.
-
Diagnostic adoption uncertainty: Uptake of companion diagnostics is uneven by market; slow diagnostic access undermines the projected addressable population and requires bespoke access strategies per market.
-
Supply concentration: With a limited set of qualified API and FDF suppliers, capacity constraints or GMP disruptions could create outsized commercial effects during rapid uptake phases.
-
Payer negotiation pressure: Broader indications and combination regimens increase absolute spend per patient, inviting tougher HTA scrutiny and price negotiation in several major markets.
Actionable recommendations for 2026
-
Align evidence generation with payer windows. Prioritize health economic studies and real‑world evidence protocols that address the most likely HTA objections for combination therapies and biomarker‑selected indications.
-
Fast‑track diagnostic partnerships. Secure preferred diagnostic pathways early (lab network agreements, co‑payment solutions, or companion kit distribution) to reduce friction at launch.
-
Strengthen supplier redundancy. Validate alternate API sources and build staged inventory buffers tied to launch milestones rather than to fixed calendar dates.
-
Negotiate geographic rights with optionality. Structure deals with step‑in rights and performance milestones to protect upside across label expansions and geographic diffusion.
Why PW Consulting’s report matters to you
For 2026, niraparib is both an operational challenge and a strategic growth lever. Our report delivers not only a rigorous market sizing — rooted in transparent assumptions and sensitivity analyses — but also actionable modules that translate forecasts into procurement decisions, clinical trial planning, and commercial timelines. We surface the implications of recent regulatory movements, diagnostic approvals, and label changes, and we map the supplier and partner landscape that will determine who wins the next phase of adoption.
Next steps — where to find the data you need
This article intentionally highlights the strategic breadth of the opportunity without disclosing granular regional or indication splits; the full report contains the detailed segmentation tables, regional uptake curves, pricing scenarios, and supplier scorecards that underpin the headline market trajectory. Senior leaders requiring transaction support, bespoke scenario runs, or onboarding briefings can request tailored appendices and interactive models directly from PW Consulting.
To convert the 2026 market opportunity into commercial advantage, organizations should move quickly to synchronize evidence plans, diagnostic access, and supply assurance. PW Consulting’s Worldwide Niraparib Market report is designed to be the roadmap for that work.
For detailed analysis of this topic, please visit the official page: Worldwide Niraparib Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Fully Automatic Tofu Machine Market to Climb from USD 485.6 Million in 2025 to USD 752.13 Million by 2032, Powered by a 6.45% CAGR
By pmarketresearch, 2026-08-12
Worldwide Fully Automatic Tofu Machine Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
PW Consulting’s latest market study on the Worldwide Fully Automatic Tofu Machine Market delivers a focused, decision-ready perspective for executives shaping 2026 strategy. The market has matured into a multi-hundred‑million-dollar global sector—expanding from roughly USD 355.2 Million in 2020 to an estimated USD 485.6 Million in 2025—and our base-case forecast projects sustained momentum through the 2026–2032 period at a compound annual growth rate (CAGR) of 6.45%. By 2032 the market is modeled to approach USD 752.13 Million under the baseline scenario.
Worldwide Tire Inflators Market
Why this matters for 2026 strategy
- Investment timing: The near-term growth trajectory signals attractive windows for capacity expansion, retrofits, and greenfield projects, but timing matters—cost pressures and technology cycles are compressing payback horizons.
- Product and channel plays: Automation is shifting competitive advantage from basic equipment supply toward integrated, turnkey solutions that shorten time-to-market for manufacturers and retailers alike.
- Risk management: Raw-material volatility and energy costs require operating models that hedge input exposure via procurement strategy and technical investments in energy and water efficiency.
Data-driven market trajectory (what the numbers tell you)
Historic patterns show steady expansion from 2020 through 2025, with CAGR pickup in the most recent years as automation adoption accelerated across food processors, commercial kitchens and retail manufacturing initiatives. Our forecast through 2032 incorporates multiple drivers—demand for plant‑based products, labor substitution via automation, and regulatory harmonization on food safety—that produce a mid-single-digit growth profile (6.45% CAGR) out to the end of the forecast horizon.
Worldwide Embedded Vision Systems Market
For corporate decision‑makers, the implication is clear: the sector’s growth is large enough to justify strategic commitments (R&D, production capacity, and channel development) while remaining tractable—market concentration is moderate, with the three largest vendors controlling roughly one‑third of market value and the top five representing under half, leaving room for regional specialists and differentiated technology providers to win.
Nickel-Metal Hydride Button Cell Market
Key macro and operational dynamics to watch in 2026
- Input-cost inflation: Soybean and commodity inputs have shown meaningful year‑over‑year price movement; procurement and process optimization will determine margin resilience.
- Labor scarcity and automation: Fully automatic systems materially reduce manual touchpoints across soaking, grinding, coagulation and pressing—translating into predictable labor savings and quality consistency that many food processors now treat as table stakes.
- Regulatory alignment and certifications: ISO and CE compliance are increasingly embedded in buyers’ RFPs; vendors who can demonstrate certified hygienic design will access premium channels such as export food manufacturers and large retailers.
- Sustainability and energy efficiency: Advances in high‑efficiency heating, heat recovery and water recycling are shifting total cost of ownership (TCO) equations—making capital investment in energy‑saving modules a high‑priority lever for cost-conscious operators.
Strategic implications by functional agenda
- Senior executives / corporate strategy: Prioritize a dual path of selective capacity expansion in regions where demand acceleration and regulatory access align, plus a targeted M&A scouting effort to acquire niche automation or energy‑savings technologies that shorten innovation cycles.
- Operations and engineering: Re-evaluate retrofit opportunities; modular automation upgrades often deliver faster ROI than full-line replacements in mid‑sized facilities.
- Supply chain & procurement: Shift toward longer-term soybean contracts, blended sourcing strategies, and collaboration with machine vendors for spare-part logistics to reduce downtime risk.
- Commercial and channel leaders: Differentiate through service models—embedded maintenance contracts, remote diagnostics, and ingredient-to-package turnkey solutions increase customer stickiness and open annuity revenue streams.
Competitive landscape — what the market structure means for 2026 moves
The marketplace combines legacy engineering houses, regional manufacturers, and agile mid-size OEMs. Our competitive scan highlights several archetypes that buyers and investors should recognize:
- Heritage engineering champions: Companies with long histories in soy and tofu plant engineering deliver high‑throughput, industry‑grade lines and global turnkey experience—well suited to large processors seeking scale and export capability.
- Certified turnkey specialists: Vendors offering ISO/CE certified European‑style lines and mid‑to‑high capacity dry soybean processing solutions are positioned to win institutional food‑manufacturing contracts and multi-site rollouts.
- Cost‑competitive regional suppliers: Numerous suppliers focus on stainless‑steel, commercial‑grade equipment for local and regional markets, delivering attractive unit economics for SMEs and specialty producers.
- Emerging innovators: A cadre of firms is embedding energy efficiency, modular control systems and digital diagnostics—capabilities that increasingly decide tenders that emphasize TCO over upfront price.
Representative profiles from our company analysis:
- Takai Tofu & Soymilk Equipment Co. (Japan): A century‑scale specialist delivering high‑speed fully automatic lines with large daily pack capacities and a global delivery footprint—an archetypal partner for large industrial processors.
- Yung Soon Lih Food Machine Co., Ltd. (Taiwan): Offers certified turnkey lines and a spectrum of throughputs for dry soybean processing and specialty tofu types; active in trade shows and international marketing to build global OEM relationships.
- China‑based OEMs (representative): Several manufacturers provide integrated machines that combine soaking, grinding, filtering, boiling and pressing into compact footprints—well suited to commercial kitchens, co‑packers and smaller factories.
- Indian suppliers (representative): Firms supplying reliable stainless‑steel machines for regional markets at competitive price‑performance levels are addressing growing domestic demand for processed plant protein products.
Recent industry developments shaping 2026 opportunity
- Major equipment suppliers continue to showcase automation advancements at international trade shows—an indicator that suppliers are investing in product visibility and global distribution.
- Raw‑material price movements and national season‑average forecasts have increased procurement focus among processors; advanced buyers are tying equipment purchase timing to hedged input strategies.
- Regulatory and certification alignment (ISO/CE) remains a gating factor for vendors seeking to participate in cross‑border procurement programs; certification now appears routinely in vendor evaluation matrices.
What our full report provides (practical, actionable content)
The PW Consulting study is structured to equip executives with both strategic context and operational tools. Subscribers will find:
- Market sizing and scenario forecasts (2020–2032) with sensitivity testing across commodity, energy and adoption curves.
- Go‑to‑market playbooks for OEMs, co‑packers and retailers—covering pricing, service models, and channel partnerships.
- Detailed vendor benchmarking and supplier selection matrices—including quality certification status, throughput bands, modularity, and TCO estimates.
- CapEx and OpEx modeling templates that integrate energy, water and labor inputs to support investment appraisal and payback analysis.
- Regulatory and sustainability checklists to streamline international market entry and buyer due‑diligence.
To preserve the report’s commercial value while enabling executive triage, this release intentionally highlights high‑confidence findings and strategic implications; detailed regional splits, application‑level shares and full company financials are distilled in the report itself.
Recommended next steps for 2026
- Run a one‑week internal TCO exercise using our modeling templates to re‑rank near‑term capital projects.
- Prioritize supplier audits that verify hygienic design and energy efficiency claims; certifications should be contractually required for export‑oriented lines.
- Explore pilot partnerships with turnkey vendors that include performance guarantees and remote monitoring—lowering the cost of technology adoption while proving concepts at scale.
- Align procurement timing with commodity hedges to protect margin during machine commissioning and ramp‑up phases.
How to obtain the full market intelligence
This briefing outlines the high‑value, strategic takeaways from PW Consulting’s Worldwide Fully Automatic Tofu Machine Market report and emphasizes the near‑term decisions that will shape competitive positioning in 2026. The full report contains the granular segmentation tables, regional and application breakdowns, extended vendor profiles, and downloadable financial models required to implement the actions recommended here. Access to the complete dataset and appendices is available via PW Consulting’s report distribution channels.
For teams committed to converting 2026 opportunity into measurable advantage, the full report is the operational playbook—containing the confidential tables and scenario outputs that underpin these recommendations. Contact PW Consulting to request the report package and a tailored briefing for your executive team.
For detailed analysis of this topic, please visit the official page: Worldwide Fully Automatic Tofu Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Cell Controller Market to Grow at 8.45% CAGR, Reach USD 1.315 Billion by 2032
By pmarketresearch, 2026-08-12
Worldwide Cell Controller Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
As organizations calibrate strategic plans for 2026, decisions around battery architecture, supplier selection, and safety compliance will increasingly shape competitive advantage. PW Consulting’s latest Worldwide Cell Controller Market research — built on a 2025 base year and a 2026–2032 forecast horizon — translates market dynamics into actionable guidance for OEMs, Tier‑1 suppliers, semiconductor vendors, energy storage developers, and private equity sponsors evaluating the electrified mobility and energy sectors.
Worldwide Solder Mask Market
Why cell controllers matter now — and why 2026 is a hinge year
Cell controllers sit at the interface of electrochemistry and systems engineering. They govern voltage and temperature sensing, cell balancing, fault isolation, and the safety instrumentation necessary to meet automotive and industrial safety standards. Our analysis traces a rapid maturation: the global market expanded from approximately USD 498 million in 2020 to roughly USD 746 million in 2025, a near‑50% increase over five years. Looking forward, the market is set to accelerate under a structural mix of EV adoption, stationary storage deployments, higher cell counts per pack, and rising functional‑safety expectations — a compound annual growth rate of 8.45% across the 2026–2032 forecast window, with the market crossing the USD 1.3 billion threshold by 2032.
Talc Ceramic Sleeve Market
For executives planning 2026 roadmaps, this is not a distant technical nuance: choices made this year about chip architectures, communication stacks, and supplier partnerships will determine cost curves, certification timelines, and time‑to‑market for next‑generation battery systems.
Data Center Virtualization Service Market
What the report delivers — pragmatic intelligence for decision makers
- Forward‑looking market sizing and scenario‑based forecasts calibrated to 2025 baseline metrics and stress‑tested across alternate EV and ESS adoption paths.
- A regulatory and standards playbook that aligns product roadmaps to ISO 26262, ISO 12405 series guidance, and functional‑safety testing regimes relevant to automotive and industrial deployments.
- Technology maps that decode cell controller architectures (isolated daisy‑chain communications, transformer physical layers, per‑cell ADC strategies, and telemetry/security overlays) and translate them into modular design patterns for hardware and software teams.
- Commercial frameworks: supplier scorecards, TCO models that combine silicon, BOM, and software/service monetization, and sourcing strategies for dual‑sourcing and qualification acceleration.
- Competitive intelligence dossiers and M&A playbooks: comparative vendor heat maps, capability cluster analysis, and diligence checklists for bolt‑on acquisitions or strategic partnerships.
- Implementation checklists and test bench templates (including virtualization and hardware‑in‑the‑loop scenarios) that cut validation cycles and reduce field recall risk.
We intentionally keep headline data public while reserving granular breakouts, vendor revenue shares, and region/application splits for the full report — because those details function as executional playbooks for clients.
Market structure and competitive dynamics: concentrated, but open to disruption
The cell controller market today exhibits moderate concentration. The top three vendors account for just over 40% of global share, and the top five approach roughly 59% — a structure that creates both stability and opportunity. Incumbent semiconductor giants command design wins with robust functional‑safety features and broad ecosystem support, yet mid‑tier specialists and software‑centric firms are carving differentiated positions around virtualization, service layers, and domain‑specific integrations.
Strategically, this concentration implies two viable client pathways in 2026:
- For OEMs and Tier‑1s: standardize around established silicon partners to shorten certification cycles, while maintaining an innovation sandbox with specialist vendors to mitigate supplier risk and capture value from differentiated features.
- For investors and new entrants: target software and test‑infrastructure assets that can scale across chipset vendors — these assets deliver high margin expansion and act as gateway technologies into broader BMS revenue pools.
Vendor spotlights — what to watch in 2026
Our competitive analysis spotlights several firms that exemplify distinct strategic postures in the cell controller value chain:
- NXP Semiconductors (Eindhoven) : NXP continues to expand its portfolio with high‑channel count ICs and functional‑safety credentials tailored for HVBMS and ESS. A notable milestone in mid‑2025 was a new family of 18‑channel cell controller ICs incorporating per‑channel ADCs, pin‑compatibility across variants, and hardware safety signaling designed to meet ASIL‑C (automotive) and SIL‑2 (industrial) requirements. For adopters, NXP’s value lies in integrated safety features, proven automotive qualification pathways, and broad ecosystem support; for partners, its platform provides a stable foundation but can carry premium pricing and qualification lock‑in risks.
- Texas Instruments (Dallas) : TI plays to its analog and system‑level strengths with cell monitor and balance ICs that facilitate rapid pack-level integration and manufacturing scale. Expect TI to push software toolchains and reference designs that reduce OEM integration effort — attractive for high‑volume industrial customers eyeing reduced time‑to‑certification.
- Analog Devices (Wilmington) : Analog Devices emphasizes precision measurement and isolation technologies, positioning its devices for high‑voltage, high‑accuracy applications (such as aerospace and premium EV segments). Its strategic advantage will be in markets where measurement fidelity links directly to system efficiency and warranty risk reduction.
- dSPACE (Paderborn) : As testing and virtualization become decisive, dSPACE’s cell controller virtualization (CCV) offerings enable manufacturers to validate BMS strategies across multi‑vendor controllers in software‑centric workflows. This lowers development cost and accelerates validation against functional‑safety requirements — an increasingly vital capability as cell counts and software complexity rise.
Together these vendors illustrate the market’s dual thrust: silicon‑led reliability and software/virtualization‑led speed to market. The interplay between these vectors will define winners in 2026 and beyond.
Regulatory and technical guardrails shaping strategy
Regulatory expectations are converging on demonstrable functional safety and rigorous diagnostics. ISO 26262 remains the de facto safety framework for automotive applications, and the ISO 12405 family explicitly references cell electronics and controller requirements for electrically propelled vehicles. Practically, this means suppliers and integrators must embed diagnostic coverage, redundant sensing, and fail‑safe communication layers early in product development.
From a systems architecture perspective, isolated daisy‑chain communication and transformer‑based physical layers are becoming standard approaches to manage reliability across long strings of cells. These choices have implications for connector design, EMC planning, and serviceability strategies. Firms that align their roadmaps to these technical guardrails — and demonstrate shortened verification cycles — will capture disproportionate share of design wins in 2026.
Actionable playbook for 2026 decision‑makers
- Prioritize platform‑level compatibility: Select cell controllers and companion software that are modular, support isolated daisy‑chain topologies, and provide clear migration paths across safety levels. This reduces rework as pack architectures evolve.
- Dual‑track certification: Run parallel paths: a low‑risk track that leverages proven silicon for near‑term models and an innovation track that pilots newer architectures in limited production runs.
- Invest in virtualization: Adopt CCV and HIL frameworks to compress validation timelines. Our fieldwork shows virtualization can cut late‑stage integration issues by over 30% in complex pack programs.
- Balance CapEx and OpEx via software services: Given the growth trajectory, software and services tied to cell controllers (analytics, OTA updates, health prognostics) are high‑leverage monetization channels that also improve pack lifecycle economics.
- Make procurement decisions with concentration in mind: The market’s top vendors control significant share; however, targeted partnerships with specialists can yield differentiated features without wholesale vendor lock‑in.
Closing — the strategic value of granular intelligence
2026 will be a decisive year for companies positioning themselves in the electrification value chain. The cell controller market is no longer a purely technical consideration; it is a strategic lever that influences safety certification timelines, product cost curves, and after‑sales economics. PW Consulting’s Worldwide Cell Controller Market report combines market sizing anchored to a 2025 baseline, an 8.45% CAGR forecast across 2026–2032, and pragmatic playbooks to turn those forecasts into executable strategies.
For executives and investment teams preparing 2026 plans, the report provides the granular intelligence needed to align product roadmaps, prioritize vendor engagements, and identify acquisition targets — while the reserved detailed segment tables and vendor revenue breakdowns serve as the tactical playbook available exclusively in the full report.
To access the comprehensive datasets, scenario models, vendor dossiers, and implementation templates referenced here, please visit the PW Consulting report page and request the full Worldwide Cell Controller Market brief.
For detailed analysis of this topic, please visit the official page: Worldwide Cell Controller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com