

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Hydrochar Market Set to Climb from USD 285.5 Million in 2025 to USD 505.37 Million by 2032, Forecasting 8.5% CAGR

Worldwide Hydrochar Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
PW Consulting’s latest market study—anchored on 2025 as the base year and projecting through 2032—distills the strategic intelligence energy, waste and agriculture executives need to make decisive moves in 2026. The hydrochar market has shifted from niche technology to a commercial-scale value pool: global revenue rose from approximately USD 195 million in 2020 to USD 285 million in 2025, and our model now forecasts a trajectory to just over USD 505 million by 2032 at a compound annual growth rate (CAGR) of 8.5% (USD, revenue unit: Million). This report is designed as an operational playbook for boardrooms and deal teams—providing the analytical scaffolding required to convert emerging policy and feedstock advantages into sustainable competitive advantage.
Industrial Tilting Devices Market
Why 2026 is a Pivotal Year
-
Policy inflection points translate into commercial windows. Recent regulatory updates across major markets are tightening organic waste streams and creating clearer pathways for hydrothermal carbonization (HTC) outputs to access incentives designed for low‑carbon fuels and soil amendments. These policy drivers collapse uncertainty that had previously slowed capital deployment.
Worldwide Car Sensors Market -
Feedstock dynamics are converging with technology maturation. Availability of wet biomass residues and municipal biowaste at industrial scales is enabling project bankability in ways not present five years ago—meaning that feasibility studies completed today can be shovel‑ready within typical project development timelines.
Worldwide Chlortetracycline Market -
Investor appetite for carbon‑removal adjacent solutions has increased materially. Hydrochar’s dual role as a fuel substitute and durable carbon product accelerates its appeal to corporates seeking both scope‑reduction and carbon‑storage pathways.
Market Dynamics and Strategic Implications
-
Feedstock supply and logistics determine project economics. While the available tonnages of wet biomass are large, localized collection efficiency, seasonality, pre‑processing costs, and competing valorization routes (anaerobic digestion, composting) create winner‑takes‑most corridors for early movers who integrate supply chains.
-
Technology choice matters for market positioning. HTC variants and competing thermochemical routes diverge on capital intensity, yield, and product specs (energy density, ash content). Strategic buyers must stress‑test vendor claims against independent yield assumptions and downstream handling costs.
-
Market concentration remains low. The sector is populated with specialist technology providers and vertically integrated operators; the top players collectively occupy less than one‑third of the market today—indicating both fragmentation and opportunity for consolidation over the forecast period.
-
Policy‑linked revenue mechanisms are a double‑edged sword. Carbon credit streams and co‑firing incentives materially improve returns but introduce policy risk. Scenario planning across policy outcomes should be embedded in all capital allocation decisions.
Competitive Landscape: Who’s Deploying at Scale and What It Signals
Our fieldwork and primary interviews confirm a cohort of technology and project developers that are setting commercial benchmarks. PW Consulting’s competitive assessment evaluates these firms on technology maturity, feedstock flexibility, route‑to‑market, and financing models.
-
Ingelia (Barcelona, Spain) — Focused on HTC plants that convert sewage sludge and other biowaste into hydrochar for fertilizer and fuel applications. Their recent commercial plant start in Italy demonstrates a move from pilot to repeatable commercial installations, signaling a template for municipal partnerships.
-
TerraNova Energy GmbH (Münster, Germany) — Developer of the HTCycle platform with pipeline commitments for industrial‑scale plants. Partnerships announced for sizeable plants indicate a business model leaning on strategic alliances with waste aggregators and municipal authorities.
-
BlackCarbon GmbH (St. Pölten, Austria) — Produces premium hydrochar from lignocellulosic feedstocks aimed at industrial boiler replacement. Their recent capacity expansion speaks to demand from heavy industry seeking rapid coal substitution pathways.
-
Arbaflame A/S (Aarhus, Denmark) — Builds pelletized hydrochar for co‑firing in power plants. Their positioning illustrates the near‑term commercial opportunity in the power generation sector where co‑firing standards are clear.
-
Haffner Energy (Vitry‑le‑François, France) — Operator of the ERC process producing SynChar; certification of pilot plants shows intent to capture both energy and carbon sequestration use cases.
-
Antaco (Santiago, Chile) — Regional player converting forestry residues and sludge into marketable hydrochar, underscoring geographic diversification and the ability to tap forestry value chains in South America.
Taken together, these players illustrate two convergent strategies: (1) vertically integrated operators that control feedstock and offtake, and (2) technology licensors and OEMs seeking high‑margin equipment and licensing revenue. Investors should evaluate which model aligns to their time horizon—asset‑heavy, lower‑risk cash flows versus asset‑light IP plays with scalability upside.
Regulation, Science and the Value Equation
-
Regulatory tailwinds: Recent updates—such as stricter separate collection rules and clearer ETS treatment for co‑fired hydrochar—are reducing policy ambiguity in key markets and accelerating offtake negotiations for projects that can demonstrate lifecycle emissions reductions.
-
Performance metrics: Independent literature shows hydrochar can deliver high carbon yields from wet biomass and substantial energy densification, making it competitive as both a fuel substitute and a soil amendment—though specifications vary by feedstock and process conditions.
-
Feedstock scale: Large volumes of wet biomass residues are technically available in several regions, but economic capture of these volumes requires logistics integration, contract standardization, and often co‑investment with municipal or agricultural stakeholders.
What PW Consulting’s Report Delivers (Practical Tools for 2026 Actions)
This research is constructed to be operational. Highlights of the deliverables include:
-
A calibrated market model from 2020–2032 with base‑year (2025) reconciliation and scenario variants that stress policy, feedstock cost, and yield assumptions—built for sensitivity testing by CFOs and strategists.
-
Technology comparison matrix and vendor scorecards—benchmarks for CAPEX/OPEX, yields, and product specs to inform procurement and partner selection.
-
Supply‑chain maps and contract templates—practical tools for securing feedstock volumes and structuring offtake agreements, including recommended KPIs and pricing collars.
-
Regulatory impact matrix—translated into quantifiable P&L levers for project financial models and permitting timelines by jurisdiction.
-
M&A and JV playbook—target screens, valuation heuristics, and due diligence checklists tailored to hydrochar assets and technology providers.
-
Commercial go‑to‑market playbooks for utilities, waste companies and industrial end‑users—detailing pilot design, scale‑up milestones, and stakeholder engagement templates.
Actionable Recommendations by Stakeholder
-
Corporate investors and strategics: Lock in feedstock supply through long‑dated contracts or upstream equity, and prioritize technologies with independent yield validation. Layer policy scenarios into valuation—don’t rely on a single incentive mechanism to validate returns.
-
Waste managers and municipalities: Evaluate HTC partnerships as part of an integrated waste‑valorization portfolio. Use demonstrations to validate seasonal collection models and offtake aggregations before committing to full‑scale plants.
-
Utility and power producers: Fast‑track co‑firing pilots where permitting and fuel handling are clearly defined, and use hydrochar as a transitional lever to reduce coal exposure while assessing feedstock price volatility.
-
Equipment manufacturers and EPCs: Standardize modular designs to reduce project timelines and bill‑of‑materials costs; aftermarket service contracts will be an important recurring revenue stream.
-
Policy makers: Harmonize quality standards for hydrochar products and create transparent carbon accounting rules to lower market entry barriers and foster investment.
Methodology and the “Trailer” Principle
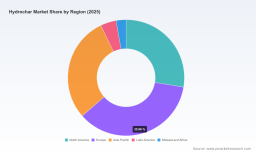
PW Consulting’s analysis synthesizes proprietary interviews, plant‑level performance data, vendor disclosures and third‑party literature. The report provides granular spreadsheets and project‑level cashflow models for subscribers. In line with our “trailer” approach, this press release communicates high‑confidence directional findings and strategic recommendations, while detailed segmental splits, regional breakdowns, and proprietary unit‑cost tables are reserved for the full report accessible via our website.
Next Steps for Decision Makers
If 2026 is when your organization moves from study to execution, the right inputs today can determine who captures value tomorrow. PW Consulting’s Worldwide Hydrochar Market report is engineered to shorten the learning curve, de‑risk capital allocation, and identify the most promising corridors for roll‑out and consolidation. For teams preparing investment memos, RFPs, or regulatory filings this year, the models, vendor scorecards and contract templates in the full report will be indispensable.
To explore the full dataset, segmental forecasts and our proprietary project models, visit the PW Consulting report page or contact our hydrochar practice for a briefing and tailored scenario analysis.
For detailed analysis of this topic, please visit the official page: Worldwide Hydrochar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com