

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Cell Controller Market to Grow at 8.45% CAGR, Reach USD 1.315 Billion by 2032

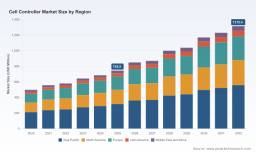
Worldwide Cell Controller Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
As organizations calibrate strategic plans for 2026, decisions around battery architecture, supplier selection, and safety compliance will increasingly shape competitive advantage. PW Consulting’s latest Worldwide Cell Controller Market research — built on a 2025 base year and a 2026–2032 forecast horizon — translates market dynamics into actionable guidance for OEMs, Tier‑1 suppliers, semiconductor vendors, energy storage developers, and private equity sponsors evaluating the electrified mobility and energy sectors.
Worldwide Solder Mask Market
Why cell controllers matter now — and why 2026 is a hinge year
Cell controllers sit at the interface of electrochemistry and systems engineering. They govern voltage and temperature sensing, cell balancing, fault isolation, and the safety instrumentation necessary to meet automotive and industrial safety standards. Our analysis traces a rapid maturation: the global market expanded from approximately USD 498 million in 2020 to roughly USD 746 million in 2025, a near‑50% increase over five years. Looking forward, the market is set to accelerate under a structural mix of EV adoption, stationary storage deployments, higher cell counts per pack, and rising functional‑safety expectations — a compound annual growth rate of 8.45% across the 2026–2032 forecast window, with the market crossing the USD 1.3 billion threshold by 2032.
Talc Ceramic Sleeve Market
For executives planning 2026 roadmaps, this is not a distant technical nuance: choices made this year about chip architectures, communication stacks, and supplier partnerships will determine cost curves, certification timelines, and time‑to‑market for next‑generation battery systems.
Data Center Virtualization Service Market
What the report delivers — pragmatic intelligence for decision makers
- Forward‑looking market sizing and scenario‑based forecasts calibrated to 2025 baseline metrics and stress‑tested across alternate EV and ESS adoption paths.
- A regulatory and standards playbook that aligns product roadmaps to ISO 26262, ISO 12405 series guidance, and functional‑safety testing regimes relevant to automotive and industrial deployments.
- Technology maps that decode cell controller architectures (isolated daisy‑chain communications, transformer physical layers, per‑cell ADC strategies, and telemetry/security overlays) and translate them into modular design patterns for hardware and software teams.
- Commercial frameworks: supplier scorecards, TCO models that combine silicon, BOM, and software/service monetization, and sourcing strategies for dual‑sourcing and qualification acceleration.
- Competitive intelligence dossiers and M&A playbooks: comparative vendor heat maps, capability cluster analysis, and diligence checklists for bolt‑on acquisitions or strategic partnerships.
- Implementation checklists and test bench templates (including virtualization and hardware‑in‑the‑loop scenarios) that cut validation cycles and reduce field recall risk.
We intentionally keep headline data public while reserving granular breakouts, vendor revenue shares, and region/application splits for the full report — because those details function as executional playbooks for clients.
Market structure and competitive dynamics: concentrated, but open to disruption
The cell controller market today exhibits moderate concentration. The top three vendors account for just over 40% of global share, and the top five approach roughly 59% — a structure that creates both stability and opportunity. Incumbent semiconductor giants command design wins with robust functional‑safety features and broad ecosystem support, yet mid‑tier specialists and software‑centric firms are carving differentiated positions around virtualization, service layers, and domain‑specific integrations.
Strategically, this concentration implies two viable client pathways in 2026:
- For OEMs and Tier‑1s: standardize around established silicon partners to shorten certification cycles, while maintaining an innovation sandbox with specialist vendors to mitigate supplier risk and capture value from differentiated features.
- For investors and new entrants: target software and test‑infrastructure assets that can scale across chipset vendors — these assets deliver high margin expansion and act as gateway technologies into broader BMS revenue pools.
Vendor spotlights — what to watch in 2026
Our competitive analysis spotlights several firms that exemplify distinct strategic postures in the cell controller value chain:
- NXP Semiconductors (Eindhoven) : NXP continues to expand its portfolio with high‑channel count ICs and functional‑safety credentials tailored for HVBMS and ESS. A notable milestone in mid‑2025 was a new family of 18‑channel cell controller ICs incorporating per‑channel ADCs, pin‑compatibility across variants, and hardware safety signaling designed to meet ASIL‑C (automotive) and SIL‑2 (industrial) requirements. For adopters, NXP’s value lies in integrated safety features, proven automotive qualification pathways, and broad ecosystem support; for partners, its platform provides a stable foundation but can carry premium pricing and qualification lock‑in risks.
- Texas Instruments (Dallas) : TI plays to its analog and system‑level strengths with cell monitor and balance ICs that facilitate rapid pack-level integration and manufacturing scale. Expect TI to push software toolchains and reference designs that reduce OEM integration effort — attractive for high‑volume industrial customers eyeing reduced time‑to‑certification.
- Analog Devices (Wilmington) : Analog Devices emphasizes precision measurement and isolation technologies, positioning its devices for high‑voltage, high‑accuracy applications (such as aerospace and premium EV segments). Its strategic advantage will be in markets where measurement fidelity links directly to system efficiency and warranty risk reduction.
- dSPACE (Paderborn) : As testing and virtualization become decisive, dSPACE’s cell controller virtualization (CCV) offerings enable manufacturers to validate BMS strategies across multi‑vendor controllers in software‑centric workflows. This lowers development cost and accelerates validation against functional‑safety requirements — an increasingly vital capability as cell counts and software complexity rise.
Together these vendors illustrate the market’s dual thrust: silicon‑led reliability and software/virtualization‑led speed to market. The interplay between these vectors will define winners in 2026 and beyond.
Regulatory and technical guardrails shaping strategy
Regulatory expectations are converging on demonstrable functional safety and rigorous diagnostics. ISO 26262 remains the de facto safety framework for automotive applications, and the ISO 12405 family explicitly references cell electronics and controller requirements for electrically propelled vehicles. Practically, this means suppliers and integrators must embed diagnostic coverage, redundant sensing, and fail‑safe communication layers early in product development.
From a systems architecture perspective, isolated daisy‑chain communication and transformer‑based physical layers are becoming standard approaches to manage reliability across long strings of cells. These choices have implications for connector design, EMC planning, and serviceability strategies. Firms that align their roadmaps to these technical guardrails — and demonstrate shortened verification cycles — will capture disproportionate share of design wins in 2026.
Actionable playbook for 2026 decision‑makers
- Prioritize platform‑level compatibility: Select cell controllers and companion software that are modular, support isolated daisy‑chain topologies, and provide clear migration paths across safety levels. This reduces rework as pack architectures evolve.
- Dual‑track certification: Run parallel paths: a low‑risk track that leverages proven silicon for near‑term models and an innovation track that pilots newer architectures in limited production runs.
- Invest in virtualization: Adopt CCV and HIL frameworks to compress validation timelines. Our fieldwork shows virtualization can cut late‑stage integration issues by over 30% in complex pack programs.
- Balance CapEx and OpEx via software services: Given the growth trajectory, software and services tied to cell controllers (analytics, OTA updates, health prognostics) are high‑leverage monetization channels that also improve pack lifecycle economics.
- Make procurement decisions with concentration in mind: The market’s top vendors control significant share; however, targeted partnerships with specialists can yield differentiated features without wholesale vendor lock‑in.
Closing — the strategic value of granular intelligence
2026 will be a decisive year for companies positioning themselves in the electrification value chain. The cell controller market is no longer a purely technical consideration; it is a strategic lever that influences safety certification timelines, product cost curves, and after‑sales economics. PW Consulting’s Worldwide Cell Controller Market report combines market sizing anchored to a 2025 baseline, an 8.45% CAGR forecast across 2026–2032, and pragmatic playbooks to turn those forecasts into executable strategies.
For executives and investment teams preparing 2026 plans, the report provides the granular intelligence needed to align product roadmaps, prioritize vendor engagements, and identify acquisition targets — while the reserved detailed segment tables and vendor revenue breakdowns serve as the tactical playbook available exclusively in the full report.
To access the comprehensive datasets, scenario models, vendor dossiers, and implementation templates referenced here, please visit the PW Consulting report page and request the full Worldwide Cell Controller Market brief.
For detailed analysis of this topic, please visit the official page: Worldwide Cell Controller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com