

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Wheel Balancer With Touchscreen Market Hits USD 391.0 Million in 2025, Poised for Further Growth

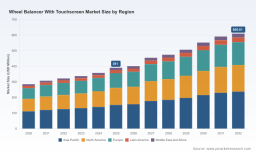
Worldwide Wheel Balancer With Touchscreen Market — Strategic Outlook for 2026: Why C-Suites and Product Leaders Need PW Consulting’s New Report
Executive summary
PW Consulting’s latest market research report on the Worldwide Wheel Balancer With Touchscreen Market (base year 2025, historical 2020–2025, forecast 2026–2032) delivers a pragmatic, decision-focused view for executives planning capital allocation, product roadmaps, and M&A activity in 2026. Our analysis finds the market at a clear inflection point: after robust recovery through 2020–2025, the installed-base upgrade cycle and rising demand for digitally enabled shop equipment will sustain growth through the forecast period at a compounded annual growth rate (CAGR) of approximately 6.55%.
Worldwide Thermal Conductive Sheet Market
Why this matters for 2026 strategy
-
Market momentum entering 2026 supports confident investment but requires selective prioritization. With the global market size measured at the 2025 base year and modeled through 2032, players must choose between competing near-term returns and long-term platform plays (connectivity, diagnostics, and automation).
Worldwide Flotation Cell Market -
Touchscreen-enabled balancing equipment has migrated from “nice-to-have” to a productivity and diagnostic hub in professional workshops. Decisions in product development, channel incentives, and aftermarket service investments in 2026 will determine who captures the high-value upgrade cycle.
Digital Pathology Image Analysis Software for Clinical Market -
Supply-chain and material considerations—particularly steel and electronic components—introduce cost and lead-time variability that will affect 2026 procurement strategies and pricing policies.
Market trajectory and sizing: what the numbers mean
Our bottom-up model synthesizes equipment shipments, replacement cycles, average selling prices, and aftermarket demand to project the market through 2032. The 2025 market midpoint is a practical decision benchmark: it quantifies the absolute scale of opportunity while the 6.55% CAGR provides the growth tempo buyers and investors should expect. Together these metrics help stretch internal business cases beyond anecdote to a defensible financial plan for 2026 investments — whether funding an R&D sprint, expanding distribution, or underwriting a tuck-in acquisition.
Key market dynamics shaping 2026 choices
-
Technology convergence: Touchscreen interfaces have become table stakes; value differentiation now comes from embedded diagnostics, 3D imaging, laser-guided workflows, and seamless connectivity with dealer/shop management systems. OEMs and independent manufacturers are converging on platform-level features that increase workshop throughput and service ticket depth.
-
Automation spectrum: The market is bifurcated between high-throughput fully automatic systems and flexible semi-automatic solutions. Each segment maps to distinct buyer economics — from large multi-bay tire shops and vehicle manufacturers to smaller independent service centers — and therefore requires different go-to-market plays.
-
Raw material and component exposure: Steel, sensors, motors, and electronic subsystems are core inputs. Our sector analysis indicates procurement volatility and concentrated component supply chains; contract manufacturers and OEMs should embed scenario-based sourcing strategies into 2026 operating plans.
-
Regulatory and sustainability pressures: Environmental rules are accelerating the shift to recyclable weighting materials. Zinc-based balancing weights are gaining share because of recyclability, despite carrying a price premium versus legacy alternatives — a factor that intersects with product positioning and customer education requirements for 2026.
-
Aftermarket expansion: Rising vehicle parc and ongoing aftermarket demand are durable tailwinds. However, the revenue mix is evolving: sales of diagnostic-capable balancers, recurring software subscriptions, and service contracts are becoming material contributors to lifetime value.
Competitive landscape — patterns, not playbooks
The vendor ecosystem is populated by long-established workshop-equipment manufacturers and fast-moving innovators. Our qualitative and quantitative assessment highlights three practical takeaways for 2026 planning:
-
Differentiation through integration: Firms that package touchscreen hardware with advanced diagnostic suites and automated workflows create stickier customer relationships. Leaders are layering features such as laser weight placement, 3D/2D imaging, and guided user interfaces to reduce service time and up-sell consumables and diagnostics.
-
Margin pressure and premiumization: Vendors targeting high-volume professional shops are investing in direct drive architectures and diagnostic-capable models to justify premium pricing. Conversely, semi-automatic, cost-efficient platforms remain essential to capture smaller service centers where capital budgets are constrained.
-
Service and channel economics: Companies that strengthen dealer training, remote diagnostic support, and spare parts logistics gain a competitive edge. Aftermarket service contracts are fast becoming a principal lever to improve gross margins and customer retention.
Our competitor profiles evaluate product portfolios, go-to-market footprints, and innovation cadence across the vendor set. The analysis examines strengths such as specialized diagnostic offerings, touchscreen ergonomics, and digital ecosystems, and highlights where gaps exist for entrants and incumbents alike.
What PW Consulting’s report contains — practical assets for 2026 execution
The report is designed as an operational toolkit for executives, deploying robust methodology and deliverables you can act on immediately. Key components include:
-
Market sizing and near-term forecasts (base year 2025; forecast 2026–2032) with scenario sensitivity to macro and commodity shocks.
-
Competitive benchmarking and capability maps that assess product features (touchscreen size, diagnostics, automation), channel strength, and service ecosystems.
-
Technology and product roadmaps: an innovations matrix that ranks features by adoption risk, implementation complexity, and ROI potential.
-
Supply-chain risk register and mitigation playbook, with stress-tested sourcing scenarios for steel, motors, and electronic subsystems.
-
Commercial playbooks for three buyer segments (high-volume professional shops, independent service centers, and OEMs) that translate market signals into pricing, bundling, and distribution tactics.
-
M&A watchlist and target scoring framework—prioritized using strategic fit, product synergies, and integration risk metrics.
-
Financial models and an ROI calculator to evaluate product investment, channel expansion, and aftersales subscription strategies under multiple market-growth assumptions.
Recent developments and implications
Notable vendor-level activity reinforces the market themes we identify. For example, a recent product launch from a U.S. equipment manufacturer introduced a diagnostic-heavy balancer targeted at high-volume shops, illustrating the competitive premium being placed on embedded diagnostics and workflow efficiency. Such moves underscore the importance of aligning 2026 product roadmaps with shop productivity metrics and software-enabled service monetization.
Strategic recommendations for 2026 (actionable priorities)
-
Prioritize modular architecture: Build touchscreen platforms with modular software and sensor interfaces to accelerate feature rollouts and reduce upgrade friction for customers.
-
Invest in aftermarket economics: Bundle diagnostics, remote support, and consumables to shift revenue toward higher-margin, recurring streams.
-
Hedge component risk: Enter strategic supply agreements for critical electronic modules and steel, and qualify alternate vendors to reduce single-source exposure.
-
Segment GTM by buyer economics: Align pricing and feature sets to the economics of distinct buyer groups—fully automatic platforms for high-throughput shops; semi-automatic, cost-efficient models for independents.
-
Use M&A tactically: Target acquisitions that fill capability gaps (software, connectivity, diagnostics) more often than scale alone; integration speed should be a gating criterion in 2026.
How to use this report in board-level conversations
Bring the report’s scenario models and ROI tool to your next strategic planning session. Use our sensitivity analyses to stress-test capital allocation decisions against commodity price swings and aftermarket adoption curves. For boards considering inorganic growth, the M&A scoring framework converts qualitative fit into quantitative trade-offs, making it easier to evaluate competing bids or divestiture options.
Conclusion — the strategic edge PW Consulting provides
For executives making pivotal 2026 decisions, the balance between speed and selectivity is decisive. PW Consulting’s report translates market scale and growth tempo into executable commercial and product strategies while exposing supply-chain and regulatory hazards that can erode margins if unaddressed. The report is not a replacement for internal analysis; it is a force-multiplier: validated market sizing, competitor insight, and operational playbooks that accelerate confident, defensible choices.
Next steps
Access the full report for detailed company profiles, the complete forecast model, customizable ROI tools, and the supplier risk register that we intentionally summarized here. For executive briefings, customized workshops, or to license our forecast dataset, please visit the official PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Worldwide Wheel Balancer With Touchscreen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com