

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 4.52% CAGR for Worldwide Pigment-Grade Titanium Dioxide Market Through 2032

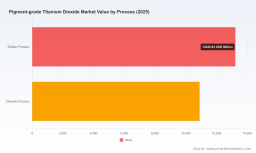
Worldwide Pigment-grade Titanium Dioxide Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s newest industry briefing, “Worldwide Pigment-grade Titanium Dioxide Market,” provides a concise, forward-looking synthesis intended to sharpen executive decision-making as companies plan for 2026. Drawing on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study places the pigment-grade TiO2 market in a tight, policy- and cost-driven context. In short: after a recovery from pandemic-era volatility the market reached USD 24,157.8 Million in 2025 and is projected to grow at a steady 4.52% CAGR through the forecast window, with an anticipated market scale exceeding USD 32.9 Billion by 2032.
Workstation Power Supply Market
Why this report matters for 2026 strategy
-
Timing: 2026 will be a hinge year where the interaction of regulatory tightening, raw material stress, and investment cycles will determine who can compete effectively in both price-sensitive and premium coatings segments.
Niti Memory Alloy Stent Market -
Risk Visibility: Several structural risks—feedstock price volatility, energy cost inflation tied to decarbonization, and trade-policy frictions—will meaningfully re-shape procurement, supply chain design, and pricing power in 2026. Our briefing quantifies these forces and models downside scenarios to inform contingency planning.
SAW Grade Lithium Niobate Thin Film Market -
Competitive Leverage: The market shows moderate concentration (CR3 ~38.5%; CR5 ~52.1%), implying that mid-tier players can still capture niches if they align investments with emerging technical and regulatory requirements. The report identifies those niches and the capabilities needed to exploit them.
What decision-makers will find in the briefing
The report is structured to be immediately operational for leadership teams preparing 2026 plans. Key deliverables include:
-
Market sizing and trend diagnostics — an audited baseline (2020–2025), a 2026 opening-position, and scenario-driven projections to 2032 that stress-test growth against raw material and regulatory shocks.
-
Segment playbooks — practical guidance on choosing process and product pathways (chloride vs. sulfate processes; rutile vs. anatase formulations), with decision trees that map capital intensity, feedstock exposure and downstream value capture without revealing confidential subsegment datapoints in this summary.
-
Price and cost analytics — an independent assessment of the primary cost drivers, including ilmenite and synthetic feedstock dynamics, energy surcharges, and processing differentials. The briefing includes sensitivity matrices that translate commodity moves into margin impacts for typical cost structures.
-
Supply-chain resilience templates — supplier scorecards, inventory strategy variants (JIT, buffer-stock, multi-sourcing), and trade-risk playbooks that factor in tariffs, force majeure scenarios and logistics bottlenecks.
-
Regulatory & ESG roadmap — compliance checklists for key markets, implications of recent EU and Chinese measures, and an emissions-control investment calculator that quantifies payback periods on energy-efficiency and decarbonization upgrades.
-
Competitive and M&A radar — benchmarking tools that position incumbents and challengers on capacity, process mix, and product focus to help identify attractive acquisition or partnership targets.
Market dynamics shaping 2026 decisions
Several converging forces make 2026 a defining year:
-
Feedstock pressure. Ilmenite prices rose materially into late 2024, reflecting supply tightness from major sources. This has direct pass-through potential for producers and will be a top-line risk for buyers planning procurement contracts in 2026.
-
Production footprint rationalization. Chinese regulatory moves to eliminate older sulfate-process capacity have realigned global supply chains. That structural rebalancing amplifies the strategic value of flexible capacity and of investments that shift production toward lower-emission chloride routes where feasible.
-
Trade policy frictions. Remaining tariffs in the US and other trade measures continue to alter regional sourcing economics. Procurement teams must factor tariff scenarios into 2026 supplier selection and near-shore vs. global sourcing trade-offs.
-
Energy and decarbonization costs. Electricity and carbon-control measures have pushed production surcharges higher in some markets; energy-efficiency upgrades and alternative energy contracts will therefore be central to cost competitiveness for plants running in 2026 and beyond.
-
Regulatory compliance complexity. Changes to REACH and other chemical import regimes have tightened the requirements for certain nano-forms and high-performance grades, necessitating updated compliance strategies and potential reformulation roadmaps.
Competitive landscape: key players and strategic takeaways
The briefing includes executive profiles and strategy implications for the major manufacturing and specialty players. Highlights for executives preparing 2026 action plans:
-
The Chemours Company — continues to leverage brand and formulation innovation (notably new water‑based optimized grades) to sustain premium positioning in coatings. Strategy implication: prioritize R&D collaborations with downstream formulators to secure specification lock-in in waterborne systems.
-
Tronox Holdings — is expanding capacity in select geographies, reinforcing its chloride-process play. Strategy implication: evaluate partnerships or offtake arrangements to ensure access to chloride-route product as demand for higher-performance rutile grades rises.
-
Lomon Billions Group — with broad global pricing influence, recent price increases underscore the pass-through levers large integrated producers possess. Strategy implication: buyers and smaller competitors should model supplier price-shock scenarios and explore hedging or longer-term contracts.
-
CNNC Hua Yuan & other Chinese producers — the interplay of force majeure events and regional capacity adjustments highlights the need for multi-regional supply strategies. Strategy implication: diversify supplier base and maintain dual-sourcing where tariffs and local restrictions create single-supplier risk.
-
Regional specialists (e.g., ISK, Tayca, Precheza) — retain advantages in high-end automotive and specialty applications where product performance trumps raw-material cost. Strategy implication: target premium niches with differentiated product claims and certification support.
Recent industry developments — implications for 2026
-
Price adjustments and input-cost inflation (notably energy and ilmenite) indicate that contract structures signed in 2025 could be re-opened or contested in 2026. Procurement teams must build flexible indexation clauses and dispute-resolution paths into supply agreements.
-
Capacity expansion projects completed in 2024–2025 materially alter regional availability in certain grades and routes; firms must map their exposure to those facilities and stress-test their commercial forecasts against accelerated ramp-ups or delayed startups.
-
Regulatory enforcement in major markets creates certification and label risks for non-compliant grades — requiring immediate investment in testing, traceability, and documentation workflows if companies intend to maintain market access in 2026.
How PW Consulting supports execution
Beyond the printed analysis, PW Consulting’s deliverables are designed for immediate use in 2026 planning cycles:
-
Customizable Excel models: interactive topline and margin scenarios, supplier-stress simulators, and investment appraisal templates.
-
Board-ready slide decks: concise diagnostics and recommended strategic moves for procurement, operations, and corporate development teams.
-
Supplier risk matrices and RFP templates: to accelerate re-sourcing and to introduce contractual protections against price, capacity and regulatory shocks.
-
Regulatory compliance playbooks and emissions investment calculators: to quantify both compliance costs and potential operational savings from energy modernization.
What we are not releasing publicly (and why)
In keeping with the “trailer” approach to this briefing, we are intentionally withholding the granular subsegment tables, full regional and application splits, and the detailed company-level revenue bridges from this summary. Those data elements are central to transactional decisions and M&A valuation work, and they are available in the full report package and accompanying data license. The summary above outlines the strategic contours and actionable insights needed to decide whether to procure the full dataset for 2026 planning.
Recommended 90‑day actions for 2026 preparedness
-
Initiate a rapid supplier-exposure audit focused on feedstock origin, process type (chloride vs. sulfate) and tariff risk to identify single points of failure.
-
Stress-test product margins under ±20% ilmenite and ±15% electricity-cost scenarios and create contingency pricing playbooks for customer contracts.
-
Accelerate compliance and testing programs for EU and key export markets to avoid market-access interruptions tied to recent regulatory updates.
-
Evaluate strategic partnership opportunities with chloride-route capacity owners or specialty players to secure access to high-margin grades.
Next steps
For procurement, operations, R&D and corporate development leaders planning 2026 moves, PW Consulting’s full “Worldwide Pigment-grade Titanium Dioxide Market” report provides the data tables, scenario models and supplier dossiers needed to convert strategic options into executable plans. For a sample executive summary, licensing options, or to arrange a briefing with our lead analysts, please contact PW Consulting via our official channels. The complete dataset and interactive models are available to licensed subscribers and advisory clients.
PW Consulting — equipping leaders with the market intelligence needed to make high-consequence, time-sensitive decisions in the evolving pigment-grade titanium dioxide landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Pigment-grade Titanium Dioxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com