

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Shape Memory Alloys for Civil Engineering Market Poised to Grow at an 8.5% CAGR

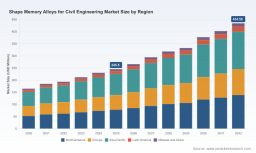
Worldwide Shape Memory Alloys for Civil Engineering Market — Strategic Intelligence to Guide 2026 Decisions
Executive snapshot
PW Consulting’s latest market study, Worldwide Shape Memory Alloys for Civil Engineering Market (base year 2025), equips infrastructure leaders with the strategic context they need to make disciplined investments in 2026. The global market has expanded from USD 165.2 Million in 2020 to USD 245.5 Million in 2025 (USD, Million) and is forecast to reach approximately USD 434.58 Million by 2032, reflecting a compounded annual growth rate of 8.5% across the 2026–2032 forecast window. These headline figures underscore a sustained, commercially meaningful adoption curve as owners, contractors and technology providers move from laboratory demonstrations to operational deployments across civil infrastructure applications.
RVs Lithium-Ion Energy Storage Batteries Market
Why this matters for 2026 decision‑makers
-
Accelerating retrofit and resilience agendas: Aging asset pools and more stringent resilience requirements make shape memory alloys (SMAs) an increasingly attractive lever for cost-effective strengthening, damping and adaptive elements in bridges, tunnels and building envelopes.
Worldwide Cotton Underwear Market -
Time‑to‑value becomes a competitive vector: SMA-enabled prestressing and thermal activation techniques can materially reduce on‑site labour, shorten outage windows and simplify sequencing for complex interventions — factors that change procurement calculus in 2026.
Worldwide Auxiliary Locks Market -
Material and regulatory dynamics are shaping opportunity windows: Nickel and titanium feedstock volatility is pressuring cost structures for NiTi solutions, while iron‑based SMAs (Fe‑SMA) are gaining traction because they can be produced using conventional metallurgical routes and are better positioned for large-scale civil deployments.
-
Standards and interoperability: Industry standards (including ASTM guidance applicable to SMA evaluation) are maturing, lowering technical risk and creating procurement benchmarks that buyers can use to specify performance and acceptance tests.
What PW Consulting’s report delivers — operational, decision‑ready content
This study is designed as a practitioner’s toolkit. It combines market intelligence with hands‑on instruments that procurement, engineering and strategy teams can deploy immediately:
-
Validated market sizing and a seven‑year forecast model (2026–2032) with scenario functionality so teams can stress‑test plans under alternative adoption and price paths.
-
Adoption curve maps and maturity matrices that show where different SMA technologies sit in the commercialization lifecycle — from early demonstrations to scale‑ready designs.
-
Use‑case ROI templates and decision trees that quantify expected downtime savings, labour reductions and life‑cycle benefits for retrofit, prestressing and damping applications.
-
Procurement playbooks and supplier due‑diligence checklists aligned to ASTM testing regimes and field acceptance protocols.
-
Supply chain heatmaps that identify single‑point material risks, cost drivers (including nickel/titanium exposure) and on‑shore/off‑shore production considerations.
-
Technical annexes translating laboratory measures (actuation temperatures, recovery stress, fatigue performance) into engineering acceptance criteria for design specifications.
-
Commercial model templates for win‑win contracting: EPC+SMA bundles, performance warranties and staged rollouts to de‑risk first‑of‑a‑kind projects.
-
Competitive landscaping with company profiles, capability scoring and partnership playbooks to support supplier selection and co‑development strategies.
Note: The report purposefully reserves granular revenue splits and detailed regional/application tables for subscribers; the “trailer” here highlights depth while directing practitioners to the full report for segment‑level intelligence and downloadable model files.
Competitive landscape — a strategic read on core suppliers
The SMA ecosystem for civil engineering is a mix of specialist innovators, materials manufacturers and component suppliers. Market concentration metrics indicate a horizontally fragmented market with consolidation potential: the top three suppliers account for a meaningful minority share while the top five widen that footprint further, signaling both room for new entrants and opportunity for strategic partnerships.
-
re‑fer AG (Brunnen, Switzerland) — Strengths: Proven iron‑based (Fe‑SMA) memory®‑steel solutions and a portfolio of real‑world civil applications (bridges, masonry repair, prestressing). Tactical implications: Owners seeking low‑temperature, scalable prestressing and retrofit solutions should prioritize pilot partnerships with Fe‑SMA specialists to validate lifecycle economics. Limitations: niche supplier scale compared with large metals manufacturers; co‑development and licensing deals may be required for mass deployment.
-
Ingpuls GmbH (Bochum, Germany) — Strengths: Customizable SMEs and integrated systems covering actuators, sensing and damping; full‑chain capability from specification to assembly. Tactical implications: Systems integrators and façade/MEP contractors should evaluate Ingpuls for turnkey actuator/detection prototypes that couple SMA hardware with building automation. Limitations: Transitioning from component to infrastructure scale requires strategic alliances with civil contractors and precasters.
-
SMA CORES Inc. (Champaign, USA) — Strengths: Focus on thermal prestressing and super‑elastic applications that can shorten construction time. Tactical implications: North American owners with compressed schedules should pilot SMA CORES’ approaches in targeted prestressing tasks to capture schedule and labour efficiencies.
-
SAES Getters S.p.A. (Lainate, Italy) — Strengths: Vertical integration across NiTi production, enabling tight quality control and component supply. Tactical implications: Buyers looking to manage material quality and traceability should engage vertically integrated producers for long‑lead contracts; caveat is NiTi exposure to raw material price swings.
-
Dynalloy Inc. (Irvine, USA) & Memry Corporation (Bethel, USA) — Strengths: Established suppliers of NiTi actuator wires, tubing and components used in actuation/damping niche applications. Tactical implications: These vendors are logical partners for integration into valve/ventilation/shading systems or for embedding sensing and actuation in civil structures where precision actuation is required.
Industry catalysts and near‑term developments
-
Research traction: Swiss researchers in collaboration with Empa demonstrated a heat‑activated Fe‑SMA method for strengthening ageing bridge decks, lowering the barrier to field adoption by validating activation protocols and performance in a civil context.
-
Knowledge consolidation: The Transportation Infrastructure Precast Innovation Center (TRANS‑IPIC) is convening the first International Symposium on Shape Memory Alloys in Infrastructure — a focal event expected to accelerate cross‑discipline knowledge transfer and standardization conversations.
-
Applied innovation: memory®‑steel has been used in digitally fabricated concrete elements (e.g., a staircase application in a research building), signaling that SMA incorporation into modern construction methods is not only possible but practical.
Key risks and regulatory levers
-
Raw material volatility: Nickel and titanium supply chains remain exposed to geopolitical and mining constraints — boards should bake material‑price stress tests into project cost models and consider hedging or long‑term supplier agreements.
-
Standards and acceptance: ASTM and related test methods are increasingly relevant; buyers should define acceptance criteria tied to standardized testing to mitigate performance disputes and to accelerate insurer and regulator confidence.
-
Scale and manufacturability: Fe‑SMA’s compatibility with conventional metallurgical processes offers a scale advantage for large civil elements; however, implementation logistics (activation equipment, thermal control) require operational readiness planning.
Strategic imperatives for 2026
-
Run focused pilot programmes on critical assets with measurable KPIs (downtime reduction, labour hours saved, life‑extension value) and a clear escalation path to portfolio rollout.
-
Design procurement around performance specifications linked to ASTM‑aligned tests rather than prescriptive material clauses — this opens competition while ensuring adequate quality control.
-
Diversify supplier exposure across NiTi and Fe‑SMA producers and build long‑term offtake clauses to manage feedstock pricing risk.
-
Invest in in‑house integration capability — small teams that can translate lab output into construction workflows (activation, monitoring, maintenance) will be a differentiator.
-
Negotiate collaboration agreements with specialty suppliers to secure IP access for scaling, and consider licensing or co‑development for site‑specific solutions.
-
Engage with standards bodies and symposiums to shape acceptance criteria and to accelerate insurer and regulator recognition.
Conclusion — how executives should use this study in 2026
For asset owners, contractors and materials investors, the 8.5% CAGR outlook and the trajectory from USD 245.5 Million (2025) toward mid‑hundreds of millions by 2032 signal the transition from niche experiments to selective mainstreaming. The strategic question for 2026 is not whether SMAs have technical merit, but how organisations will operationalise them: which pilot projects to fund, how to allocate procurement risk, who to partner with, and how to embed acceptance testing into contract packages.
PW Consulting’s report provides the forecast, the tools and the competitive analysis to answer those questions — and it reserves the granular segment and regional tables, along with downloadable financial models and procurement templates, for report subscribers. To access the full dataset, supplier scorecards and decision models that will directly support your 2026 investment and procurement decisions, please visit PW Consulting’s report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide Shape Memory Alloys for Civil Engineering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com