

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Niraparib Market Reaches USD 1,180.5 Million in 2025, Poised for a 12.43% CAGR to USD 2,680.5 Million by 2032

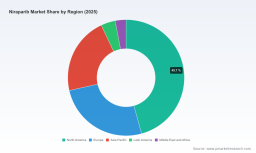
Worldwide Niraparib Market: Strategic Imperatives for 2026 Decision‑Makers
As oncology portfolios and oncology-adjacent supply chains become defining pillars of biopharma growth strategies, niraparib has emerged from a specialist PARP inhibitor into a multi-indication strategic asset. PW Consulting’s latest Worldwide Niraparib Market report — with 2025 as the base year and a 2026–2032 forecast horizon — shows a market that reached roughly USD 1.18 billion in 2025 and is on track to approximately USD 2.68 billion by 2032, reflecting a compound annual growth rate (CAGR) of 12.43%. For executives preparing 2026 budgets, pipeline prioritization, licensing negotiations, or manufacturing investments, these headline dynamics translate into concrete choices that can materially affect shareholder value and patient access over the coming decade.
Medical Power Strip Market
Executive snapshot: why niraparib matters now
-
From maintenance therapy in ovarian cancer to newly approved prostate cancer combinations, niraparib has crossed from niche oncology drug to a diversified therapeutic platform with multiple commercial pathways.
Off-Grid Solar Lighting Market -
High market concentration around a small number of originator and license-holding firms creates both stability and strategic bottlenecks: a concentrated supplier and commercialization landscape amplifies the impact of regulatory decisions, label updates, and partnership shifts.
Worldwide Digital Manometer Market -
Regulatory and diagnostic advancements in late 2025–early 2026 materially changed the addressable population and payer dialogue — requiring rapid re-assessment of access models and commercial roll‑outs for 2026.
What this means for 2026 planning
-
Prioritize regulatory-readiness and label optimization. Recent label updates and the extension of indications into prostate cancer broaden the clinical use case, but also require updated HCP engagement, new value dossiers, and targeted payer evidence generation during 2026.
-
Refresh companion diagnostic strategies. The approval of an HRD companion diagnostic linked to niraparib use heightens the importance of diagnostic access, sample logistics, and co‑marketing agreements — all levers that influence uptake curves in the first 18 months post-approval.
-
Stress-test supply chains. A market trajectory that doubles within the forecast window increases demand volatility for both API and finished-dose forms. Organizations should model multi‑scenario capacity needs and validate secondary suppliers to mitigate single‑source exposure.
-
Revisit partnership and exclusivity timelines. Patent protection and exclusive licensing footprints remain central strategic constraints; organizations should align M&A, out‑licensing, and geographic expansion timelines to these IP and collaborator windows.
Report deliverables — practical, decision‑ready content
Our report is built as a playbook for commercial, regulatory, and manufacturing leadership. Key operational modules include:
-
Market-sizing and scenario modeling: Transparent methodology, sensitivity analyses, and regional uptake scenarios that map to different reimbursement and diagnostic penetration trajectories.
-
Go‑to‑market playbooks: Segmented launch strategies by stakeholder (oncologists, urologists, payers), channel tactics, and recommended evidence generation plans for label expansions.
-
Competitive intelligence and partner maps: Deep profiles of originators, licensees, and active API/FDF suppliers, with strategic implications for pricing, tendering, and co‑promotion opportunities.
-
Regulatory and HTA tracker: Rolling timeline of approvals, label updates, diagnostic authorizations, and payer coverage decisions that influence near‑term access.
-
Manufacturing and sourcing playbook: API capacity assessments, quality/regulatory audit priorities, and contingency sourcing strategies for rapid scale‑up.
-
M&A and licensing scorecards: Value drivers, downside scenarios, and negotiation playbooks tailored to acquirers, licensors, and regional partners.
Competitive landscape: players, positions, and strategic levers
The competitive field for niraparib is shaped by a mix of originator companies, regional licensees, and specialist API suppliers. The market is highly concentrated among a few leading commercial principals — a dynamic we quantify in the report and that materially raises the strategic value of control over commercialization rights and label breadth.
-
Originator and global commercial steward: The originator remains the primary commercial force behind ZEJULA (niraparib), managing global brand stewardship, lifecycle management, and evidence generation in core indications. Their stewardship dictates global messaging, safety updates, and the timing of major labelling changes.
-
Prostate‑focused collaborator: A major multinational holds exclusive rights (outside certain territories) to advance niraparib combinations in prostate cancer and has successfully brought a dual‑action combination to approval in late 2025. This creates a parallel commercial track that complements ovarian cancer maintenance use and expands prescriber audiences.
-
Regional licensees and partners: Strategic commercialization partners in Greater China and Japan retain critical in-market capabilities and distribution networks — decisions on promotional investments and diagnostic partnerships in these territories will determine near-term market penetration.
-
API and manufacturing base: A set of established API manufacturers and regional suppliers underpin global production. Their capabilities, GMP certifications, and willingness to scale are determining factors in the cost curve and supply resilience during peak demand periods.
Recent developments that alter the playbook
-
Late‑stage regulatory approvals and Priority Review actions in 2025 materially shift the addressable population and accelerate commercialization plans for combination regimens in prostate cancer.
-
Companion diagnostic authorization in early 2026 refocuses market access conversations around biomarker-driven reimbursement and necessitates integrated diagnostic‑drug launch plans.
-
Originator label updates and updated prescribing information (2025) change clinical positioning and risk mitigation communications, which should be reflected in medical affairs roadmaps and safety monitoring strategies.
Risk map for 2026 decisions
-
IP timeline sensitivity: Core composition and formulation patents extend into the late 2030s, shaping generic entry timing and informing licensing valuations. Executives must model multiple scenarios for post‑patent competitive intensity.
-
Diagnostic adoption uncertainty: Uptake of companion diagnostics is uneven by market; slow diagnostic access undermines the projected addressable population and requires bespoke access strategies per market.
-
Supply concentration: With a limited set of qualified API and FDF suppliers, capacity constraints or GMP disruptions could create outsized commercial effects during rapid uptake phases.
-
Payer negotiation pressure: Broader indications and combination regimens increase absolute spend per patient, inviting tougher HTA scrutiny and price negotiation in several major markets.
Actionable recommendations for 2026
-
Align evidence generation with payer windows. Prioritize health economic studies and real‑world evidence protocols that address the most likely HTA objections for combination therapies and biomarker‑selected indications.
-
Fast‑track diagnostic partnerships. Secure preferred diagnostic pathways early (lab network agreements, co‑payment solutions, or companion kit distribution) to reduce friction at launch.
-
Strengthen supplier redundancy. Validate alternate API sources and build staged inventory buffers tied to launch milestones rather than to fixed calendar dates.
-
Negotiate geographic rights with optionality. Structure deals with step‑in rights and performance milestones to protect upside across label expansions and geographic diffusion.
Why PW Consulting’s report matters to you
For 2026, niraparib is both an operational challenge and a strategic growth lever. Our report delivers not only a rigorous market sizing — rooted in transparent assumptions and sensitivity analyses — but also actionable modules that translate forecasts into procurement decisions, clinical trial planning, and commercial timelines. We surface the implications of recent regulatory movements, diagnostic approvals, and label changes, and we map the supplier and partner landscape that will determine who wins the next phase of adoption.
Next steps — where to find the data you need
This article intentionally highlights the strategic breadth of the opportunity without disclosing granular regional or indication splits; the full report contains the detailed segmentation tables, regional uptake curves, pricing scenarios, and supplier scorecards that underpin the headline market trajectory. Senior leaders requiring transaction support, bespoke scenario runs, or onboarding briefings can request tailored appendices and interactive models directly from PW Consulting.
To convert the 2026 market opportunity into commercial advantage, organizations should move quickly to synchronize evidence plans, diagnostic access, and supply assurance. PW Consulting’s Worldwide Niraparib Market report is designed to be the roadmap for that work.
For detailed analysis of this topic, please visit the official page: Worldwide Niraparib Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com