

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Copper Hollow Conductors Market Poised to Reach USD 403.9 Million by 2032

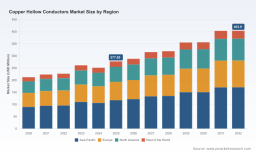
Worldwide Copper Hollow Conductors Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market intelligence on the Worldwide Copper Hollow Conductors market distills five years of historical performance, an actionable 2026–2032 forecast horizon, and a set of practical tools designed to shape boardroom decisions in 2026. This brief provides a high‑signal orientation for executives — highlighting market momentum, supply‑chain pressure points, competitive dynamics, and high‑payoff strategic moves — while preserving the granular segmentation and financial models for our full report and interactive dashboards.
Worldwide Smart Home Displays Market
Market trajectory at a glance
Using 2025 as the analytical base year, the market has demonstrated steady expansion through the historical window and is projected to maintain mid-single‑digit growth across the seven‑year forecast period. Key macro metrics from our model: the market has grown from the low‑hundreds (USD Million) in 2020 to an expanded base in 2025, and our scenario-anchored forecast projects continued growth through 2032 at a compound annual growth rate of approximately 5.49%. PW Consulting’s topline and scenario tables (expressed in USD Million) are included in the full report and permit roll‑forward analyses under alternative copper price and demand scenarios.
Worldwide Lithium-Ion Battery ICs Market
What’s driving the market in 2026
-
Electrification and heavy current applications: Rising deployment of infrastructure and industrial systems that require high‑performance water‑cooled conductors continues to sustain demand for hollow copper shapes designed for low-loss, high‑current density environments.
Video Security SoC Market -
Medical and scientific capital equipment: Investment cycles in MRI systems and high‑energy physics facilities keep premium, specification‑driven hollow conductors in stable demand, favoring suppliers who can deliver strict tolerances and traceable metallurgy.
-
Industrial heating and specialty manufacturing: Induction heating and process furnaces remain reliable pockets of demand for custom profiles and internally cooled channels, creating value for producers with flexible tooling platforms.
-
Price and supply‑side volatility: Commodity copper price swings — which reached record highs in early 2026 before moderating — and evolving midstream economics (including unusually low treatment and refining charges in recent quarters) are reshaping cost structures across the value chain and pressuring margins for downstream fabricators.
Supply‑side dynamics and risk vectors
-
Raw material volatility: The copper price environment entered 2026 with exceptional volatility, driven by accelerated electrification demand and cyclical manufacturing dynamics. Short‑term price spikes and divergent market forecasts from major banks underline the need for active procurement strategies and dynamic pass‑through pricing clauses in supply contracts.
-
Midstream margin compression: Despite price spikes at the metal level, treatment and refining charges for smelters recently hit multi‑year lows — an unusual combination that tightens the window for margin recovery across the midstream and amplifies execution risk for producers without disciplined cost control.
-
Concentration and bargaining power: The market exhibits a moderate level of supplier concentration — three players account for a meaningful share of production capacity and the top five further increase that share. This concentration creates structural advantages for leading producers around scale, specialized tooling, and customer relationships, but also leaves space for regional specialists and low‑cost manufacturers to compete on speed and customization.
-
Regulatory and sustainability pressures: Tighter environmental standards and buyer expectations on traceability (from ore to conductor) are raising compliance costs and favoring manufacturers with robust sustainability roadmaps and digital traceability systems.
Competitive landscape — capabilities that matter in 2026
Across global manufacturers, several recurring capability patterns determine competitive advantage: precision tooling for complex cross‑sections, capacity for internally cooled channels, rapid prototyping and short lead times, alloy expertise (including oxygen‑free and high‑conductivity grades), and geographically diversified production footprints to serve capital equipment OEMs and utilities.
-
Luvata (Pori, Finland) — Recognized for highly configurable tooling and a deep focus on high‑magnetic‑field applications. Their product breadth and short lead time model make them a preferred partner for MRI and laboratory magnet customers where specification and delivery reliability are non‑negotiable.
-
KME (Germany) — A multi‑plant European player with integrated capability across bars, profiles and hollow conductors. Recent R&D outputs demonstrate an institutional commitment to digitalization of the copper value chain, which can lower lead times and improve traceability.
-
Proterial Metals (Japan) — Legacy metallurgy and manufacturing competence with a focus on tough‑pitch copper grades and applications in large‑scale generators and high‑energy physics, where material performance under extreme conditions is critical.
-
cunova and regional specialists — Firms that combine modern machinery and process control with localized customer service are increasingly effective at winning industrial and regional OEM business.
-
Fabmann , Oriental Copper , Extube , S&W Wire Co. , and Channel Metal — These companies each play to specific strengths: complex profile machining, extrusion/drawing quality, ultra‑high conductivity grades, seamless tubing for water‑cooling, and customized microwave or magnet solutions. Buyers commonly select suppliers from this cohort when the priority is either price competitiveness or a narrowly defined technical capability.
Recent corporate actions underscore these capability bets: KME’s BMBF‑backed project on production chain data collection and Luvata’s product positioning for demanding induction furnace applications both reflect the industry’s twin focus on digital traceability and application‑specific productization.
What PW Consulting’s report delivers (practical, executable content)
-
Verified market sizing and forward scenarios (USD Million) with sensitivity to copper price, demand shock, and policy shifts — ready to insert into investor models and procurement playbooks.
-
Competitive benchmarking and supplier scorecards that map technical capability, capacity, lead time, and sustainability credentials — enabling rapid short‑lists for sourcing and strategic partnerships.
-
Cost‑to‑serve and margin decomposition templates that quantify the impact of copper price swings, TC/RC variations, and regional labor/energy differentials on unit economics.
-
Commercial diligence modules and an M&A playbook for acquirers that includes pro forma valuation ranges, integration red flags, and synergies specific to hollow conductor manufacturing.
-
Go‑to‑market and product roadmap recommendations for suppliers seeking to move up the value chain (e.g., internal cooling, high‑precision MRI coils, EV stator cooling solutions), plus regulatory and sustainability checklists for compliant scale‑up.
-
Interactive dashboards and raw data appendices (2020–2025 historicals; 2026–2032 forecasts) that preserve confidentiality around granular splits while enabling client‑side drilldowns under NDA.
Strategic imperatives for 2026
-
Procurement: Implement dynamic hedging and strategically diversified sourcing. Given commodity volatility and midstream margin pressure, procurement teams should combine rolling hedges, fixed‑price components, and volume‑tiered contracts to stabilize unit costs.
-
Product strategy: Prioritize development of internally cooled profiles and tailored alloys that address emerging needs in electrified infrastructure and high‑field medical equipment — these features command premium pricing and improve customer stickiness.
-
Operations and footprint: Reassess capacity allocation against regional demand clusters and logistic cost curves. For capital planners, modest near‑term capacity expansion in lower‑cost jurisdictions plus selective automation of finishing operations delivers the best risk‑adjusted returns.
-
M&A and partnerships: Target bolt‑on acquisitions that add tooling depth, rapid prototyping capabilities, or regional distribution channels rather than broad horizontal scale plays. Strategic alliances with foundries and precision machining houses can create differentiated integrated offers.
-
Sustainability and traceability: Invest in digital traceability and supplier auditing now; buyers increasingly require chain‑of‑custody data and emissions disclosures. Early investment reduces tender friction and unlocks premium contracts with OEMs in medical and scientific segments.
Immediate next steps for executives
-
Request PW Consulting’s full dataset and model pack (2020–2032) to run bespoke scenarios against your cost base and product mix. The summary here is deliberately non‑exhaustive to preserve competitive value — the full report contains the granular inputs and downloadable spreadsheets used in our models.
-
Commission a rapid supplier audit focused on delivery reliability, tooling flexibility, and alloy traceability — ideally delivered as a two‑week diagnostic that produces a prioritized action plan.
-
For investors and M&A teams: engage our commercial diligence team for a targeted valuation and integration risk assessment aligned with the current price volatility and projected demand paths through 2032.
PW Consulting’s Worldwide Copper Hollow Conductors Market report is built to be immediately operational for procurement, product, and corporate strategy teams preparing for 2026. To access the full analysis, interactive visualizations, and the confidential segmentation tables that underpin our recommendations, please visit our report page or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Worldwide Copper Hollow Conductors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com