

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Worldwide Agricultural Automated Steering System Market Poised for 12.85% CAGR in 2026–2032 Forecast
By pmarketresearch, 2026-08-18
Worldwide Agricultural Automated Steering System Market: Strategic Insights for 2026 Decision-Making
PW Consulting’s latest market study on the Worldwide Agricultural Automated Steering System market provides a compact but rigorous briefing designed to inform executive decisions in 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, the report synthesizes market sizing, technology trajectories, vendor positioning, and practical go-to-market playbooks. At the macro level the market demonstrates sustained expansion — growing from approximately USD 855 million in 2020 to roughly USD 1,652 million in 2025, and our modeled outlook projects an increase to about USD 3,851 million by 2032, representing a compound annual growth rate of 12.85% over the forecast period. This trajectory is accompanied by a moderately concentrated supplier base: the top three vendors account for roughly 54.3% of share and the top five for roughly 71.9% — a profile that creates both competitive barriers and consolidation opportunities.
Worldwide Asphalt Anti Strip Agent Market
Why this report matters for 2026 strategists
- Actionable, revenue-linked insight: The study does more than chart growth — it quantifies where value pools are forming and translates those pools into executable pathways for OEMs, Tier‑1 suppliers, distributors, and capital allocators.
- Operational levers prioritized: Cost-of-ownership dynamics, retrofit vs. factory-installed economics, and service-network imperatives are modeled to highlight near-term margin and adoption levers.
- Risk-aware scenario planning: Multiple adoption scenarios reflect sensitivity to regulatory shifts, RTK availability, and commodity-price-driven CAPEX cycles so organizations can stress‑test investment timelines.
What the report contains — practical, useable modules
- Market sizing and methodology: A transparent approach linking historical adoption (2020–2025) to 2026–2032 forecasts, with assumptions on technology substitution, price deflation curves, and service revenue potential.
- Demand-driver diagnostic: Farm economics, operator shortages, precision-agriculture adoption rates, and mechanization trends are modeled to show which farm segments will drive incremental purchases.
- Technology deep dives: Comparative analysis of GNSS/RTK, vision-based, and laser guidance approaches — covering technical performance, cost bands, integration complexity, and terrain/operation suitability.
- Go-to-market playbooks: Practical pathways for OEMs and retrofit suppliers covering channel selection, bundling strategies, financing and subscription models, and dealer enablement templates.
- Commercial models and ROI tools: Build-your-own calculators and sensitivity matrices demonstrating payback timelines under different crop values, operation intensities, and accuracy levels.
- Regulatory and standards radar: Assessment of current and emerging regulatory dynamics that affect operations, spectrum/GNSS policy exposure, and safety/ liability considerations for autonomation features.
- Competitive positioning: Scorecards, partner-fit matrices, and capability maps for leading vendors — enabling immediate benchmarking and M&A screening.
- Implementation playbooks: Field-trial design, fleet‑scale roll-out sequencing, training curricula for dealers and operators, and service logistics optimization.
Competitive landscape: Who matters and why
The market is anchored by a combination of large global OEMs and specialist technology providers. Our assessment identifies a mix of vertically integrated manufacturers and adaptable tech suppliers — each with distinct routes to market and competitive strengths.
Worldwide Activated Alumina Sorbent Market
- John Deere (Moline, Illinois) — A vertically integrated leader offering an OEM-level automated steering platform that emphasizes systems integration, display ecosystems, and proprietary GNSS augmentation. Its value lies in deep OEM integration and dealer network reach.
- Trimble Agriculture (PTx Trimble) (Westminster, Colorado) — A technology-first supplier whose Autopilot platform supports hydraulic and motor-drive configurations and broad OEM and retrofit compatibility, making it a frequent partner for both OEMs and aftermarket players.
- CNH Industrial (Case IH / New Holland) (UK) — Combines factory-installed guidance with retrofit options, balancing brand-led customer trust with cross‑brand technology adoption through their AFS and IntelliSteer lines.
- AGCO (including Fendt) (Duluth, Georgia) — Focused on integrating guidance into its brand portfolio while leveraging partnerships and compatibility with major technology platforms to deliver precision guidance at scale.
- Topcon Agriculture (Livermore, California) — A specialist in guidance systems known for making autosteering more accessible to mid-market tractors; recent product activity demonstrates a deliberate push to expand the addressable retrofit and mid-range segments.
- CHCNAV (Shanghai) — A fast-moving entrant that emphasizes RTK-level accuracy and multi‑GNSS support, offering competitive pricing and rapid global expansion from a China base.
- Ag Leader Technology (Ames, Iowa) — A focused player delivering integrated steering systems with an emphasis on compatibility with precision displays and year‑round machine control.
- FJDynamics (Shenzhen) — A provider concentrating on RTK-level performance and terrain compensation, targeting broad compatibility for tractors and specialized agricultural machinery.
- Raven Industries (CNH affiliate), CLAAS, Kubota — Each brings unique strengths: Raven with precision-control systems, CLAAS with OEM integration in harvesting platforms, and Kubota with scale in certain geographic and mechanization segments.
Collectively, these profiles make clear that competitive advantage will increasingly derive from combination offers — hardware + connectivity + services — and from channel depth rather than hardware differentiation alone.
Online Transformerless UPS Market
Recent industry dynamics shaping 2026 choices
- Product activity in 2025 shows vendors moving to broaden access: for example, new “value line” autosteering solutions target mid-range tractors and smaller farms, lowering the entry threshold for precision guidance.
- High-accuracy systems with RTK-level performance are now widely available from multiple vendors, increasing competitive pressure on price and pushing differentiation toward service, UX, and integration.
- Adoption snapshots indicate meaningful penetration in midsize and large farms — a structural tailwind that translates into a steady replacement and retrofit market, especially where operator shortages and efficiency pressures are acute.
- Field-level benefits — reduced overlap, lower operator fatigue, and extended operating windows — continue to be validated in productivity studies, strengthening the operational case for investment.
Strategic implications and recommended moves for 2026
- For OEMs: Prioritize platform openness with clear upgrade paths. Maintain capture of factory-installed revenue while enabling retrofit-friendly interfaces to address farmers who delay full fleet replacement.
- For aftermarket and tech vendors: Focus on modular solutions that reduce integration friction and on dealer training programs that shorten time-to-value in the field. Consider subscription pricing for positioning recurring revenue streams.
- For distributors and dealers: Invest in service capability and financing options. The purchasing decision is often more about risk mitigation and uptime than sticker price.
- For investors: Look for assets that combine hardware with data and service moats — companies that can monetize recurring GNSS corrections, software updates, and fleet analytics will command premium multiples.
- For policymakers and extension services: Encourage trials and co-funded pilots that de‑risk adoption for smallholders and midsize farms, and support spectrum and GNSS policy that stabilizes RTK availability.
Where this report acts as a strategic tool
Leaders who need to set 18–36 month investment priorities will find this report particularly practical. It turns market momentum into prioritized actions: where to allocate R&D spend, how to sequence product roll-outs, what dealer competencies to build, and which partnership archetypes deliver rapid scale. Our scenario models allow executives to map capital deployment to expected payback under conservative, base, and accelerated adoption cases.
Confidentiality of granular splits — and how to access them
In line with our “trailer” approach, this briefing surfaces the high‑value implications and the strategic narrative you need to act in 2026, while reserving detailed segment breakdowns, regional and application-level revenue tables, and granular vendor share matrices for the full report. That granular data underpins the actionable playbooks and ROI calculators referenced above; organizations that require immediate operationalization of those insights should review the full dataset and appendix.
Next steps
- Download the full report to obtain the segmented datasets, vendor scorecards, and financial models that support the recommendations summarized here.
- Schedule a capability workshop with PW Consulting to translate these insights into a 12–24 month commercial plan, including pilot design and dealer enablement roadmaps.
PW Consulting’s Worldwide Agricultural Automated Steering System market study is designed to convert market momentum into measurable advantage. For strategy teams preparing capital allocations, partnership roadmaps, or go-to-market plans in 2026, the report provides a concise, evidence-based foundation that bridges market sizing, competitive realities, and field-level execution.
For detailed analysis of this topic, please visit the official page: Worldwide Agricultural Automated Steering System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 20.15% CAGR for Worldwide Autologous Cell Therapy Market, Signaling Rapid Expansion Through 2032
By pmarketresearch, 2026-08-18
PW Consulting Release: Strategic Brief — Worldwide Autologous Cell Therapy Market (Base Year 2025)
PW Consulting today publishes an executive industry brief accompanying our full report, Worldwide Autologous Cell Therapy Market. Designed as a strategic “trailer” for C-suite and deal teams preparing for 2026 decision cycles, this briefing explains why autologous cell therapies will remain a high-growth, high-complexity sector — and how senior executives should prioritize investments, partnerships, and operational choices in the year ahead. For organizations that require the underlying, transaction-grade data and granular regional, application and source splits, the full report contains the complete dataset, modelling files, and playbooks.
Worldwide Social Login Tool Market
Why this market matters to 2026 strategy
The autologous cell therapy market has transitioned from niche clinical promise to commercial reality over the past half-decade. At the macro level, PW Consulting’s model shows a market that expanded markedly from the early 2020s and reached USD 8,426.12 Million (revenue unit: Million USD) in 2025 (base year). Our forecast indicates continued robust expansion into the next decade, with the market projected to exceed USD 10,035.55 Million in 2026 and reach USD 30,457.48 Million by 2032. This trajectory corresponds to a compound annual growth rate (CAGR) of 20.15% across the 2026–2032 forecast window — a profile that places autologous approaches among the fastest-growing segments in advanced therapeutics.
Mobile and Portable MRI Scanner Market
High growth plus concentrated supplier dynamics (our concentration analysis indicates a CR3 of 38.5% and a CR5 of 52.1%) creates both opportunity and risk. Market leaders capture meaningful commercial rents, yet there remains substantial room for new entrants with differentiated manufacturing, logistics, or clinical differentiation to disrupt the incumbency.
Worldwide Regulating Human Health Beverage Market
What PW Consulting’s report delivers — practical, decision-focused content
- Actionable market sizing and scenarios : Transparent methodology and stress-tested scenarios for 2026–2032 to support capital allocation, portfolio prioritization, and M&A valuation assumptions. The report includes base, upside and downside demand pathways tied to regulatory and reimbursement inflection points.
- Commercial-readiness playbooks : Step-by-step recommendations for field launches, phased market entry, and payer engagement — including model term-sheets for value-based and outcomes-linked reimbursement pilots.
- Supply chain and manufacturing assessment : Deep-dive on cost drivers, batch economics and scalable processing strategies — from decentralized point-of-care models to regional centralized facilities — plus a vendor matrix for automation, single-use systems and cold-chain partners.
- Regulatory and quality roadmap : Comparative analysis of FDA, EMA and key APAC regulators’ expectations for CMC, cGMP/cGTP compliance, and donor screening where applicable. Includes timelines and checklist templates for audit readiness.
- Pipeline and clinical risk tracker : Live table of late-stage autologous programs, anticipated regulatory milestones and probability-weighted timelines to commercialization — facilitating portfolio reprioritization and partnering decisions.
- Competitive & partnership playbook : Profiles of incumbent and emerging players, commercial strategies, vertical-integration options, and best-practice alliances between developers, CDMOs, and health systems.
- M&A and licensing intelligence : Deal comps, enterprise valuation sensitivities, and an M&A heat map identifying the most attractive capability gaps to fill through acquisition.
Operational dynamics and the business implications for 2026
- Manufacturing economics are decisive : Autologous processes remain inherently high-cost on a per-patient basis. Our sector synthesis finds production cost drivers (facility footprint, specialized labor, reagents, and one-batch-per-patient processing) often driving per-dose manufacturing expenses into a high five-figure range. For 2026 planning, executives must stress-test capital allocation between automation investments that reduce variable labor intensity versus outsourcing to CDMOs with mature patient-flow throughput.
- Logistics and cold-chain management are strategic : Time-sensitive patient-to-facility-to-patient flows magnify operational risk. Companies expanding geographically should prioritize redundant transport corridors, validated cryo-logistics vendors, and localized contingency capacity to protect time-to-treat windows.
- Reimbursement frameworks are evolving but remain a gating factor : Payers continue to demand outcome-linked models. Firms launching in 2026 should secure early payer dialogue, invest in real-world evidence infrastructure, and be prepared to pilot bundled or annuity payment models where clinical durability supports it.
- Regulatory diligence reduces launch risk : CMC and facility compliance issues are frequent causes of launch delays. Organizations targeting 2026 approvals must front-load regulatory interactions and ensure CMC packages and process validation studies are aligned with anticipated agency expectations.
Competitive landscape — strategic takeaways on core players
The marketplace is populated by global pharmaceutical leaders, dedicated cell therapy developers, and specialized biotechs. Our competitive analysis synthesizes capabilities, commercialization models, and near-term catalysts for the most consequential players:
- Novartis AG — A proven first-mover with commercial experience in autologous CAR-T. Novartis’s strengths lie in integrated commercialization, payer contracting experience and scalable manufacturing know-how. For competitors, Novartis sets the benchmark for post-launch support and provider engagement models.
- Gilead Sciences (Kite) — A dominant commercial engine for CAR-Ts with strategic appetite for portfolio diversification; recent M&A moves and late-stage filings indicate continued expansion in blood-cancer indications. Their deal-making posture makes them a natural partner or acquirer for high-quality BCMA or next-generation CAR portfolios.
- Bristol-Myers Squibb — Combines large oncology sales infrastructure with targeted cell therapy assets. BMS’s integration focus favors therapies that can be lodged within existing oncology pathways and benefit from cross-selling synergies.
- Johnson & Johnson (Janssen/Legend) — Positions itself on the multiple-myeloma and specialty-care axis; leverages deep hospital relationships and commercial scale to optimize uptake in complex inpatient and outpatient settings.
- Vertex — Demonstrates the value of gene-editing platform leverage in autologous cell therapy, with potential to expand into other monogenic conditions. Vertex’s regulatory and manufacturing rigor is an exemplar for companies seeking premium valuation multiples.
- bluebird bio, Vericel, Iovance, Autolus — Represent specialist developers with domain expertise in ex vivo gene-modified cells, tissue-engineered autologous products, and TIL or CAR constructs. These companies are potential consolidation targets or partners for commercial roll-out support.
- Notable regionals (e.g., Pharmicell, Holostem, ProKidney) — While smaller in scale, these organizations illustrate the clinical breadth of autologous approaches and the geographic diffusion of capability, particularly for localized indications and rare-disease niches.
For deal teams, the strategic lens should be: does the target add a clinical differentiation, a manufacturing or logistics advantage, or a payer-proven evidence package? Those three levers most directly compress commercialization timelines and derisk pricing negotiations.
Recent industry developments shaping 2026 strategy
- Late-breaking clinical and commercial preparations : 2025–2026 data readouts and leadership appointments highlight an industry moving from development to scale. Examples include late-breaking echocardiography data indicating potential cardiac remodeling benefits in ischemic heart failure, and companies appointing commercialization leadership ahead of expected launches — signals that an expanding set of indications is approaching commercial inflection.
- M&A and regulatory milestones : Ongoing acquisition activity and high-stakes Biologics License Application acceptances are compressing windows for strategic responses. Expect heightened valuation volatility around positive BLA outcomes and successful PDUFA decisions.
- Comparative clinical performance : New data demonstrating parity between innovative gene-edited or next-generation CAR constructs and established autologous CAR-T programs are likely to shift competitive dynamics, enabling nimble entrants to capture premium access if they can align manufacturing capacity with launch timing.
Three strategic recommendations for executives planning 2026
- Prioritize manufacturing modularity : Move capital decisions toward flexible, semi-automated systems that shorten changeover times and reduce per-patient labor. Consider dual-sourcing critical reagents and contracting with accredited CDMOs as a near-term hedge.
- Invest in evidence generation and payer partnerships : Allocate budget to registry infrastructure and early outcomes agreements. Demonstrating durable benefit will unlock broader reimbursement and justify higher list prices in value propositions tied to avoided downstream costs.
- Adopt a ‘selective scale’ commercialization cadence : Launch in high-yield centers of excellence with controlled capacity scaling tied to demonstrated referral flows and logistic performance. This reduces the risk of launch overspend and protects unit economics while adoption pathways mature.
Conclusion — why PW Consulting’s intelligence is decision-critical for 2026
Autologous cell therapies present a rare combination: rapid market expansion (projected to cross the ten-billion-dollar threshold in 2026) and operational complexity that penalizes poor execution. The market’s 20.15% CAGR through 2032 reinforces why boardrooms must move decisively — yet with a risk-managed playbook that addresses manufacturing, logistics, reimbursement, and regulatory realities. PW Consulting’s full report provides the granular segmentation, regional and application breakdowns, and financial models necessary to make those decisions with confidence.
To review the comprehensive datasets, validation tables, company scorecards, and downloadable modelling workbooks that underpin these findings, please consult the full Worldwide Autologous Cell Therapy Market report available through PW Consulting’s report portal.
For detailed analysis of this topic, please visit the official page: Worldwide Autologous Cell Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Automotive Platooning System Market Set to Soar at a 34.56% CAGR, Driving Rapid Industry Expansion
By pmarketresearch, 2026-08-12
Worldwide Automotive Platooning System Market: Strategic Preview for 2026 Decision‑Makers
PW Consulting’s new market study, Worldwide Automotive Platooning System Market, synthesizes five years of historical performance and a seven‑year forecast to equip executive teams with the evidence and frameworks required to make high‑stakes investments in freight automation in 2026. The study shows platooning moving from pilots into commercially material deployments: the global market is modeled rising from a base of USD 126.5 Million (base year 2025) to a projected USD 1,010.92 Million by 2032, expanding at a compound annual growth rate of 34.56% through the forecast window.
Worldwide Community Platforms Market
Why this study matters for 2026 strategy
-
Acceleration point: 2026 will be a pivotal year when regulatory pressure, fleet electrification initiatives, and maturation of vehicle‑to‑vehicle communications converge to change investment calculus. Companies that move from experimentation to structured commercial pilots now will be best positioned to scale in the 2027–2030 inflection period.
Disposable Medical Anticoagulation Tube Market -
Risk‑aware scaling: The market’s rapid projected expansion offers large upside, but uptake is uneven across geographies, vehicle types and business models. Our report supplies decision‑grade scenario analysis to quantify upside and downside across those variables without relying on simple extrapolation.
Nursing Reception Station Market -
Operational realism: Platooning is not just a software play. Implementation carries meaningful hardware, integration and human‑capital costs — we model typical per‑truck implementation costs and the real TCO breakpoints that determine fleet ROI.
Key dynamics shaping the market
-
Regulatory drivers and compliance pathways: Policymaking is defining near‑term demand. The EU’s heavy‑duty CO₂ reduction commitments and recent safety mandates (including required automated emergency braking on new trucks) create both obligations and enabling conditions. In the U.S., state‑level approval regimes and fleet decarbonization rules (for example, California’s advancing clean fleets requirements) create pockets of early commercial opportunity for platooning as a fuel‑efficiency and operational‑compliance lever.
-
Technology stack evolution: Successful platooning deployments require a tightly integrated stack of sensors, controls, V2V communications and fleet orchestration software. Operators face tradeoffs between communication technologies, integration complexity, and upgrade paths for mixed fleets. Our technical due diligence maps current options, maturity levels, and interoperability constraints to practical decision rules.
-
Cost and ROI constraints: Implementation incurs material upfront costs — driven by sensors, compute, communications and driver program costs — which our sector analysis places in a range that requires careful fleet economics to justify. The report’s TCO models show how utilization, route geometry, fuel prices, and regulatory penalties materially alter payback timelines.
-
Commercial concentration and ecosystem structure: The market shows emerging concentration among a handful of systems providers, OEMs and tier‑one suppliers. Our concentration analysis (CR3/CR5) quantifies current market share dynamics and provides a competitive map for partnership or M&A plays.
What the report contains — practical deliverables for 2026
-
Market sizing and forecast model: Full historical series (2020–2025) and bottom‑up forecasts (2026–2032) by total market value, with scenario variants to stress test CAGR outcomes under different regulatory, technology and macroeconomic assumptions.
-
TCO and pilot design toolkit: Configurable calculators that translate vendor quotes and fleet telematics into break‑even distances, utilization thresholds and expected emissions reductions — designed to support board‑level approvals for pilot investments.
-
Regulatory and standards playbook: A jurisdictional map of policy drivers, approval pathways and near‑term regulatory changes that materially affect fleet operability, including recommended compliance workflows for commercial pilots.
-
Competitive landscape and supplier scorecards: Independent assessments of incumbent vendors, OEM initiatives and tier‑one component suppliers across technical competence, commercial readiness and partnership fit — enabling defensible vendor shortlists.
-
Use‑case playbooks: Operational templates for freight corridors, cross‑dock logistics, and dual‑use (commercial/defense) applications, each with recommended runbooks, staffing models and safety oversight measures.
-
M&A and partnership frameworks: A set of diligence checklists, valuation sensitivities and integration risk matrices tailored for strategic investors considering minority stakes, joint ventures or bolt‑on acquisitions.
Competitive landscape: who matters and why
-
Systems innovators and scale players: A small group of technology companies and OEMs are defining early production deployments and commercial interfaces. These players combine vehicle integration capabilities with either proprietary communications stacks or open integration strategies. Their differing approaches to V2V communications, safety validation and fleet‑centric orchestration shape lock‑in risks and interoperability outcomes.
-
Case highlights — exemplar profiles
-
Peloton Technology (Mountain View, CA) has operationalized driver‑assistive platooning around DSRC‑based V2V links and emphasizes incremental safety and efficiency gains in commercial fleets.
-
Kratos Defense & Security Solutions (San Diego, CA) demonstrates cross‑domain application potential — expanding automated platooning support for logistics in high‑visibility events and dual‑use testing programs demonstrates an ability to deploy at scale rapidly and to adapt systems for ruggedized or mission‑critical use cases.
-
Major OEMs (including longstanding European and North American truck manufacturers) are integrating platooning capabilities into production vehicles, focusing on aerodynamic gains, platform reliability and multi‑brand convoy interoperability — a dynamic that will accelerate OEM‑led adoption once regulatory and market conditions align.
-
Tier‑one suppliers (sensor, brake and control specialists) are positioning to be the integration backbone by offering validated subsystems and retrofit packages that shorten time‑to‑pilot for fleets reluctant to rely on single‑vendor stacks.
-
-
Consolidation risk and partnership opportunities: Market concentration metrics indicate material advantages for early leaders yet leave substantial room for specialist vendors and integrators. For incumbent transport operators, partnering with validated system integrators rather than building in‑house end‑to‑end systems is often the lower‑risk path to early commercial benefit.
Recent market movements to watch in 2026
-
Deployment expansions by dual‑use providers, including high‑profile logistics support for major events, signal that platooning systems are operationally maturing and being stress‑tested in complex, long‑haul environments. These deployments yield real‑world performance data that materially shorten validation cycles for other fleets.
-
Regulatory updates and pilot approvals in multiple jurisdictions continue to shape where fleets can operate at scale; operators who align pilots with jurisdictional approval pathways secure first‑mover corridor advantages.
Strategic recommendations for executives (actionable in 2026)
-
Design tiered pilots: Launch a two‑stage pilot program that separates technology validation from commercial scaling. Stage one focuses on safety, communications interoperability and driver workflows; stage two emphasizes route optimization, pricing and commercial KPIs.
-
Prioritize interoperability and standards alignment: Avoid single‑vendor lock‑in by requiring open interfaces for telematics, over‑the‑air updates and fleet operations software. Insist on supplier commitments to multi‑brand convoy demonstrations as part of procurement criteria.
-
Model regulatory scenarios: Build financial models tied to specific policy outcomes (e.g., targeted emissions reduction mandates or state approval timelines). Use these models to determine optimal investment timing and the scale of pilot commitments.
-
Explore commercial innovations: Consider subscription models, retrofit service bundles, and performance‑based contracting with system providers to spread capital cost and align incentives for fuel‑savings delivery.
-
Prepare for human factors and training: Invest in driver training and revised operating procedures early. Effective human‑systems integration materially shortens time‑to‑value and reduces operational risk during scaling.
What PW Consulting recommends next
For boards, corporate strategy teams and private investors, the question is not whether platooning will be relevant — it already is — but how rapidly and where it will become profitable. Our report converts market momentum into decision‑grade intelligence: it quantifies market expansion, models plausible adoption curves under multiple policy and technology assumptions, and delivers practical toolkits to design, bid, and scale pilots with measurable KPIs.
We deliberately present this preview to demonstrate the analytical depth and practical orientation of the full study while preserving the proprietary granularity that underpins robust commercial decisions. To access the full forecast models, vendor scorecards, TCO calculators and jurisdictional playbooks that will inform board‑level investment decisions in 2026, please consult PW Consulting’s official report page and contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Platooning System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 8.12% CAGR for Worldwide Multifunction Baby Monitors Market Through 2032
By pmarketresearch, 2026-08-12
Worldwide Multifunction Baby Monitors Market: Strategic Imperatives for 2026
PW Consulting’s latest market study for Worldwide Multifunction Baby Monitors (base year 2025, forecast 2026–2032) delivers an operational roadmap for executives making consequential product, sourcing, and M&A decisions in 2026. The market is expanding at a compound annual growth rate of 8.12% in our forecast window; total industry revenue grows from roughly USD 1.85 billion in 2025 to an estimated USD 3.20 billion by 2032. Those macro trajectories mask rapid, asymmetric change at the product, channel and supply-chain level—our report synthesizes those inflection points into a practical playbook for commercial and corporate-strategy teams.
Worldwide Cytokinins Market
Why 2026 Is a Pivotal Year for Market Leaders and Challengers
-
Feature convergence and AI: Cameras with embedded computer vision, contactless respiratory sensing, and analytics-led sleep insights are shifting buyer expectations. Companies that combine robust on-device analytics with privacy-forward cloud services are capturing higher lifetime revenue per customer.
Hydropower Distributed Control Systems Market -
Regulatory and safety scrutiny: High-profile safety events and recalls are accelerating regulatory attention on charging systems, battery design and claims around clinical-grade monitoring. Brand safety and compliance are now material strategic risk factors.
Variable Inductance Shunt Reactors Market -
Supply-chain volatility: Semiconductor export controls, rising component prices, and extended lead times for sensors and MCUs are influencing sourcing strategies and time-to-market decisions in early 2026.
-
Channel migration and monetization: Online retail continues to consolidate share, but premium buyers still value bundled hardware-plus-subscription models sold through specialist channels and selective retail partners.
Market Dynamics & Recent Signals
-
Growth profile: An 8.12% CAGR to 2032 underpins a near-term expansion opportunity that justifies strategic investment in product differentiation and recurring-revenue models.
-
Safety incident: A February 2026 recall of Max View units (approximately 81,800 devices) due to parent-unit overheating underscores how product-safety events can rapidly degrade trust and distribution access; recall readiness and post-market surveillance are strategic necessities.
-
Product acceleration: In March 2026, Owlet announced expanded deployment of an AI-enabled camera paired with its wearable platform—illustrating the advantage of vertically integrated ecosystems that combine FDA-cleared sensors (where applicable) with camera-based analytics.
-
Adjacent component markets: Camera modules—the critical enabling subsystem for video-first monitors—are a multi-billion-dollar segment and exert pricing and capacity pressure on monitor OEMs; expectations for 2025–2026 show significant market activity that will cascade into supplier negotiations.
-
Competitive validation: Editorial and independent testing outlets continue to elevate multifunction models (both premium and value-tier) into mainstream buying guides, reinforcing the importance of third-party validation for purchase decisions.
Competitive Landscape — Practical Takeaways
The market exhibits moderate concentration (top-3 players ~32% of market revenue; top-5 ~49%). That mix yields advantages for both scale players and focused specialists. Below are distilled strategic implications from profiling core vendors:
-
Nanit — Strength: rich sleep analytics and computer-vision features. Recommendation: double down on privacy-certified analytics and deepen relationships with pediatric research groups to convert clinical credibility into premium subscription uptake.
-
Owlet — Strength: wearable + camera ecosystem with regulatory claims on certain wearables. Recommendation: use FDA clearance and clinical trial data to defend higher ASPs and to open clinical-channel partnerships (e.g., neonatal follow-up programs).
-
VTech — Strength: scale manufacturing and broad retail footprint. Recommendation: prioritize QC of charging/battery subsystems and differentiate with value-added software updates to protect mass-channel margins.
-
Infant Optics — Strength: hardware modularity (interchangeable lenses) and trusted audio/video performance. Recommendation: explore premium accessories and extended-warranty services to lift per-unit economics.
-
Motorola (Baby Division) — Strength: recognizable brand with distribution breadth. Recommendation: accelerate selective connectivity features while insulating non-WiFi FHSS SKUs for privacy-conscious segments.
-
eufy / Anker — Strength: hybrid Wi‑Fi and non-Wi‑Fi portfolio with strong value proposition. Recommendation: defend value tier via supply efficiency while piloting subscription tiers for advanced AI features.
-
Cubo Ai / Miku / iBaby / Lollipop — Strength: AI/feature differentiation and app ecosystems. Recommendation: convert engagement metrics into recurring revenue while investing in robust data-security certifications to lower privacy risk.
-
HelloBaby / Momcozy / Wyze — Strength: aggressive price points and broad global reach. Recommendation: manage risk through tighter supplier controls and product testing to avoid reputational damage from safety incidents.
-
Babysense (Hisense) — Current risk: post-recall remediation required. Recommendation: immediate root-cause remediation, transparent communication and enhanced third-party testing are prerequisites to restore retail relationships.
-
Philips (Avent) — Strength: corporate connected-care narrative. Recommendation: leverage enterprise-level compliance frameworks to target premium care-oriented channels and institutional procurement.
Operational Playbook for 2026 — Concrete Moves
-
Product & R&D: Prioritize on-device AI for latency-sensitive safety features while keeping privacy-by-design and data minimization as default architectures.
-
Supply-chain resilience: Secure multi-tier sourcing for camera modules and MCUs, negotiate capacity options with long-lead suppliers, and consider strategic buffer stock for critical SKUs.
-
Quality & Compliance: Expand in-market safety testing and third-party certification of charging systems and battery subsystems; implement a rapid trace-and-recall protocol linked to CRM and retail partners.
-
Commercial & Pricing: Test hybrid monetization—lowering entry price with optional subscription tiers for analytics and cloud storage—while protecting gross margins through accessory and service bundles.
-
Channel strategy: Optimize online retail with CPC-backed conversion funnels, invest in premium retail experiential displays for higher ASP SKUs, and insulate value SKUs via efficient distribution partnerships.
-
M&A and partnerships: Target complementary IP (AI analytics, sensor fusion) and distribution assets; prioritize targets that accelerate recurring revenue or close supply-chain gaps.
-
Risk management: Build scenario triggers for component-price shocks and regulatory tightening; map financial and inventory levers to 90–180 day playbooks.
Scenario Planning — Financial & Strategic Implications
Using the report’s baseline growth assumptions (CAGR 8.12%), the market expands meaningfully by 2032—creating attractive upside for firms that capture premium share in AI-enabled segments or establish defensible recurring revenue. Key scenario variables to monitor include the pace of regulatory standards for consumer monitors, semiconductor export-control dynamics, and the incidence of high-visibility safety events. Each scenario carries distinct implications for R&D cadence, inventory financing and working-capital management; our scenario matrices quantify those impacts and link them to go/no-go thresholds for investment rounds and M&A.
What the PW Consulting Report Contains (Practical, Executable Modules)
-
Market sizing & forecast model (2020–2032) with bottom-up validation and sensitivity testing.
-
Segment-level commercial playbooks (product architectures, channel maps, pricing experiments) — note: granular segment and regional tables are reserved for the full report.
-
Supplier landscape and procurement playbook for camera modules, MCUs, sensors and battery subsystems.
-
Regulatory matrix and safety-readiness checklist, including recall-response steps and certification pathways.
-
Vendor profiles and competitive positioning for leading OEMs, plus benchmarking on feature‑to‑price and subscription penetration.
-
M&A thesis library: target criteria, valuation heuristics and integration roadmaps for tuck‑ins and scale deals.
-
Scenario-planning templates tied to financial KPIs and inventory/cash-flow playbooks for rapid deployment.
Conclusion — Where to Focus in 2026
Executives should treat 2026 as a year to convert product innovation into defensible monetization while shoring up supply chains and compliance frameworks. The market’s growth trajectory creates room for both premium, clinically adjacent offerings and scaled value propositions, but commercial success will hinge on three capabilities: reliable safety and QA systems, robust supply-chain partnerships for critical camera and sensor components, and a clear subscription/value-exchange model tied to demonstrable analytics benefits. PW Consulting’s report turns these strategic imperatives into executable steps; for firms evaluating product roadmaps, procurement commitments or M&A targets, the detailed segment-level intelligence and vendor diagnostics in the full report are essential to inform board-level decisions in 2026.
Request the full Worldwide Multifunction Baby Monitors Market report from PW Consulting to access the detailed regional and segment tables, vendor financials, and our proprietary scenario models that support the operational recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Worldwide Multifunction Baby Monitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cordless Telephone Battery Market to Edge Down in 2026–2032 (CAGR −0.51%); 2025 Revenue USD 485.5 Million — Ni‑MH Dominates at USD 397.64M, Aftermarket USD 411.47M, Europe Leads with USD 151.01M
By pmarketresearch, 2026-08-12
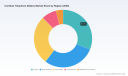
Worldwide Cordless Telephone Battery Market — Strategic Outlook for 2026 Decision‑Makers
Executive summary
The Worldwide Cordless Telephone Battery market is at an inflection point. While the installed base of DECT and low‑power cordless handsets supports a stable replacement economy, regulatory shifts and emerging DECT NR+ deployments are reshaping product requirements and supplier economics. Our PW Consulting report — based on a 2025 base year and a 2026–2032 forecast horizon — shows a 2025 market size of approximately USD 485.5 Million and a modest compound annual growth rate of -0.51% across the forecast period. This headline stability masks short‑term volatility and structural changes that will determine winners and losers in 2026 and beyond.
Wearable Smart Wristbands Market
Why this matters for 2026 planning
For executive teams responsible for product strategy, supply chain, and channel go‑to‑market, the cordless battery market no longer permits a "set and forget" approach. A near‑term rebound in 2026 (reflected in our top‑line projections) coexists with longer‑term downward pressure driven by device energy‑efficiency standards, shifting battery chemistry economics, and channel dynamics between aftermarket replacement and OEM supply. In practice, that means decisions made in the coming 12 months — component sourcing, warranty policy, and aftermarket engagement — will materially affect profitability and market positioning through 2028.
Worldwide Fire Department Software Market
What the macro data tells us
Key macro signals from the dataset and modelling underpin three practical conclusions for strategists:
Worldwide Bot Management Solution Market
- Stability with episodic volatility: The overall market base (2025) and the near‑term model show a bounce and subsequent oscillation in revenues rather than a monotonic decline. Tactical inventory and procurement flexibility will therefore outperform rigid annual contracting models.
- Low but negative long‑term drift: The slight negative CAGR across 2026–2032 indicates a gradual contraction driven by efficiency improvements, longer handset lifecycles, and regulatory energy benchmarks — not a sudden structural collapse. Firms should prioritize margin protection and cost containment over aggressive volume expansion.
- Concentration matters: Market concentration metrics in our analysis (CR3 ~38.5%, CR5 ~52.2%) reveal a mid‑consolidated sector where top vendors exert meaningful influence without forming a closed oligopoly. This creates fertile ground for mid‑sized players and nimble specialists to expand via targeted product or channel plays.
Regulatory and technology inflection points
Regulation and standards are the proximate drivers of technical specification changes that downstream battery suppliers will need to absorb. The EU Ecodesign rules (effective June 2025) introduce explicit expectations for energy efficiency and minimum battery cycle life performance, and base station standby power caps create a tighter energy budget across cordless ecosystems. Meanwhile, the progression toward DECT NR+ (spectrum and system updates rolled forward in late 2025) unlocks new handset capabilities but also raises implications for duty cycles and battery endurance.
Product launches such as Fanvil’s W610D demonstrate the pace at which handset OEMs are integrating higher performance cordless subsystems. Taken together, these developments move battery requirements from pure energy capacity metrics toward a richer set of attributes: cycle life under real‑world duty profiles, standby/active power interplay, thermal stability, and compliance documentation.
Supply chain and material dynamics
Cordless telephone batteries continue to be dominated by mature chemistries that balance cost, safety, and lifecycle for low‑power applications. In this market context, lithium‑ion price deflation at the consumer‑electronics level has limited immediate effect on the segment because product designers have not broadly shifted to Li‑ion for legacy DECT handsets. Geopolitical tensions and tariffs on critical minerals do meaningfully shape broader battery supply chains; however, cordless telephone packs typically exhibit lower exposure to those concentrated raw materials than, for example, EV or grid‑scale battery sectors. For procurement teams, the priorities are therefore:
- diversifying qualified NiMH and small‑format Li‑ion cell suppliers,
- maintaining robust secondary sources for cells and pack assembly, and
- locking technical specifications and test protocols that align with impending Ecodesign and DECT NR+ requirements to avoid costly late‑stage redesigns.
Competitive landscape — who matters and why
The market is a mix of retail/aftermarket specialists, traditional cordless OEMs, and battery manufacturers. Each cluster requires a different strategic posture:
- Retail and aftermarket specialists (examples: Interstate Batteries, BatteryClerk, Batteries Plus) — these players excel in channel reach, replacement compatibility, and brand trust among consumers and small businesses. For OEMs, partnerships or white‑label agreements with these distributors remain attractive routes to extend product life and recapture end‑of‑life value.
- Integrated handset OEMs (examples: VTech, Panasonic, AT&T) — OEMs control specification and have the most direct route to standardize compliant battery packs for new handset lines. They are also the primary locus for embedding Ecodesign compliance into new releases and shaping the market’s technical bar.
- Contract manufacturers and cell suppliers (examples: Shenzhen Tcbest Battery, EnerSys) — these vendors provide the manufacturing capacity and engineering know‑how necessary for scale and customized pack solutions. Their role becomes pivotal when OEMs pursue rapid spec changes to meet regulation or new DECT features.
Our report contains concise strategic profiles of these firms, highlighting supply strengths, channel footprints, and M&A posture — enabling quick benchmarking and partner selection in 2026.
Commercial dynamics: aftermarket vs OEM
The aftermarket replacement economy remains the primary margin and volume engine for the cordless battery market. OEM replacement and bundled supply are strategically important for new handset launches and brand‑protected channels. For 2026, the tactical priorities differ by role:
- Retailers and aftermarket specialists should invest in warranty clarity, compatibility search tools, and compliance labeling to capture consumers trading up under Ecodesign awareness.
- OEMs need to accelerate battery validation programs and consider extended service/recertification offers to capture lifecycle revenue while conserving device longevity in a regulation‑tightened environment.
Practical recommendations for 2026
Leaders who intend to use 2026 to build durable advantage should prioritize five actions:
- Operationalize regulation: Build a cross‑functional Ecodesign readiness program (product, test labs, compliance, marketing) with a 6–12 month roadmap and clear acceptance criteria linked to warranty and R&D budgets.
- Flexible sourcing: Move to smaller, more frequent cell procurement contracts with dual qualified suppliers to buffer short‑term swings while maintaining price discipline.
- Aftermarket monetization: For OEMs, create certified replacement programs and trade‑in pathways that capture revenue and reduce gray‑market leakage.
- Portfolio triage: Apply a profitability heatmap across SKU families to decide which battery technologies and handset lines justify engineering investment versus those better suited to aftermarket replacement strategies.
- M&A and partnerships: Given mid‑market concentration, identify tuck‑in targets among regional pack assemblers or aftermarket specialists to accelerate channel scale and technical capabilities.
What PW Consulting’s report delivers
Our Worldwide Cordless Telephone Battery Market report is designed as a practical playbook for 2026. It includes:
- Top‑line forecasts and scenario modelling (base case, high demand, regulation‑forced redesign) for 2026–2032, with stress testing for energy‑efficiency and unit‑life assumptions.
- Supplier and channel heatmaps with qualitative supplier capability assessments and an M&A watchlist.
- Regulatory impact matrix (including Ecodesign obligations and DECT NR+ implications) that links compliance actions to capex and product timelines.
- Operational annexes: test protocols, recommended battery validation matrices, warranty framing templates, and an aftermarket monetization playbook.
- Executive dashboards and a downloadable scenario model so commercial teams can run "what‑if" cases specific to their product and region strategies.
How to use this insight in the boardroom
Board conversations in 2026 should move beyond positional statements about "market decline" to granular decisions tied to procurement cadence, product roadmap triage, and channel economics. Use the report’s scenario tool to quantify the P&L impact of: changing minimum cycle life requirements, supplier consolidation, and an increasing share of sales moving to certified replacement channels. That work will identify whether to accelerate R&D (for regulated compliance), de‑risk supply, or double down on aftermarket services.
Next steps and where to find the full segmentation
In keeping with our "trailer" approach, this release highlights the strategic takeaways and supporting context you need to prioritize 2026 actions while deliberately reserving the granular, segment‑level tables and model outputs for the full report. For access to detailed region, chemistry and channel split data, downloadable models, and vendor scorecards, please visit the PW Consulting report page or contact our industrial practice team for a tailored briefing.
Prepared by PW Consulting — Senior Strategy & Industry Analysis. For executive briefings or bespoke modelling workshops tied to this market, our team is available to support rapid, board‑level decision cycles in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Cordless Telephone Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects 7.85% CAGR for Worldwide Veterinary Glucometers Market During 2026–2032
By pmarketresearch, 2026-08-12
Worldwide Veterinary Glucometers Market — Strategic Outlook for 2026: PW Consulting Report Preview
Executive summary
PW Consulting’s new market study on Worldwide Veterinary Glucometers provides a targeted, decision-ready briefing for executives planning product, commercial, and M&A strategies in 2026. The veterinary glucometers market has matured into a predictable growth opportunity: after expanding through 2020–2025 and reaching an estimated market size of USD 545.6 Million in our 2025 baseline, the market is forecast to continue at a robust compound annual growth rate (CAGR) of 7.85% through our 2026–2032 modeling horizon, approaching roughly USD 926 Million by 2032. For leadership teams evaluating near-term investments, this trajectory frames how quickly incremental innovations — especially around continuous glucose monitoring (CGM), species-specific algorithms, and connected care — can scale commercial returns.
Aircraft Lift Control Devices Market
Why this preview matters for 2026 decision cycles
- Timing of strategic moves: With a clear upward trajectory from the 2025 baseline into 2026, the window for first-mover advantage on clinic-directed CGM products and integrated digital services is narrowing. Executives who align R&D and distribution decisions to calendar-2026 launch windows can capture premium adoption among progressive veterinary networks.
- Capital allocation prioritization: Our scenario work shows that incremental investments in species-specific calibration, clinical validation, and vet-facing software yield outsized returns versus equivalent spend on general-purpose human meters repurposed for animals.
- Channel and partnership sequencing: The market’s current structure — moderately concentrated among a few global animal-health majors and specialized device providers — favors hybrid strategies combining direct distribution to veterinary hospitals with distributor-led clinic and retail channels for home care adoption.
What the full report contains (practical deliverables)
This preview highlights strategic findings; the complete PW Consulting report delivers the operational tools that business and product teams will use to execute against them. Key deliverables include:
Worldwide Video Lottery Terminals (VLT) Market
- Dynamic market model (2020–2032) with downloadable scenario tabs (base, conservative, accelerated) enabling sensitivity testing of price, adoption and reimbursement levers.
- Go-to-market playbooks tailored to four commercial archetypes — global animal-health incumbent, hospital-focused specialist, digital-native CGM entrant, and distributor-led aggregator — with roll-out timelines calibrated to 2026 regulatory and purchasing cycles.
- Product feature and technical benchmarking, showing where species-specific calibration, sample volume, connectivity, and analytics deliver the greatest clinical and commercial delta.
- Regulatory and validation checklist for veterinary devices, including sample study designs to verify species-specific accuracy against laboratory reference methods and guidance on where ISO 15197 performance verification matters.
- Pricing elasticity and reimbursement matrix that models out-of-pocket versus clinic-procured adoption scenarios for companion-animal versus herd applications.
- Competitive playbooks and M&A screening filters with candidate lists and illustrative valuation ranges based on product portfolio complementarity and distribution footprint.
Market structure and competitive dynamics — how to read the competitive map
Our concentration analysis shows a market where the top three players capture a clear majority of revenue, and the top five extend that dominance further. This structure creates both defensive and offensive strategic implications: incumbents benefit from scale and established clinic relationships, while agile specialists can win on product differentiation and clinic-directed CGM offerings.
Multispecific Antibody Development Platform Market
Leading firms profiled in-depth include animal-health majors and focused device makers. Their strengths, strategies, and likely near-term moves are summarized below — the full report contains comparative scorecards, channel overlap maps, and launch-timing matrices for each named competitor.
- Zoetis — With AlphaTrak 3, Zoetis has leveraged species-specific algorithms and a pet-owner / clinician mobile app to entrench its position in companion-animal glycemic monitoring. Its playbook emphasizes integrated clinical workflows and data-sharing between clinics and owners, a model other incumbents are trying to emulate.
- i-SENS — i-SENS’ veterinary-calibrated meter (VetMate) represents the strategy of translating human-glucose sensing expertise into validated veterinary use with focused calibration for dogs and cats; it competes primarily on cost and distribution breadth.
- Nova Biomedical — Nova Vet’s combined glucose/ketone meters position the company to serve both companion and herd-related use cases, an approach that diversifies revenue streams but requires differentiated go-to-market motions.
- Universal Biosensors — PETRACKR focuses on handheld point-of-care tools with multi-pet profile management, targeting clinic workflows where repeat testing and patient tracking matter most.
- ALR Technologies (GluCurve), Adapet Medical — These entrants are accelerating the CGM shift for pets. ALR’s recent internal manufacturing validation and planned relaunch, and Adapet’s integrated monitoring of glucose, activity, and feeding data, underscore the sector’s technological pivot toward continuous, clinic-managed solutions.
- UltiMed / Advocate, MAI Animal Health, Woodley Equipment — These companies emphasize validated, species-specific handheld meters and accessories that support both clinical and at-home testing; they represent critical distribution nodes for broadening home-care adoption.
Regulatory and clinical validation: non-negotiables for 2026
Regulatory expectations and clinical best practices are central drivers of procurement decisions in veterinary medicine. Our report synthesizes current regulatory guidance and recent validation literature to provide a pragmatic pathway for CE-marking and for meeting expectations in major markets. Key regulatory realities include:
- Species-specific calibration and validation — devices must demonstrate accuracy against laboratory reference methods in the animal matrices they target (dog, cat, horse), and clinicians will expect documented, peer-reviewed comparators.
- Standards alignment — where ISO 15197 accuracy criteria can be applied or adapted to veterinary matrices, adherence materially improves purchaser confidence.
- Clinical trial design — the report includes templates for pivotal validation studies sized to support both veterinary-clinic adoption and distributor purchasing decisions, reducing time-to-order through pre-validated evidence packages.
Tech and product trends that will shape 2026 wins
Three clusters of innovation will disproportionately influence outcomes in 2026:
- Continuous Glucose Monitoring (CGM) for clinic-directed care: CGM systems designed specifically for pets are moving from niche to mainstream. These devices require clinic-directed distribution and support; companies that align manufacturing, training, and distribution with major veterinary distributors will scale fastest.
- Species-specific analytics and low-sample-volume meters: Companion-animal meters that minimize sample volume and provide species-calibrated outputs reduce clinical friction and improve owner adherence — direct drivers of retention and recurring consumables revenue.
- Connected care and data services: The value proposition increasingly includes cloud analytics, vet-owner sharing, and care-path orchestration. Monetization models extend beyond device sales to subscription-based analytics and clinic licensing.
Commercial implications and recommended plays for 2026
- For incumbents: Protect clinical relationships by bundling validated CGM pilots with training and data services for high-volume clinics. Use scale to negotiate distributor exclusivity in priority geographies and to rationalize consumables pricing.
- For challengers and startups: Focus on clinical evidence that demonstrates parity with leading handheld meters and highlight unique data features (e.g., integrated feeding/activity signals). Consider selective regional launches via partner clinics to build clinical case series prior to national rollouts.
- For distributors and retailers: Align inventory strategies to support hybrid purchasing — clinic procurement for CGM devices and retail/home options for validated handheld meters — and develop product education cohorts to accelerate vet endorsement.
- For investors and M&A teams: Target targets that bring either validated CGM IP, species-specific algorithm portfolios, or high-margin consumables with sticky clinic workflows; use the report’s M&A filters to screen and prioritize opportunities by time-to-market and channel fit.
Risk considerations and mitigation
Key risks include regulatory delays in local markets, off-label use of human flash glucose systems that can depress veterinary-specific device uptake, and supply-chain constraints for sensors and test strips. The full report offers mitigation playbooks, including tactical manufacturing redundancy plans, regulatory filing roadmaps, and clinical-education programs that reduce the attractiveness of off-label substitutes.
Next steps — how to use this preview
This preview is designed to inform 2026 planning conversations and to prioritize actions for product, commercial, and corporate development teams. For teams ready to act, the full PW Consulting report supplies the granular data, segmentation tables, competitor scorecards, and downloadable financial model necessary to build business cases, investment memos, and launch plans. Because the most actionable intelligence is in the fine-grained splits and scenario work, we intentionally withheld granular segmentation figures from this preview; the full dataset and model are available on the report landing page.
Recent developments highlighted in the report
- ALR Technologies completed internal manufacturing testing for its GluCurve Pet CGM in late 2025 and is planning a phased relaunch into Canada and the US in early 2026 — a development that shifts competitive dynamics for clinic-directed CGM solutions.
- Zoetis’ earlier launch of AlphaTrak 3 and its integrated mobile app illustrates the competitive edge obtained by coupling species-specific measurement with digital care pathways — a model the report evaluates for replication and defense strategies.
Get the full intelligence
To convert these insights into executable plans for 2026, PW Consulting’s full report and model provide the referenced segmentation detail, vendor-level financial benchmarks, and policy-readiness checklists. Access to the complete study includes one-on-one analyst time for bespoke scenario runs tailored to your portfolio and priority markets.
PW Consulting — from validated market sizing to tactical playbooks, we equip leaders to turn the veterinary glucometers market’s growth trajectory into sustained competitive advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Veterinary Glucometers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide MRI-Compatible IV Infusion Pumps Market Poised for 8.6% CAGR (2026–2032)
By pmarketresearch, 2026-08-12
Worldwide MRI Compatible IV Infusion Pumps Market — Strategic Imperatives for 2026
PW Consulting today releases a strategic industry briefing accompanying our full market research report on the Worldwide MRI Compatible IV Infusion Pumps Market. Built for executive teams, corporate development functions, and health system procurement leaders, this briefing distills why 2026 will be a pivotal year for competitive positioning, capital allocation, and regulatory strategy in a market that is accelerating toward clinical mainstreaming.
Worldwide Linear Ultrasound Transducers Market
Snapshot: A market maturing at commercial and clinical frontiers
Our analysis uses 2025 as the base year and models the market through 2032. The global market for MRI-compatible IV infusion pumps—measured in USD millions—grew from USD 312.45 Million in 2020 to USD 465.00 Million in 2025. Under our central scenario, the market continues to expand at a compound annual growth rate (CAGR) of 8.6% across the forecast window (2026–2032), reaching an estimated USD 828.44 Million by 2032. This trajectory reflects a convergence of clinical demand, regulatory clarity, and targeted procurement programs that together lower barriers to in-scanner infusion therapy.
Worldwide Handwritten Notes Software Market
What is driving the next phase of adoption?
- Clinical demand for simultaneous imaging and therapy: Increasing MRI throughput, advanced interventional MRI workflows, and growth in pediatric/neonatal imaging heighten the clinical value of infusion devices that can safely operate in high-field environments.
- Regulatory and procurement tailwinds: Recent regulatory clearances and public procurement decisions recognizing non-magnetic solutions are creating reference cases that shorten the approval pathway and buying cycles for early adopters.
- Product innovation unlocking new use cases: Advances in non-magnetic drive systems (including ultrasonic motors), integrated drug libraries, wireless control interfaces, and systems-level shielding are shifting the value conversation from “if” to “how” to use infusion pumps in and around the MRI bore.
- Capital planning and replacement cycles: Hospital capital planning frameworks and useful-life benchmarks—commonly applied in the sector—are prompting refresh cycles in 2026 for infusion hardware purchased in the previous decade, creating demand windows for vendors with robust total-cost-of-ownership (TCO) propositions.
Regulatory and procurement context — why 2025–2026 matter
Two regulatory facts have immediate strategic implications. First, the FDA’s 510(k) pathway for MRI-compatible infusion pumps remains the primary route to U.S. market access; recent clearances demonstrate the agency’s expectations for device performance and human factors evidence. Second, public-health procurement authorities are increasingly willing to recognize unique clinical needs through sole-source or specialized procurement justifications when a truly non-magnetic solution is demonstrably unique.
Cold Atom Gravimeter Market
For market entrants and incumbents alike, the practical consequence is that a well-executed regulatory dossier (with strong human factors and clinical validation) plus targeted reference deployment can materially shorten sales cycles and support premium pricing—if supported by demonstrable patient-safety and workflow benefits.
Competitive landscape: consolidation, niche leadership, and product differentiation
The MRI compatible infusion pump market is highly concentrated, with the top three players commanding the vast majority of commercial revenues and the top five extending that dominance further. This concentration reflects significant technical barriers—validated non-magnetic actuation, MRI safety testing up to high gauss levels, and documented clinical workflows—that favor specialized suppliers and established infusion-platform vendors able to invest in certification and field support.
Key vendor archetypes identified in our report:
- Specialist non-magnetic innovators — Companies focused specifically on MRI-safe pump platforms have technological and regulatory advantages in the in-bore and near-bore use cases. Recent product clearances from such specialists create important commercial references.
- Large infusion-platform incumbents — Global infusion manufacturers leverage wide hospital footprints and integrated infusion management systems to sell MRI-aware solutions as part of broader therapy bundles.
- System integrators and shielding suppliers — Vendor solutions that pair infusion pumps with shielded carts or dedicated MRI-room platforms are establishing differentiated value propositions for complex multi-pump workflows.
Representative firms covered in the report include specialized innovators headquartered in the United States with cleared MRI offerings, legacy infusion systems vendors with MRI-compatible variants, and European and North American manufacturers offering integrated shielding solutions. Recent milestones in the competitive set—the granting of a 510(k) clearance for a next-generation non-magnetic pump system in May 2025 and a subsequent sole-source procurement intent from a major U.S. healthcare purchaser in early 2026—illustrate how regulatory milestones can immediately translate into procurement advantages for niche leaders.
Strategic implications for corporate decision-makers in 2026
As organizations plan priorities for 2026, the report highlights concrete actions across four decision vectors: product strategy, commercial go-to-market, regulatory and clinical evidence, and corporate development.
- Product strategy: Invest in non-magnetic actuation, robust drug libraries, intuitive wireless control, and modular shielding options. Prioritize human factors engineering early in development to de-risk 510(k) submissions and to shorten time-to-reference sites.
- Commercialization & partnerships: Forge alliances with imaging OEMs, MRI-focused systems integrators, and high-volume imaging centers. Design bundled offers that address workflow friction points—cabinetized carts, centralized monitoring, and MRI-safe tubing management—rather than standalone pumps alone.
- Regulatory & clinical evidence: Allocate budget to pre-market studies that align with FDA Total Product Life Cycle expectations and establish early clinical references in academic centers able to publish outcomes. These references accelerate adoption among health systems and support higher reimbursement or procurement prioritization.
- Corporate development: For incumbents seeking rapid capability upgrades, targeted acquisitions or minority investments in specialist non-magnetic pump makers can be a faster route to validated technology and installed-clinic references than greenfield R&D.
Risk matrix: what keeps CFOs and CPOs awake at night?
- Regulatory delay risk: Complex human factors expectations and the need for MRI-specific safety testing can extend approval timelines if not anticipated.
- Procurement variability: Differences in public and private procurement policies—especially where sole-source justifications are involved—mean that commercial success can hinge on a small number of early institutional wins.
- Clinical adoption hurdles: The incremental complexity of in-bore infusion workflows requires investment in training and change management; the cost of inadequate training can blunt adoption.
- Supply chain and component risk: Specialty components for non-magnetic actuation and shielding can face constrained supplier availability; suppliers should build redundancy into sourcing strategies.
What PW Consulting’s full report delivers — and why the granular data matters
Our full market study (base year 2025; forecast 2026–2032) combines a rigorous topline forecast with deep, actionable modules designed for strategy execution:
- Detailed market-sizing and growth scenarios with sensitivity analysis under alternative adoption and reimbursement assumptions.
- Segment-level analyses covering device types, clinical applications, and regional dynamics (note: segment-level numerical breakdowns are covered in the full report).
- Vendor scorecards and product benchmarking against safety, performance, usability, and service metrics.
- Regulatory pathway maps and clinical evidence templates tailored to 510(k) submissions and human-factors planning.
- Procurement playbooks for hospital purchasing groups and public health authorities, including negotiation levers and total-cost-of-ownership models built around common capital-life benchmarks.
- M&A and partnership targets identified by strategic fit and integration risk, with modeled impact on market share and revenue synergies.
To preserve the strategic value of this briefing and to support competitive decision-making, we have intentionally withheld detailed granular splits and proprietary scenario outputs from this press summary. The full dataset, vendor-by-vendor performance matrices, and downloadable financial models are available through the PW Consulting report portal.
Conclusion — why 2026 is a make-or-break year
For executives evaluating capital allocation and go-to-market strategy, 2026 presents a window of opportunity: regulatory clarity and early procurement precedents are converting a historically niche capability into an investable clinical platform. Companies that align product development with rigorous human factors data, secure early clinical references, and craft bundled workflow solutions will capture disproportionate upside in a market that is forecast to nearly double in revenue through 2032 at an 8.6% CAGR.
PW Consulting’s full report equips decision-makers with the quantitative forecasts, vendor intelligence, and tactical playbooks required to act in 2026 with confidence. For access to the complete study, including our proprietary models and vendor scorecards, please consult the PW Consulting report release page.
For detailed analysis of this topic, please visit the official page: Worldwide MRI Compatible IV Infusion Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cupping Therapy Kits Market Poised for 5.8% CAGR in 2026–2032
By pmarketresearch, 2026-08-12
Worldwide Cupping Therapy Kits Market: Strategic Preview for 2026 Decision-Makers
Executive snapshot
As PW Consulting’s senior industry analyst, I present a guided preview of our newest market research — the Worldwide Cupping Therapy Kits Market report (base year 2025). This briefing highlights the strategic signals that matter for boardrooms, corporate strategy teams, and private investors planning moves in 2026. It demonstrates the report’s practical value without disclosing the full, proprietary segmentation tables and financial matrices reserved for the full publication.
Mini LiDAR Market
Why this market matters in 2026
Cupping therapy kits sit at the intersection of traditional medicine, consumer wellness, and clinical rehabilitation. After recovering from early-pandemic volatility, the global market expanded from an estimated USD 145.2 Million in 2020 to USD 192.48 Million in 2025. Under the conservative scenarios modeled in our forecast, the market continues to grow through the 2026–2032 window at a compound annual growth rate (CAGR) of 5.8%, reaching an expected market size above USD 285 Million by 2032.
Worldwide Journal Software Market
That trajectory is meaningful for three categories of decision-makers:
Canopy Light Market
- Manufacturers seeking scale efficiencies and product differentiation
- Distributors and service providers building integrated recovery suites
- Healthcare institutions and payors evaluating inclusion in care pathways
Market dynamics shaping 2026 strategies
Our sector analysis identifies five converging dynamics companies must internalize before committing capital:
- Product innovation and material evolution: Manufacturers are diversifying from traditional glass cups into silicone, thermoplastic and hybrid systems that prioritize safety, durability, and user comfort. Innovations in pump ergonomics, magnetic attachments, and shock/heat-resistant materials are enabling broader clinical adoption and home-use positioning.
- Clinical integration and reimbursement signals: Cupping therapy is increasingly embedded within rehabilitation and pain-management protocols. Industry billing practices reference existing physical-medicine CPT codes in certain settings, and institutional purchasers (including public health systems) are evaluating reimbursement pathways — a trend that materially affects procurement strategies for clinics and device suppliers.
- Regulatory clarity and standards: Cupping kits continue to be regulated predominantly as Class I medical devices in major markets, with relevant ISO standards for air-extraction and glass cupping devices in place. This creates a baseline compliance expectation but also opens opportunities for early movers who obtain voluntary quality certifications and robust clinical claims.
- Channel and education ecosystem: Sellers that bundle education (continuing education units, practitioner training) with product offerings are winning higher retention and premium pricing, especially in practitioner-targeted segments.
- Fragmented competitive structure: Market concentration remains low relative to many medical-device subsegments. Our concentration indices indicate a fragmented supplier base, creating opportunity for consolidation and for specialized incumbents to capture niche premium roles.
What the PW Consulting report delivers — practical, actionable content
This study was built to guide real-world decisions. The full report includes:
- Detailed market sizing and trend validation (historical 2020–2025 and modeled forecasts 2026–2032), with sensitivity scenarios and upside/downside drivers.
- Proprietary forecast model delivered in Excel, enabling users to re-run scenarios after adjusting pricing, adoption curves, or regulatory assumptions.
- Supply chain maps and cost-driver analysis from raw materials to finished-packaging decisions, including labor, logistics, and tooling considerations.
- Channel and commercialization playbooks for clinic, sports-rehab, and direct-to-consumer (D2C) routes to market — including pricing benchmarks, bundling strategies, and education-led retention models.
- Regulatory and reimbursement navigators: step-by-step compliance checklists for major markets, ISO alignment guidance, and payer engagement briefs for institutional sales teams.
- Customer segmentation frameworks and buyer-persona profiles tailored to practitioners, physiotherapists, and informed consumers who buy at-home kits.
- Strategic M&A and partnership screening matrix highlighting target profiles for tuck-ins, technology acquisitions, and distribution alliances.
- Risk matrices, mitigation options, and contingency plans for supply shocks, regulatory shifts, and reputational risks related to clinical safety concerns.
- Primary interview insights: synthesized perspectives from practitioners, procurement officers, and senior product managers collected during our 2025–2026 fieldwork.
Competitive landscape — who to watch and why
The market features a mix of established equipment producers, specialized silicone and glass manufacturers, and distributors bundling education and clinical services. The landscape’s fragmentation, reflected in modest top-three and top-five concentration ratios, leaves room for brand differentiation and vertically integrated models.
- EarthSpa R&D (United States) — Known for handblown glass and in-house plastic pump systems, EarthSpa’s positioning centers on ’made-in’ quality and practitioner trust. Expect continued focus on premium clinical channels and design-protected products.
- Lhasa OMS (United States) — A diversified supplier with product lines spanning silicone, glass, and magnetic offerings; appeals to licensed acupuncturists and integrative health clinics via combined product-and-education programs.
- HawkGrips (United States) — Emphasizes dynamic cupping for sports recovery and clinical CEU-backed programs; a playbook for companies seeking to monetize education alongside hardware.
- Thysol US / FASCIQ (United States) — Targets fascia and massage therapy markets with premium silicone solutions; strong channel affinity with manual-therapy professionals.
- Kangzhu (China, via Taizhou Xinkang) — Original maker of classically engineered plastic vacuum systems and pumps; cost-competitive manufacturing with regulatory credentials in markets requiring Class I registration.
- Boen Medical (China) — Glass cupping specialist positioned for scale; relevant to buyers prioritizing traditional materials and lower-cost clinical inventories.
- MMT Cupping, Cupping International, Performance Health and others — A diverse group of suppliers and distributors that combine product breadth, clinical distribution networks, and rehabilitation-focused kits.
Recent product moves underline the market’s dual emphasis on performance and home-wellness adoption. Notable developments in 2025–2026 include expanded integrated recovery kits for physiotherapy, new ergonomic professional pumps, and refreshed silicone/magnetic product waves across Asia-Pacific. These moves validate our hypothesis that packaging, training, and system-level integration are as important as cup design itself.
Strategic implications: six priority actions for 2026
Based on our modeling and field interviews, companies should prioritize the following:
- Clarify target customer economics: Build P&L models for practitioner bundles versus D2C offerings; quantify lifetime value differences driven by recurring consumables and training revenues.
- Invest in validated clinical evidence: Short, focused clinical studies and documented case series will materially accelerate institutional adoption and payer conversations.
- Design supply resilience into product roadmaps: Dual-source critical components, standardize materials to reduce regulatory complexity, and consider regional assembly to shorten lead times.
- Differentiate through services: Offer CEU-accredited training, digital rehabilitation protocols, and telehealth-enabled onboarding to capture higher-margin accounts.
- Pursue pragmatic M&A and partnerships: Target acquisitions that fill distribution gaps, add clinical evidence capacity, or incorporate complementary modalities for integrated recovery kits.
- Prepare for regulatory and reimbursement evolution: Invest in compliance documentation, ISO alignment, and payer-engagement templates to move quickly if CPT coding and benefits change regionally.
How PW Consulting’s report accelerates execution
For strategy teams, the full report is a decision-enabler rather than an academic exercise. The integrated Excel model lets executives test: (a) price-elasticity in home versus professional channels; (b) the impact of unit-cost reductions from regional manufacturing; and (c) the ROI of bundling training with hardware. Our M&A screening tool surfaces targets aligned to four acquisition archetypes (scale, capability, channel, and technology) and ranks them against five execution risks.
Closing perspective and next step
The Worldwide Cupping Therapy Kits Market is moving from niche therapeutic practice toward broader clinical and consumer adoption. The path to 2026 is navigable for organizations that act now: solidify clinical credibility, build resilient supply and manufacturing strategies, and monetize services around hardware. Fragmentation creates opportunity — for first movers who integrate product, education, and clinical partnerships, and for investors seeking consolidation opportunities.
To access the full dataset, segmented forecasts, valuation matrices, and the downloadable forecast model, visit the PW Consulting report page. The detailed splits and proprietary financials are intentionally reserved for the comprehensive report to preserve client value and enable confident execution planning.
For detailed analysis of this topic, please visit the official page: Worldwide Cupping Therapy Kits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Conjunctivitis Ophthalmic Drugs Market Valued at USD 5,466.5 Million in 2025, Poised for Further Growth
By pmarketresearch, 2026-08-12
Worldwide Conjunctivitis Ophthalmic Drugs Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market intelligence on the Worldwide Conjunctivitis Ophthalmic Drugs Market synthesizes multi-year observed performance with scenario-driven forecasts to 2032. Our analysis shows a resilient expansion of the overall market from just over USD 4.2 billion in 2020 to USD 5.47 billion in 2025, with a continued upward trajectory across the 2026–2032 forecast window. The market’s compound annual growth rate (CAGR) over the forecast period stands at 5.51%, underpinned by persistent demand in allergic and infectious indications, product innovation, and an evolving competitive and regulatory landscape.
Worldwide Scanning Lenses Market
Why this report matters for 2026 strategy
-
Actionable foresight: We translate broad-market momentum into discrete strategic options that are executable within 12–24 months — from lifecycle management and portfolio prioritization to targeted M&A and market-entry sequencing.
RV Backup Power System Market -
Investment prioritization: The report frames where to allocate R&D and commercial resources to capture disproportionate value as category dynamics shift (e.g., branded innovation vs. generic displacement, novel delivery forms vs. traditional drops).
Worldwide Ball Joints Market -
Risk calibration: We quantify systemic exposures — regulatory timing, reimbursement hurdles, and API supply constraints — and map mitigation levers correlated with upside scenarios.
Report scope and practical contents
-
Market sizing and trend analysis: Year-on-year market sizing from 2020 through 2025, with forward projections through 2032. Our models reconcile historical sales, launch trajectories, and expected therapeutic substitution dynamics to produce base, upside, and downside cases.
-
Competitive benchmarking: Detailed company profiles, commercial footprint assessments, and capability matrices covering global innovators, specialty ophthalmology firms, and major generic/contract manufacturers.
-
Clinical and pipeline intelligence: Assessment of late‑stage assets, delivery technologies (including ocular inserts and intracanalicular systems), and the potential commercial impact of recently approved or launched products.
-
Regulatory, reimbursement & payer playbook: Jurisdiction-specific timelines and reimbursement sensitivities, plus recommended dossier content and real‑world evidence strategies to accelerate formulary access.
-
Go‑to‑market blueprints: Channel segmentation, clinician and patient adoption drivers, and tactical launch plans calibrated to diverse healthcare systems.
-
Commercial financial models: Scenario-ready revenue models and margin stress tests designed for M&A diligence, licensing negotiations, and internal capital allocation.
Note: In this briefing we present high-level conclusions and strategic guidance. The full report contains granular segment tables, country-level forecasts, product-level unit and value estimates, and downloadable financial models — access details are provided at the end of this release.
Market dynamics shaping 2026 decisions
-
Innovation in delivery formats is changing the clinical and commercial calculus. Intracanalicular inserts and long-acting formulations continue to gain attention for their adherence benefits, especially in allergic indications where episodic symptoms and patient compliance have historically limited therapeutic impact.
-
Genericization remains a major force. The recent acceleration of generic ophthalmic launches amplifies pricing pressure for established branded drops and shortens the effective exclusivity period for commodity anti-infectives and anti-allergy agents. This dynamic makes early lifecycle actions — such as formulation improvements, device-enabled delivery, and line extensions — strategically valuable.
-
Regulatory and reimbursement constraints differ significantly by product type. High-value differentiated products that deliver demonstrable clinical or economic value (e.g., reduced clinic visits, fewer antibiotic courses, or improved pediatric tolerability) retain stronger payer negotiating positions than incremental improvements in commodity drops.
-
Supply‑chain resilience for ophthalmic APIs is now table stakes. A concentrated API sourcing base for core molecules raises operational risk and necessitates contingency planning and supplier diversification for both branded and generic manufacturers.
Competitive landscape: implications for incumbents and challengers
The market exhibits moderate concentration: the leading three firms account for a meaningful share of value, and the top five control a clear majority of the market’s commercial heft. This structure creates both defensive advantages for incumbents and openings for focused challengers. Key dynamics include:
-
Established global players (e.g., companies with deep ophthalmic franchises and OTC/ Rx convergence) can leverage scale in distribution, clinical relationships, and regulatory experience to defend branded positions and accelerate new launches.
-
Specialty ophthalmology firms and innovative midsize players are the most likely sources of differentiated assets — whether novel molecules, biologics for severe allergic phenotypes, or device-integrated delivery systems. Strategic partnerships or licensing transactions with these players can be a rapid route to pipeline refreshment.
-
Large generics manufacturers and regional players are making the market more price-competitive at the base of the value chain, forcing branded companies to prioritize premium product segments and patient-centric differentiators.
Representative company positioning observed in our study:
-
Companies with established anti-allergy drops benefit from broad physician familiarity and strong retail presence, but face intensified generic erosion unless supported by new evidence or delivery innovations.
-
Firms active in anti-infectives continue to compete on speed of onset, preservative-free formulations, and cost-competitiveness — attributes that are decisive in acute care settings.
-
Specialty innovators focused on severe allergic conditions and novel delivery platforms are positioned to capture premium segments if they can secure favorable reimbursement and demonstrate measurable healthcare-system benefits.
Recent developments and strategic takeaways
-
Generic launches and approvals that expanded the availability of core anti-infectives increase the urgency for branded players to accelerate lifecycle programs and explore device differentiation or combination formulas.
-
Regulatory approvals for innovative formulations and new indications (including pediatric label extensions in select jurisdictions) create new commercial opportunities but also raise the bar for evidence generation and payer engagement.
-
Ongoing regulatory nuances — for example, procedural requirements associated with certain implants and pediatric insertion considerations — amplify the need for clinical training programs and tailored reimbursement strategies.
Recommended 2026 playbook
-
Prioritize portfolio triage: Identify high-return assets and deprioritize commodity lines unlikely to withstand intensified generic competition. Use our financial model to simulate outcomes under multiple pricing and market-access scenarios.
-
Invest selectively in delivery innovation: Intracanalicular inserts and extended‑release platforms can create durable differentiation. Evaluate partnership or acquisition targets that provide clinical credibility and rapid time-to-market.
-
Strengthen payer engagement: Develop dossiers that quantify system-level benefits (reduced clinic follow-ups, adherence-driven outcome improvements). Early engagement with key payers can materially improve market access timelines.
-
Secure API supply: Implement dual-sourcing strategies and contract manufacturing agreements to mitigate raw-material shortages and price volatility.
-
Adopt targeted M&A and licensing: Use bolt-on acquisitions to shore up gaps in therapeutic class coverage or to secure differentiated delivery technologies rather than broad, high-cost diversification.
How PW Consulting supports executive/action teams
-
Proprietary market and product models calibrated to real-world sales and launch evidence.
-
Rapid diligence packages for M&A screening, including red-team analysis and integration playbooks.
-
Regulatory and reimbursement route-mapping with bespoke payer evidence plans and KOL engagement strategies.
-
Commercial launch accelerators covering pricing, distribution, and specialist training programs tailored to ophthalmology stakeholders.
Our full Worldwide Conjunctivitis Ophthalmic Drugs Market report contains the granular, actionable data and the downloadable financial models necessary to execute the above recommendations. For senior teams preparing 2026 budgets, the report serves as both a tactical manual and a strategic scoreboard: it translates market momentum into high-confidence choices while preserving the detailed segment intelligence your teams require to operationalize those choices. To request the complete report, data tables, and a tailored briefing, please visit our publication page or contact PW Consulting’s Ophthalmology Practice.
For detailed analysis of this topic, please visit the official page: Worldwide Conjunctivitis Ophthalmic Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Ovum Egg Banking Market Valued at USD 5,464.34 Million in 2025, Poised to Reach USD 12,462.51 Million by 2032 at a 12.48% CAGR
By pmarketresearch, 2026-08-12
Worldwide Ovum Egg Banking Market — Strategic Imperatives for 2026
PW Consulting’s new market study, “Worldwide Ovum Egg Banking Market (Base year 2025; Forecast 2026–2032)”, synthesizes proprietary models, primary interviews and regulatory analysis to deliver a decision-grade briefing for executive teams preparing strategies for 2026. The ovum egg banking market has moved from a high-growth niche into mainstream strategic planning for fertility providers, employers and investors. Our macro modelling shows the market expanding from roughly USD 3.12 billion in 2020 to USD 5.46 billion in 2025, and, under our central scenario, accelerating to a multi‑billion-dollar industry by 2032 at a compound annual growth rate (CAGR) of 12.48% (USD million basis). This release highlights the report’s strategic value while deliberately withholding the granular segmented metrics that are available in the full study.
Red Cap Station Market
Why 2026 Matters: Regulatory, Clinical and Commercial Catalysts
-
Regulatory clarity and professional guidance have shifted the risk calculus. Updated positions from leading professional bodies in late 2025 and 2026 affirm planned oocyte cryopreservation as ethically permissible for reproductive planning and explicitly contextualize medical preservation for patients facing gonadotoxic therapy. These developments reduce ethical friction and support broader adoption by clinics and health systems.
Worldwide Anchor Windlass Market -
Reimbursement and coding regimes remain a complex but addressable barrier. Current procedural terminology includes codes for cryopreservation and thawing; however, donor egg acquisition and many storage costs are still predominantly out‑of‑pocket. Payer engagement strategies that target oncology mandates and employer-sponsored fertility benefits will be decisive for commercial scale.
Bioenergy with Carbon Capture and Storage Market -
Clinical evidence and real-world program outcomes are maturing. Leading clinics now report high-throughput freezing programs and growing numbers of live births from stored oocytes, translating to more predictable clinical success rates and better patient counseling — an essential commercial advantage for early movers.
-
Demand drivers are compounding: demographic trends, delayed family formation, increasing awareness of fertility preservation, and rising employer benefits are creating durable end-market expansion that rewards investment in patient experience, capacity and data-driven pricing.
How This Report Informs 2026 Decisions
Executives facing 2026 planning cycles require more than headline growth numbers — they need a roadmap that links market shape to executable moves. PW Consulting’s report provides that bridge through:
-
An accessible, auditable market model (USD million) covering historicals (2020–2025) and a detailed forecast to 2032, including high/low scenarios and sensitivity analyses that stress-test key assumptions.
-
Actionable go-to-market playbooks for clinic networks, dedicated cryobanks and integrated fertility platforms — including pricing levers, bundled service structures and differentiated service propositions (donor egg offerings vs. self-oocyte preservation).
-
A regulatory and reimbursement compass that maps coding, state-level fertility preservation mandates, and the practical implications of professional guidance for informed consent, marketing and payer contracting.
-
Commercial diligence assets: buyer/seller scorecards for M&A, an M&A heatmap identifying consolidation corridors, and a data room checklist for transaction readiness.
-
Operational toolkits: capacity planning templates for lab buildouts, quality and accreditation checklists, and a logistics/cold-chain risk register tailored to oocyte transport and cross-border distribution.
-
Patient journey diagnostics and digital engagement frameworks to increase conversion and lifetime value — from employer benefits enrollment to post-thaw clinical pathways and outcomes tracking.
Competitive Landscape — Who’s Competing and How
The market combines specialized cryobanks, national clinic networks and vertically integrated fertility groups. Key players covered in the report include specialized international banks, national leaders and clinic networks that operate both freezing programs and distribution channels. Representative companies profiled include Cryos International A/S (Denmark), California Cryobank (USA), Donor Egg Bank USA, ReproTech LLC, Cryo-Cell International Inc., CCRM Fertility, IVIRMA Global, Shady Grove Fertility, Kindbody, Genea Pty Limited, Boston IVF, Monash IVF Group, Fairfax EggBank and Extend Fertility.
Our competitive analysis shows a fragmented supplier base where specialization, service quality and geographic reach — rather than scale alone — drive premium positioning. Clinical credibility, validated outcomes and robust donor-matching technologies have emerged as differentiators. Organizations that combine laboratory excellence with superior digital patient experiences and strong clinician partnerships capture higher margins and stickier demand.
Market concentration metrics in the study underscore the fragmentation and the room for consolidation: a structure that still rewards well‑executed roll-up strategies, strategic partnerships with clinic networks, and white‑label service agreements for hospital systems.
Priority Strategic Plays for 2026
Based on our scenario modelling and interviews with payers, clinicians and operators, PW Consulting recommends the following priority actions for 2026:
-
Accelerate capacity with quality governance: invest selectively in lab capacity and quality systems that meet international accreditation standards. Build redundancy into cold‑chain logistics to prevent catastrophic losses and reputational damage.
-
Pursue targeted partnerships with oncology centres and employer benefit providers: embed oocyte preservation into clinical pathways and employer benefit packages to capture under‑served medical indications and voluntary uptake in working populations.
-
Differentiate through data and outcomes: develop registries and outcome dashboards that enable transparent counseling and support payer negotiations. Demonstrated live-birth outcomes will materially improve conversion rates and pricing power.
-
Consider roll-up and bolt-on acquisitions in fragmented regional markets: consolidation can deliver scale benefits in procurement, standardized quality and a branded donor database — but acquirers must prioritize integration of clinical protocols and regulatory compliance.
-
Design consumer-centric pricing and storage bundles: move from one-off storage fees toward subscription or outcome‑linked models where feasible, and pilot risk-sharing arrangements with high-volume clinic partners.
-
Embed ethical and compliance leadership: proactively adopt enhanced informed-consent protocols and transparent donor governance consistent with leading society guidance to reduce legal and reputational risk.
Risk Scenarios and Mitigation
Key downside scenarios we model include abrupt payer policy shifts that limit coverage for elective preservation, technological breakthroughs that accelerate obsolescence of existing storage methods, and heightened regulatory scrutiny around donor anonymity and cross-border distribution. Mitigation strategies include diversified revenue mixes that anchor medical indications, staged capex aligned to demand triggers, and active policy engagement to shape reimbursement pathways.
Practical Planning Timelines for 2026
-
0–6 months: validate demand via clinic pilots, align compliance and informed consent frameworks, and build a payer engagement plan focused on oncology mandates and employer benefits.
-
6–18 months: scale lab and cold-chain upgrades where demand is proven, roll out digital donor-matching and patient engagement platforms, and pilot innovative pricing models.
-
18–36 months: execute M&A or partnership strategies to consolidate regional strength, integrate outcomes registries for commercial differentiation, and expand cross-border distribution under robust governance.
What’s Behind the Numbers — Methodology Highlights
The report’s base year is 2025 and it leverages five years of historical data (2020–2025) to inform a forward forecast to 2032. Our model uses a bottom-up service taxonomy, triangulates utilization with demographic and oncology incidence trends, and applies scenario-based adoption curves to reflect regulatory and reimbursement uncertainty. All values are reported in USD (USD million unless otherwise noted). The study couples primary interviews with clinic operators, cryobank managers, payers and patient‑advocacy groups to test assumptions and to surface tactical barriers to scale.
Accessing the Full Intelligence
This article presents the strategic frame and actionable themes drawn from PW Consulting’s full market study, while intentionally withholding granular regional, service-type and end‑user splits that are included in the complete deliverable. The full report contains detailed segment-level models, company market shares, pricing matrices, and proprietary acquisition screening tools that senior leaders can deploy directly in 2026 planning cycles.
To obtain the full report or a tailored executive briefing for your organisation, contact PW Consulting’s Ovum Egg Banking practice. The comprehensive dataset and playbooks will enable investment committees, commercial heads and operational leaders to move from market awareness to implementation-ready programs as they plan for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Ovum Egg Banking Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com