

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Agricultural Automated Steering System Market Poised for 12.85% CAGR in 2026–2032 Forecast

Worldwide Agricultural Automated Steering System Market: Strategic Insights for 2026 Decision-Making
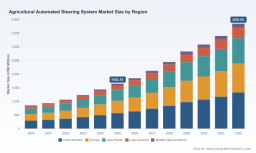
PW Consulting’s latest market study on the Worldwide Agricultural Automated Steering System market provides a compact but rigorous briefing designed to inform executive decisions in 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, the report synthesizes market sizing, technology trajectories, vendor positioning, and practical go-to-market playbooks. At the macro level the market demonstrates sustained expansion — growing from approximately USD 855 million in 2020 to roughly USD 1,652 million in 2025, and our modeled outlook projects an increase to about USD 3,851 million by 2032, representing a compound annual growth rate of 12.85% over the forecast period. This trajectory is accompanied by a moderately concentrated supplier base: the top three vendors account for roughly 54.3% of share and the top five for roughly 71.9% — a profile that creates both competitive barriers and consolidation opportunities.
Worldwide Asphalt Anti Strip Agent Market
Why this report matters for 2026 strategists
- Actionable, revenue-linked insight: The study does more than chart growth — it quantifies where value pools are forming and translates those pools into executable pathways for OEMs, Tier‑1 suppliers, distributors, and capital allocators.
- Operational levers prioritized: Cost-of-ownership dynamics, retrofit vs. factory-installed economics, and service-network imperatives are modeled to highlight near-term margin and adoption levers.
- Risk-aware scenario planning: Multiple adoption scenarios reflect sensitivity to regulatory shifts, RTK availability, and commodity-price-driven CAPEX cycles so organizations can stress‑test investment timelines.
What the report contains — practical, useable modules
- Market sizing and methodology: A transparent approach linking historical adoption (2020–2025) to 2026–2032 forecasts, with assumptions on technology substitution, price deflation curves, and service revenue potential.
- Demand-driver diagnostic: Farm economics, operator shortages, precision-agriculture adoption rates, and mechanization trends are modeled to show which farm segments will drive incremental purchases.
- Technology deep dives: Comparative analysis of GNSS/RTK, vision-based, and laser guidance approaches — covering technical performance, cost bands, integration complexity, and terrain/operation suitability.
- Go-to-market playbooks: Practical pathways for OEMs and retrofit suppliers covering channel selection, bundling strategies, financing and subscription models, and dealer enablement templates.
- Commercial models and ROI tools: Build-your-own calculators and sensitivity matrices demonstrating payback timelines under different crop values, operation intensities, and accuracy levels.
- Regulatory and standards radar: Assessment of current and emerging regulatory dynamics that affect operations, spectrum/GNSS policy exposure, and safety/ liability considerations for autonomation features.
- Competitive positioning: Scorecards, partner-fit matrices, and capability maps for leading vendors — enabling immediate benchmarking and M&A screening.
- Implementation playbooks: Field-trial design, fleet‑scale roll-out sequencing, training curricula for dealers and operators, and service logistics optimization.
Competitive landscape: Who matters and why
The market is anchored by a combination of large global OEMs and specialist technology providers. Our assessment identifies a mix of vertically integrated manufacturers and adaptable tech suppliers — each with distinct routes to market and competitive strengths.
Worldwide Activated Alumina Sorbent Market
- John Deere (Moline, Illinois) — A vertically integrated leader offering an OEM-level automated steering platform that emphasizes systems integration, display ecosystems, and proprietary GNSS augmentation. Its value lies in deep OEM integration and dealer network reach.
- Trimble Agriculture (PTx Trimble) (Westminster, Colorado) — A technology-first supplier whose Autopilot platform supports hydraulic and motor-drive configurations and broad OEM and retrofit compatibility, making it a frequent partner for both OEMs and aftermarket players.
- CNH Industrial (Case IH / New Holland) (UK) — Combines factory-installed guidance with retrofit options, balancing brand-led customer trust with cross‑brand technology adoption through their AFS and IntelliSteer lines.
- AGCO (including Fendt) (Duluth, Georgia) — Focused on integrating guidance into its brand portfolio while leveraging partnerships and compatibility with major technology platforms to deliver precision guidance at scale.
- Topcon Agriculture (Livermore, California) — A specialist in guidance systems known for making autosteering more accessible to mid-market tractors; recent product activity demonstrates a deliberate push to expand the addressable retrofit and mid-range segments.
- CHCNAV (Shanghai) — A fast-moving entrant that emphasizes RTK-level accuracy and multi‑GNSS support, offering competitive pricing and rapid global expansion from a China base.
- Ag Leader Technology (Ames, Iowa) — A focused player delivering integrated steering systems with an emphasis on compatibility with precision displays and year‑round machine control.
- FJDynamics (Shenzhen) — A provider concentrating on RTK-level performance and terrain compensation, targeting broad compatibility for tractors and specialized agricultural machinery.
- Raven Industries (CNH affiliate), CLAAS, Kubota — Each brings unique strengths: Raven with precision-control systems, CLAAS with OEM integration in harvesting platforms, and Kubota with scale in certain geographic and mechanization segments.
Collectively, these profiles make clear that competitive advantage will increasingly derive from combination offers — hardware + connectivity + services — and from channel depth rather than hardware differentiation alone.
Online Transformerless UPS Market
Recent industry dynamics shaping 2026 choices
- Product activity in 2025 shows vendors moving to broaden access: for example, new “value line” autosteering solutions target mid-range tractors and smaller farms, lowering the entry threshold for precision guidance.
- High-accuracy systems with RTK-level performance are now widely available from multiple vendors, increasing competitive pressure on price and pushing differentiation toward service, UX, and integration.
- Adoption snapshots indicate meaningful penetration in midsize and large farms — a structural tailwind that translates into a steady replacement and retrofit market, especially where operator shortages and efficiency pressures are acute.
- Field-level benefits — reduced overlap, lower operator fatigue, and extended operating windows — continue to be validated in productivity studies, strengthening the operational case for investment.
Strategic implications and recommended moves for 2026
- For OEMs: Prioritize platform openness with clear upgrade paths. Maintain capture of factory-installed revenue while enabling retrofit-friendly interfaces to address farmers who delay full fleet replacement.
- For aftermarket and tech vendors: Focus on modular solutions that reduce integration friction and on dealer training programs that shorten time-to-value in the field. Consider subscription pricing for positioning recurring revenue streams.
- For distributors and dealers: Invest in service capability and financing options. The purchasing decision is often more about risk mitigation and uptime than sticker price.
- For investors: Look for assets that combine hardware with data and service moats — companies that can monetize recurring GNSS corrections, software updates, and fleet analytics will command premium multiples.
- For policymakers and extension services: Encourage trials and co-funded pilots that de‑risk adoption for smallholders and midsize farms, and support spectrum and GNSS policy that stabilizes RTK availability.
Where this report acts as a strategic tool
Leaders who need to set 18–36 month investment priorities will find this report particularly practical. It turns market momentum into prioritized actions: where to allocate R&D spend, how to sequence product roll-outs, what dealer competencies to build, and which partnership archetypes deliver rapid scale. Our scenario models allow executives to map capital deployment to expected payback under conservative, base, and accelerated adoption cases.
Confidentiality of granular splits — and how to access them
In line with our “trailer” approach, this briefing surfaces the high‑value implications and the strategic narrative you need to act in 2026, while reserving detailed segment breakdowns, regional and application-level revenue tables, and granular vendor share matrices for the full report. That granular data underpins the actionable playbooks and ROI calculators referenced above; organizations that require immediate operationalization of those insights should review the full dataset and appendix.
Next steps
- Download the full report to obtain the segmented datasets, vendor scorecards, and financial models that support the recommendations summarized here.
- Schedule a capability workshop with PW Consulting to translate these insights into a 12–24 month commercial plan, including pilot design and dealer enablement roadmaps.
PW Consulting’s Worldwide Agricultural Automated Steering System market study is designed to convert market momentum into measurable advantage. For strategy teams preparing capital allocations, partnership roadmaps, or go-to-market plans in 2026, the report provides a concise, evidence-based foundation that bridges market sizing, competitive realities, and field-level execution.
For detailed analysis of this topic, please visit the official page: Worldwide Agricultural Automated Steering System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com