

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Cupping Therapy Kits Market Poised for 5.8% CAGR in 2026–2032

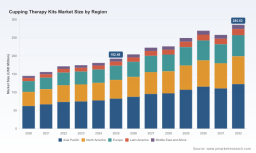
Worldwide Cupping Therapy Kits Market: Strategic Preview for 2026 Decision-Makers
Executive snapshot
As PW Consulting’s senior industry analyst, I present a guided preview of our newest market research — the Worldwide Cupping Therapy Kits Market report (base year 2025). This briefing highlights the strategic signals that matter for boardrooms, corporate strategy teams, and private investors planning moves in 2026. It demonstrates the report’s practical value without disclosing the full, proprietary segmentation tables and financial matrices reserved for the full publication.
Mini LiDAR Market
Why this market matters in 2026
Cupping therapy kits sit at the intersection of traditional medicine, consumer wellness, and clinical rehabilitation. After recovering from early-pandemic volatility, the global market expanded from an estimated USD 145.2 Million in 2020 to USD 192.48 Million in 2025. Under the conservative scenarios modeled in our forecast, the market continues to grow through the 2026–2032 window at a compound annual growth rate (CAGR) of 5.8%, reaching an expected market size above USD 285 Million by 2032.
Worldwide Journal Software Market
That trajectory is meaningful for three categories of decision-makers:
Canopy Light Market
- Manufacturers seeking scale efficiencies and product differentiation
- Distributors and service providers building integrated recovery suites
- Healthcare institutions and payors evaluating inclusion in care pathways
Market dynamics shaping 2026 strategies
Our sector analysis identifies five converging dynamics companies must internalize before committing capital:
- Product innovation and material evolution: Manufacturers are diversifying from traditional glass cups into silicone, thermoplastic and hybrid systems that prioritize safety, durability, and user comfort. Innovations in pump ergonomics, magnetic attachments, and shock/heat-resistant materials are enabling broader clinical adoption and home-use positioning.
- Clinical integration and reimbursement signals: Cupping therapy is increasingly embedded within rehabilitation and pain-management protocols. Industry billing practices reference existing physical-medicine CPT codes in certain settings, and institutional purchasers (including public health systems) are evaluating reimbursement pathways — a trend that materially affects procurement strategies for clinics and device suppliers.
- Regulatory clarity and standards: Cupping kits continue to be regulated predominantly as Class I medical devices in major markets, with relevant ISO standards for air-extraction and glass cupping devices in place. This creates a baseline compliance expectation but also opens opportunities for early movers who obtain voluntary quality certifications and robust clinical claims.
- Channel and education ecosystem: Sellers that bundle education (continuing education units, practitioner training) with product offerings are winning higher retention and premium pricing, especially in practitioner-targeted segments.
- Fragmented competitive structure: Market concentration remains low relative to many medical-device subsegments. Our concentration indices indicate a fragmented supplier base, creating opportunity for consolidation and for specialized incumbents to capture niche premium roles.
What the PW Consulting report delivers — practical, actionable content
This study was built to guide real-world decisions. The full report includes:
- Detailed market sizing and trend validation (historical 2020–2025 and modeled forecasts 2026–2032), with sensitivity scenarios and upside/downside drivers.
- Proprietary forecast model delivered in Excel, enabling users to re-run scenarios after adjusting pricing, adoption curves, or regulatory assumptions.
- Supply chain maps and cost-driver analysis from raw materials to finished-packaging decisions, including labor, logistics, and tooling considerations.
- Channel and commercialization playbooks for clinic, sports-rehab, and direct-to-consumer (D2C) routes to market — including pricing benchmarks, bundling strategies, and education-led retention models.
- Regulatory and reimbursement navigators: step-by-step compliance checklists for major markets, ISO alignment guidance, and payer engagement briefs for institutional sales teams.
- Customer segmentation frameworks and buyer-persona profiles tailored to practitioners, physiotherapists, and informed consumers who buy at-home kits.
- Strategic M&A and partnership screening matrix highlighting target profiles for tuck-ins, technology acquisitions, and distribution alliances.
- Risk matrices, mitigation options, and contingency plans for supply shocks, regulatory shifts, and reputational risks related to clinical safety concerns.
- Primary interview insights: synthesized perspectives from practitioners, procurement officers, and senior product managers collected during our 2025–2026 fieldwork.
Competitive landscape — who to watch and why
The market features a mix of established equipment producers, specialized silicone and glass manufacturers, and distributors bundling education and clinical services. The landscape’s fragmentation, reflected in modest top-three and top-five concentration ratios, leaves room for brand differentiation and vertically integrated models.
- EarthSpa R&D (United States) — Known for handblown glass and in-house plastic pump systems, EarthSpa’s positioning centers on ’made-in’ quality and practitioner trust. Expect continued focus on premium clinical channels and design-protected products.
- Lhasa OMS (United States) — A diversified supplier with product lines spanning silicone, glass, and magnetic offerings; appeals to licensed acupuncturists and integrative health clinics via combined product-and-education programs.
- HawkGrips (United States) — Emphasizes dynamic cupping for sports recovery and clinical CEU-backed programs; a playbook for companies seeking to monetize education alongside hardware.
- Thysol US / FASCIQ (United States) — Targets fascia and massage therapy markets with premium silicone solutions; strong channel affinity with manual-therapy professionals.
- Kangzhu (China, via Taizhou Xinkang) — Original maker of classically engineered plastic vacuum systems and pumps; cost-competitive manufacturing with regulatory credentials in markets requiring Class I registration.
- Boen Medical (China) — Glass cupping specialist positioned for scale; relevant to buyers prioritizing traditional materials and lower-cost clinical inventories.
- MMT Cupping, Cupping International, Performance Health and others — A diverse group of suppliers and distributors that combine product breadth, clinical distribution networks, and rehabilitation-focused kits.
Recent product moves underline the market’s dual emphasis on performance and home-wellness adoption. Notable developments in 2025–2026 include expanded integrated recovery kits for physiotherapy, new ergonomic professional pumps, and refreshed silicone/magnetic product waves across Asia-Pacific. These moves validate our hypothesis that packaging, training, and system-level integration are as important as cup design itself.
Strategic implications: six priority actions for 2026
Based on our modeling and field interviews, companies should prioritize the following:
- Clarify target customer economics: Build P&L models for practitioner bundles versus D2C offerings; quantify lifetime value differences driven by recurring consumables and training revenues.
- Invest in validated clinical evidence: Short, focused clinical studies and documented case series will materially accelerate institutional adoption and payer conversations.
- Design supply resilience into product roadmaps: Dual-source critical components, standardize materials to reduce regulatory complexity, and consider regional assembly to shorten lead times.
- Differentiate through services: Offer CEU-accredited training, digital rehabilitation protocols, and telehealth-enabled onboarding to capture higher-margin accounts.
- Pursue pragmatic M&A and partnerships: Target acquisitions that fill distribution gaps, add clinical evidence capacity, or incorporate complementary modalities for integrated recovery kits.
- Prepare for regulatory and reimbursement evolution: Invest in compliance documentation, ISO alignment, and payer-engagement templates to move quickly if CPT coding and benefits change regionally.
How PW Consulting’s report accelerates execution
For strategy teams, the full report is a decision-enabler rather than an academic exercise. The integrated Excel model lets executives test: (a) price-elasticity in home versus professional channels; (b) the impact of unit-cost reductions from regional manufacturing; and (c) the ROI of bundling training with hardware. Our M&A screening tool surfaces targets aligned to four acquisition archetypes (scale, capability, channel, and technology) and ranks them against five execution risks.
Closing perspective and next step
The Worldwide Cupping Therapy Kits Market is moving from niche therapeutic practice toward broader clinical and consumer adoption. The path to 2026 is navigable for organizations that act now: solidify clinical credibility, build resilient supply and manufacturing strategies, and monetize services around hardware. Fragmentation creates opportunity — for first movers who integrate product, education, and clinical partnerships, and for investors seeking consolidation opportunities.
To access the full dataset, segmented forecasts, valuation matrices, and the downloadable forecast model, visit the PW Consulting report page. The detailed splits and proprietary financials are intentionally reserved for the comprehensive report to preserve client value and enable confident execution planning.
For detailed analysis of this topic, please visit the official page: Worldwide Cupping Therapy Kits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com