

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts 20.15% CAGR for Worldwide Autologous Cell Therapy Market, Signaling Rapid Expansion Through 2032

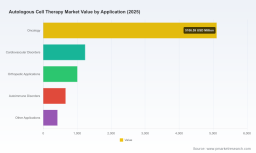
PW Consulting Release: Strategic Brief — Worldwide Autologous Cell Therapy Market (Base Year 2025)
PW Consulting today publishes an executive industry brief accompanying our full report, Worldwide Autologous Cell Therapy Market. Designed as a strategic “trailer” for C-suite and deal teams preparing for 2026 decision cycles, this briefing explains why autologous cell therapies will remain a high-growth, high-complexity sector — and how senior executives should prioritize investments, partnerships, and operational choices in the year ahead. For organizations that require the underlying, transaction-grade data and granular regional, application and source splits, the full report contains the complete dataset, modelling files, and playbooks.
Worldwide Social Login Tool Market
Why this market matters to 2026 strategy
The autologous cell therapy market has transitioned from niche clinical promise to commercial reality over the past half-decade. At the macro level, PW Consulting’s model shows a market that expanded markedly from the early 2020s and reached USD 8,426.12 Million (revenue unit: Million USD) in 2025 (base year). Our forecast indicates continued robust expansion into the next decade, with the market projected to exceed USD 10,035.55 Million in 2026 and reach USD 30,457.48 Million by 2032. This trajectory corresponds to a compound annual growth rate (CAGR) of 20.15% across the 2026–2032 forecast window — a profile that places autologous approaches among the fastest-growing segments in advanced therapeutics.
Mobile and Portable MRI Scanner Market
High growth plus concentrated supplier dynamics (our concentration analysis indicates a CR3 of 38.5% and a CR5 of 52.1%) creates both opportunity and risk. Market leaders capture meaningful commercial rents, yet there remains substantial room for new entrants with differentiated manufacturing, logistics, or clinical differentiation to disrupt the incumbency.
Worldwide Regulating Human Health Beverage Market
What PW Consulting’s report delivers — practical, decision-focused content
- Actionable market sizing and scenarios : Transparent methodology and stress-tested scenarios for 2026–2032 to support capital allocation, portfolio prioritization, and M&A valuation assumptions. The report includes base, upside and downside demand pathways tied to regulatory and reimbursement inflection points.
- Commercial-readiness playbooks : Step-by-step recommendations for field launches, phased market entry, and payer engagement — including model term-sheets for value-based and outcomes-linked reimbursement pilots.
- Supply chain and manufacturing assessment : Deep-dive on cost drivers, batch economics and scalable processing strategies — from decentralized point-of-care models to regional centralized facilities — plus a vendor matrix for automation, single-use systems and cold-chain partners.
- Regulatory and quality roadmap : Comparative analysis of FDA, EMA and key APAC regulators’ expectations for CMC, cGMP/cGTP compliance, and donor screening where applicable. Includes timelines and checklist templates for audit readiness.
- Pipeline and clinical risk tracker : Live table of late-stage autologous programs, anticipated regulatory milestones and probability-weighted timelines to commercialization — facilitating portfolio reprioritization and partnering decisions.
- Competitive & partnership playbook : Profiles of incumbent and emerging players, commercial strategies, vertical-integration options, and best-practice alliances between developers, CDMOs, and health systems.
- M&A and licensing intelligence : Deal comps, enterprise valuation sensitivities, and an M&A heat map identifying the most attractive capability gaps to fill through acquisition.
Operational dynamics and the business implications for 2026
- Manufacturing economics are decisive : Autologous processes remain inherently high-cost on a per-patient basis. Our sector synthesis finds production cost drivers (facility footprint, specialized labor, reagents, and one-batch-per-patient processing) often driving per-dose manufacturing expenses into a high five-figure range. For 2026 planning, executives must stress-test capital allocation between automation investments that reduce variable labor intensity versus outsourcing to CDMOs with mature patient-flow throughput.
- Logistics and cold-chain management are strategic : Time-sensitive patient-to-facility-to-patient flows magnify operational risk. Companies expanding geographically should prioritize redundant transport corridors, validated cryo-logistics vendors, and localized contingency capacity to protect time-to-treat windows.
- Reimbursement frameworks are evolving but remain a gating factor : Payers continue to demand outcome-linked models. Firms launching in 2026 should secure early payer dialogue, invest in real-world evidence infrastructure, and be prepared to pilot bundled or annuity payment models where clinical durability supports it.
- Regulatory diligence reduces launch risk : CMC and facility compliance issues are frequent causes of launch delays. Organizations targeting 2026 approvals must front-load regulatory interactions and ensure CMC packages and process validation studies are aligned with anticipated agency expectations.
Competitive landscape — strategic takeaways on core players
The marketplace is populated by global pharmaceutical leaders, dedicated cell therapy developers, and specialized biotechs. Our competitive analysis synthesizes capabilities, commercialization models, and near-term catalysts for the most consequential players:
- Novartis AG — A proven first-mover with commercial experience in autologous CAR-T. Novartis’s strengths lie in integrated commercialization, payer contracting experience and scalable manufacturing know-how. For competitors, Novartis sets the benchmark for post-launch support and provider engagement models.
- Gilead Sciences (Kite) — A dominant commercial engine for CAR-Ts with strategic appetite for portfolio diversification; recent M&A moves and late-stage filings indicate continued expansion in blood-cancer indications. Their deal-making posture makes them a natural partner or acquirer for high-quality BCMA or next-generation CAR portfolios.
- Bristol-Myers Squibb — Combines large oncology sales infrastructure with targeted cell therapy assets. BMS’s integration focus favors therapies that can be lodged within existing oncology pathways and benefit from cross-selling synergies.
- Johnson & Johnson (Janssen/Legend) — Positions itself on the multiple-myeloma and specialty-care axis; leverages deep hospital relationships and commercial scale to optimize uptake in complex inpatient and outpatient settings.
- Vertex — Demonstrates the value of gene-editing platform leverage in autologous cell therapy, with potential to expand into other monogenic conditions. Vertex’s regulatory and manufacturing rigor is an exemplar for companies seeking premium valuation multiples.
- bluebird bio, Vericel, Iovance, Autolus — Represent specialist developers with domain expertise in ex vivo gene-modified cells, tissue-engineered autologous products, and TIL or CAR constructs. These companies are potential consolidation targets or partners for commercial roll-out support.
- Notable regionals (e.g., Pharmicell, Holostem, ProKidney) — While smaller in scale, these organizations illustrate the clinical breadth of autologous approaches and the geographic diffusion of capability, particularly for localized indications and rare-disease niches.
For deal teams, the strategic lens should be: does the target add a clinical differentiation, a manufacturing or logistics advantage, or a payer-proven evidence package? Those three levers most directly compress commercialization timelines and derisk pricing negotiations.
Recent industry developments shaping 2026 strategy
- Late-breaking clinical and commercial preparations : 2025–2026 data readouts and leadership appointments highlight an industry moving from development to scale. Examples include late-breaking echocardiography data indicating potential cardiac remodeling benefits in ischemic heart failure, and companies appointing commercialization leadership ahead of expected launches — signals that an expanding set of indications is approaching commercial inflection.
- M&A and regulatory milestones : Ongoing acquisition activity and high-stakes Biologics License Application acceptances are compressing windows for strategic responses. Expect heightened valuation volatility around positive BLA outcomes and successful PDUFA decisions.
- Comparative clinical performance : New data demonstrating parity between innovative gene-edited or next-generation CAR constructs and established autologous CAR-T programs are likely to shift competitive dynamics, enabling nimble entrants to capture premium access if they can align manufacturing capacity with launch timing.
Three strategic recommendations for executives planning 2026
- Prioritize manufacturing modularity : Move capital decisions toward flexible, semi-automated systems that shorten changeover times and reduce per-patient labor. Consider dual-sourcing critical reagents and contracting with accredited CDMOs as a near-term hedge.
- Invest in evidence generation and payer partnerships : Allocate budget to registry infrastructure and early outcomes agreements. Demonstrating durable benefit will unlock broader reimbursement and justify higher list prices in value propositions tied to avoided downstream costs.
- Adopt a ‘selective scale’ commercialization cadence : Launch in high-yield centers of excellence with controlled capacity scaling tied to demonstrated referral flows and logistic performance. This reduces the risk of launch overspend and protects unit economics while adoption pathways mature.
Conclusion — why PW Consulting’s intelligence is decision-critical for 2026
Autologous cell therapies present a rare combination: rapid market expansion (projected to cross the ten-billion-dollar threshold in 2026) and operational complexity that penalizes poor execution. The market’s 20.15% CAGR through 2032 reinforces why boardrooms must move decisively — yet with a risk-managed playbook that addresses manufacturing, logistics, reimbursement, and regulatory realities. PW Consulting’s full report provides the granular segmentation, regional and application breakdowns, and financial models necessary to make those decisions with confidence.
To review the comprehensive datasets, validation tables, company scorecards, and downloadable modelling workbooks that underpin these findings, please consult the full Worldwide Autologous Cell Therapy Market report available through PW Consulting’s report portal.
For detailed analysis of this topic, please visit the official page: Worldwide Autologous Cell Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com