

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Conjunctivitis Ophthalmic Drugs Market Valued at USD 5,466.5 Million in 2025, Poised for Further Growth

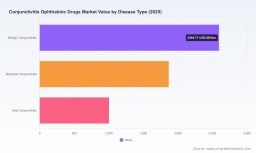
Worldwide Conjunctivitis Ophthalmic Drugs Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market intelligence on the Worldwide Conjunctivitis Ophthalmic Drugs Market synthesizes multi-year observed performance with scenario-driven forecasts to 2032. Our analysis shows a resilient expansion of the overall market from just over USD 4.2 billion in 2020 to USD 5.47 billion in 2025, with a continued upward trajectory across the 2026–2032 forecast window. The market’s compound annual growth rate (CAGR) over the forecast period stands at 5.51%, underpinned by persistent demand in allergic and infectious indications, product innovation, and an evolving competitive and regulatory landscape.
Worldwide Scanning Lenses Market
Why this report matters for 2026 strategy
-
Actionable foresight: We translate broad-market momentum into discrete strategic options that are executable within 12–24 months — from lifecycle management and portfolio prioritization to targeted M&A and market-entry sequencing.
RV Backup Power System Market -
Investment prioritization: The report frames where to allocate R&D and commercial resources to capture disproportionate value as category dynamics shift (e.g., branded innovation vs. generic displacement, novel delivery forms vs. traditional drops).
Worldwide Ball Joints Market -
Risk calibration: We quantify systemic exposures — regulatory timing, reimbursement hurdles, and API supply constraints — and map mitigation levers correlated with upside scenarios.
Report scope and practical contents
-
Market sizing and trend analysis: Year-on-year market sizing from 2020 through 2025, with forward projections through 2032. Our models reconcile historical sales, launch trajectories, and expected therapeutic substitution dynamics to produce base, upside, and downside cases.
-
Competitive benchmarking: Detailed company profiles, commercial footprint assessments, and capability matrices covering global innovators, specialty ophthalmology firms, and major generic/contract manufacturers.
-
Clinical and pipeline intelligence: Assessment of late‑stage assets, delivery technologies (including ocular inserts and intracanalicular systems), and the potential commercial impact of recently approved or launched products.
-
Regulatory, reimbursement & payer playbook: Jurisdiction-specific timelines and reimbursement sensitivities, plus recommended dossier content and real‑world evidence strategies to accelerate formulary access.
-
Go‑to‑market blueprints: Channel segmentation, clinician and patient adoption drivers, and tactical launch plans calibrated to diverse healthcare systems.
-
Commercial financial models: Scenario-ready revenue models and margin stress tests designed for M&A diligence, licensing negotiations, and internal capital allocation.
Note: In this briefing we present high-level conclusions and strategic guidance. The full report contains granular segment tables, country-level forecasts, product-level unit and value estimates, and downloadable financial models — access details are provided at the end of this release.
Market dynamics shaping 2026 decisions
-
Innovation in delivery formats is changing the clinical and commercial calculus. Intracanalicular inserts and long-acting formulations continue to gain attention for their adherence benefits, especially in allergic indications where episodic symptoms and patient compliance have historically limited therapeutic impact.
-
Genericization remains a major force. The recent acceleration of generic ophthalmic launches amplifies pricing pressure for established branded drops and shortens the effective exclusivity period for commodity anti-infectives and anti-allergy agents. This dynamic makes early lifecycle actions — such as formulation improvements, device-enabled delivery, and line extensions — strategically valuable.
-
Regulatory and reimbursement constraints differ significantly by product type. High-value differentiated products that deliver demonstrable clinical or economic value (e.g., reduced clinic visits, fewer antibiotic courses, or improved pediatric tolerability) retain stronger payer negotiating positions than incremental improvements in commodity drops.
-
Supply‑chain resilience for ophthalmic APIs is now table stakes. A concentrated API sourcing base for core molecules raises operational risk and necessitates contingency planning and supplier diversification for both branded and generic manufacturers.
Competitive landscape: implications for incumbents and challengers
The market exhibits moderate concentration: the leading three firms account for a meaningful share of value, and the top five control a clear majority of the market’s commercial heft. This structure creates both defensive advantages for incumbents and openings for focused challengers. Key dynamics include:
-
Established global players (e.g., companies with deep ophthalmic franchises and OTC/ Rx convergence) can leverage scale in distribution, clinical relationships, and regulatory experience to defend branded positions and accelerate new launches.
-
Specialty ophthalmology firms and innovative midsize players are the most likely sources of differentiated assets — whether novel molecules, biologics for severe allergic phenotypes, or device-integrated delivery systems. Strategic partnerships or licensing transactions with these players can be a rapid route to pipeline refreshment.
-
Large generics manufacturers and regional players are making the market more price-competitive at the base of the value chain, forcing branded companies to prioritize premium product segments and patient-centric differentiators.
Representative company positioning observed in our study:
-
Companies with established anti-allergy drops benefit from broad physician familiarity and strong retail presence, but face intensified generic erosion unless supported by new evidence or delivery innovations.
-
Firms active in anti-infectives continue to compete on speed of onset, preservative-free formulations, and cost-competitiveness — attributes that are decisive in acute care settings.
-
Specialty innovators focused on severe allergic conditions and novel delivery platforms are positioned to capture premium segments if they can secure favorable reimbursement and demonstrate measurable healthcare-system benefits.
Recent developments and strategic takeaways
-
Generic launches and approvals that expanded the availability of core anti-infectives increase the urgency for branded players to accelerate lifecycle programs and explore device differentiation or combination formulas.
-
Regulatory approvals for innovative formulations and new indications (including pediatric label extensions in select jurisdictions) create new commercial opportunities but also raise the bar for evidence generation and payer engagement.
-
Ongoing regulatory nuances — for example, procedural requirements associated with certain implants and pediatric insertion considerations — amplify the need for clinical training programs and tailored reimbursement strategies.
Recommended 2026 playbook
-
Prioritize portfolio triage: Identify high-return assets and deprioritize commodity lines unlikely to withstand intensified generic competition. Use our financial model to simulate outcomes under multiple pricing and market-access scenarios.
-
Invest selectively in delivery innovation: Intracanalicular inserts and extended‑release platforms can create durable differentiation. Evaluate partnership or acquisition targets that provide clinical credibility and rapid time-to-market.
-
Strengthen payer engagement: Develop dossiers that quantify system-level benefits (reduced clinic follow-ups, adherence-driven outcome improvements). Early engagement with key payers can materially improve market access timelines.
-
Secure API supply: Implement dual-sourcing strategies and contract manufacturing agreements to mitigate raw-material shortages and price volatility.
-
Adopt targeted M&A and licensing: Use bolt-on acquisitions to shore up gaps in therapeutic class coverage or to secure differentiated delivery technologies rather than broad, high-cost diversification.
How PW Consulting supports executive/action teams
-
Proprietary market and product models calibrated to real-world sales and launch evidence.
-
Rapid diligence packages for M&A screening, including red-team analysis and integration playbooks.
-
Regulatory and reimbursement route-mapping with bespoke payer evidence plans and KOL engagement strategies.
-
Commercial launch accelerators covering pricing, distribution, and specialist training programs tailored to ophthalmology stakeholders.
Our full Worldwide Conjunctivitis Ophthalmic Drugs Market report contains the granular, actionable data and the downloadable financial models necessary to execute the above recommendations. For senior teams preparing 2026 budgets, the report serves as both a tactical manual and a strategic scoreboard: it translates market momentum into high-confidence choices while preserving the detailed segment intelligence your teams require to operationalize those choices. To request the complete report, data tables, and a tailored briefing, please visit our publication page or contact PW Consulting’s Ophthalmology Practice.
For detailed analysis of this topic, please visit the official page: Worldwide Conjunctivitis Ophthalmic Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com