

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide MRI-Compatible IV Infusion Pumps Market Poised for 8.6% CAGR (2026–2032)

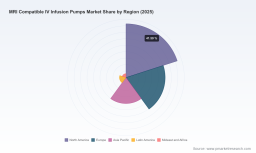
Worldwide MRI Compatible IV Infusion Pumps Market — Strategic Imperatives for 2026
PW Consulting today releases a strategic industry briefing accompanying our full market research report on the Worldwide MRI Compatible IV Infusion Pumps Market. Built for executive teams, corporate development functions, and health system procurement leaders, this briefing distills why 2026 will be a pivotal year for competitive positioning, capital allocation, and regulatory strategy in a market that is accelerating toward clinical mainstreaming.
Worldwide Linear Ultrasound Transducers Market
Snapshot: A market maturing at commercial and clinical frontiers
Our analysis uses 2025 as the base year and models the market through 2032. The global market for MRI-compatible IV infusion pumps—measured in USD millions—grew from USD 312.45 Million in 2020 to USD 465.00 Million in 2025. Under our central scenario, the market continues to expand at a compound annual growth rate (CAGR) of 8.6% across the forecast window (2026–2032), reaching an estimated USD 828.44 Million by 2032. This trajectory reflects a convergence of clinical demand, regulatory clarity, and targeted procurement programs that together lower barriers to in-scanner infusion therapy.
Worldwide Handwritten Notes Software Market
What is driving the next phase of adoption?
- Clinical demand for simultaneous imaging and therapy: Increasing MRI throughput, advanced interventional MRI workflows, and growth in pediatric/neonatal imaging heighten the clinical value of infusion devices that can safely operate in high-field environments.
- Regulatory and procurement tailwinds: Recent regulatory clearances and public procurement decisions recognizing non-magnetic solutions are creating reference cases that shorten the approval pathway and buying cycles for early adopters.
- Product innovation unlocking new use cases: Advances in non-magnetic drive systems (including ultrasonic motors), integrated drug libraries, wireless control interfaces, and systems-level shielding are shifting the value conversation from “if” to “how” to use infusion pumps in and around the MRI bore.
- Capital planning and replacement cycles: Hospital capital planning frameworks and useful-life benchmarks—commonly applied in the sector—are prompting refresh cycles in 2026 for infusion hardware purchased in the previous decade, creating demand windows for vendors with robust total-cost-of-ownership (TCO) propositions.
Regulatory and procurement context — why 2025–2026 matter
Two regulatory facts have immediate strategic implications. First, the FDA’s 510(k) pathway for MRI-compatible infusion pumps remains the primary route to U.S. market access; recent clearances demonstrate the agency’s expectations for device performance and human factors evidence. Second, public-health procurement authorities are increasingly willing to recognize unique clinical needs through sole-source or specialized procurement justifications when a truly non-magnetic solution is demonstrably unique.
Cold Atom Gravimeter Market
For market entrants and incumbents alike, the practical consequence is that a well-executed regulatory dossier (with strong human factors and clinical validation) plus targeted reference deployment can materially shorten sales cycles and support premium pricing—if supported by demonstrable patient-safety and workflow benefits.
Competitive landscape: consolidation, niche leadership, and product differentiation
The MRI compatible infusion pump market is highly concentrated, with the top three players commanding the vast majority of commercial revenues and the top five extending that dominance further. This concentration reflects significant technical barriers—validated non-magnetic actuation, MRI safety testing up to high gauss levels, and documented clinical workflows—that favor specialized suppliers and established infusion-platform vendors able to invest in certification and field support.
Key vendor archetypes identified in our report:
- Specialist non-magnetic innovators — Companies focused specifically on MRI-safe pump platforms have technological and regulatory advantages in the in-bore and near-bore use cases. Recent product clearances from such specialists create important commercial references.
- Large infusion-platform incumbents — Global infusion manufacturers leverage wide hospital footprints and integrated infusion management systems to sell MRI-aware solutions as part of broader therapy bundles.
- System integrators and shielding suppliers — Vendor solutions that pair infusion pumps with shielded carts or dedicated MRI-room platforms are establishing differentiated value propositions for complex multi-pump workflows.
Representative firms covered in the report include specialized innovators headquartered in the United States with cleared MRI offerings, legacy infusion systems vendors with MRI-compatible variants, and European and North American manufacturers offering integrated shielding solutions. Recent milestones in the competitive set—the granting of a 510(k) clearance for a next-generation non-magnetic pump system in May 2025 and a subsequent sole-source procurement intent from a major U.S. healthcare purchaser in early 2026—illustrate how regulatory milestones can immediately translate into procurement advantages for niche leaders.
Strategic implications for corporate decision-makers in 2026
As organizations plan priorities for 2026, the report highlights concrete actions across four decision vectors: product strategy, commercial go-to-market, regulatory and clinical evidence, and corporate development.
- Product strategy: Invest in non-magnetic actuation, robust drug libraries, intuitive wireless control, and modular shielding options. Prioritize human factors engineering early in development to de-risk 510(k) submissions and to shorten time-to-reference sites.
- Commercialization & partnerships: Forge alliances with imaging OEMs, MRI-focused systems integrators, and high-volume imaging centers. Design bundled offers that address workflow friction points—cabinetized carts, centralized monitoring, and MRI-safe tubing management—rather than standalone pumps alone.
- Regulatory & clinical evidence: Allocate budget to pre-market studies that align with FDA Total Product Life Cycle expectations and establish early clinical references in academic centers able to publish outcomes. These references accelerate adoption among health systems and support higher reimbursement or procurement prioritization.
- Corporate development: For incumbents seeking rapid capability upgrades, targeted acquisitions or minority investments in specialist non-magnetic pump makers can be a faster route to validated technology and installed-clinic references than greenfield R&D.
Risk matrix: what keeps CFOs and CPOs awake at night?
- Regulatory delay risk: Complex human factors expectations and the need for MRI-specific safety testing can extend approval timelines if not anticipated.
- Procurement variability: Differences in public and private procurement policies—especially where sole-source justifications are involved—mean that commercial success can hinge on a small number of early institutional wins.
- Clinical adoption hurdles: The incremental complexity of in-bore infusion workflows requires investment in training and change management; the cost of inadequate training can blunt adoption.
- Supply chain and component risk: Specialty components for non-magnetic actuation and shielding can face constrained supplier availability; suppliers should build redundancy into sourcing strategies.
What PW Consulting’s full report delivers — and why the granular data matters
Our full market study (base year 2025; forecast 2026–2032) combines a rigorous topline forecast with deep, actionable modules designed for strategy execution:
- Detailed market-sizing and growth scenarios with sensitivity analysis under alternative adoption and reimbursement assumptions.
- Segment-level analyses covering device types, clinical applications, and regional dynamics (note: segment-level numerical breakdowns are covered in the full report).
- Vendor scorecards and product benchmarking against safety, performance, usability, and service metrics.
- Regulatory pathway maps and clinical evidence templates tailored to 510(k) submissions and human-factors planning.
- Procurement playbooks for hospital purchasing groups and public health authorities, including negotiation levers and total-cost-of-ownership models built around common capital-life benchmarks.
- M&A and partnership targets identified by strategic fit and integration risk, with modeled impact on market share and revenue synergies.
To preserve the strategic value of this briefing and to support competitive decision-making, we have intentionally withheld detailed granular splits and proprietary scenario outputs from this press summary. The full dataset, vendor-by-vendor performance matrices, and downloadable financial models are available through the PW Consulting report portal.
Conclusion — why 2026 is a make-or-break year
For executives evaluating capital allocation and go-to-market strategy, 2026 presents a window of opportunity: regulatory clarity and early procurement precedents are converting a historically niche capability into an investable clinical platform. Companies that align product development with rigorous human factors data, secure early clinical references, and craft bundled workflow solutions will capture disproportionate upside in a market that is forecast to nearly double in revenue through 2032 at an 8.6% CAGR.
PW Consulting’s full report equips decision-makers with the quantitative forecasts, vendor intelligence, and tactical playbooks required to act in 2026 with confidence. For access to the complete study, including our proprietary models and vendor scorecards, please consult the PW Consulting report release page.
For detailed analysis of this topic, please visit the official page: Worldwide MRI Compatible IV Infusion Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com