

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
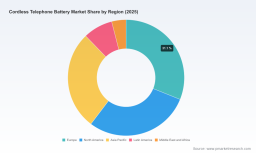
PW Consulting: Worldwide Cordless Telephone Battery Market to Edge Down in 2026–2032 (CAGR −0.51%); 2025 Revenue USD 485.5 Million — Ni‑MH Dominates at USD 397.64M, Aftermarket USD 411.47M, Europe Leads with USD 151.01M

Worldwide Cordless Telephone Battery Market — Strategic Outlook for 2026 Decision‑Makers
Executive summary
The Worldwide Cordless Telephone Battery market is at an inflection point. While the installed base of DECT and low‑power cordless handsets supports a stable replacement economy, regulatory shifts and emerging DECT NR+ deployments are reshaping product requirements and supplier economics. Our PW Consulting report — based on a 2025 base year and a 2026–2032 forecast horizon — shows a 2025 market size of approximately USD 485.5 Million and a modest compound annual growth rate of -0.51% across the forecast period. This headline stability masks short‑term volatility and structural changes that will determine winners and losers in 2026 and beyond.
Wearable Smart Wristbands Market
Why this matters for 2026 planning
For executive teams responsible for product strategy, supply chain, and channel go‑to‑market, the cordless battery market no longer permits a "set and forget" approach. A near‑term rebound in 2026 (reflected in our top‑line projections) coexists with longer‑term downward pressure driven by device energy‑efficiency standards, shifting battery chemistry economics, and channel dynamics between aftermarket replacement and OEM supply. In practice, that means decisions made in the coming 12 months — component sourcing, warranty policy, and aftermarket engagement — will materially affect profitability and market positioning through 2028.
Worldwide Fire Department Software Market
What the macro data tells us
Key macro signals from the dataset and modelling underpin three practical conclusions for strategists:
Worldwide Bot Management Solution Market
- Stability with episodic volatility: The overall market base (2025) and the near‑term model show a bounce and subsequent oscillation in revenues rather than a monotonic decline. Tactical inventory and procurement flexibility will therefore outperform rigid annual contracting models.
- Low but negative long‑term drift: The slight negative CAGR across 2026–2032 indicates a gradual contraction driven by efficiency improvements, longer handset lifecycles, and regulatory energy benchmarks — not a sudden structural collapse. Firms should prioritize margin protection and cost containment over aggressive volume expansion.
- Concentration matters: Market concentration metrics in our analysis (CR3 ~38.5%, CR5 ~52.2%) reveal a mid‑consolidated sector where top vendors exert meaningful influence without forming a closed oligopoly. This creates fertile ground for mid‑sized players and nimble specialists to expand via targeted product or channel plays.
Regulatory and technology inflection points
Regulation and standards are the proximate drivers of technical specification changes that downstream battery suppliers will need to absorb. The EU Ecodesign rules (effective June 2025) introduce explicit expectations for energy efficiency and minimum battery cycle life performance, and base station standby power caps create a tighter energy budget across cordless ecosystems. Meanwhile, the progression toward DECT NR+ (spectrum and system updates rolled forward in late 2025) unlocks new handset capabilities but also raises implications for duty cycles and battery endurance.
Product launches such as Fanvil’s W610D demonstrate the pace at which handset OEMs are integrating higher performance cordless subsystems. Taken together, these developments move battery requirements from pure energy capacity metrics toward a richer set of attributes: cycle life under real‑world duty profiles, standby/active power interplay, thermal stability, and compliance documentation.
Supply chain and material dynamics
Cordless telephone batteries continue to be dominated by mature chemistries that balance cost, safety, and lifecycle for low‑power applications. In this market context, lithium‑ion price deflation at the consumer‑electronics level has limited immediate effect on the segment because product designers have not broadly shifted to Li‑ion for legacy DECT handsets. Geopolitical tensions and tariffs on critical minerals do meaningfully shape broader battery supply chains; however, cordless telephone packs typically exhibit lower exposure to those concentrated raw materials than, for example, EV or grid‑scale battery sectors. For procurement teams, the priorities are therefore:
- diversifying qualified NiMH and small‑format Li‑ion cell suppliers,
- maintaining robust secondary sources for cells and pack assembly, and
- locking technical specifications and test protocols that align with impending Ecodesign and DECT NR+ requirements to avoid costly late‑stage redesigns.
Competitive landscape — who matters and why
The market is a mix of retail/aftermarket specialists, traditional cordless OEMs, and battery manufacturers. Each cluster requires a different strategic posture:
- Retail and aftermarket specialists (examples: Interstate Batteries, BatteryClerk, Batteries Plus) — these players excel in channel reach, replacement compatibility, and brand trust among consumers and small businesses. For OEMs, partnerships or white‑label agreements with these distributors remain attractive routes to extend product life and recapture end‑of‑life value.
- Integrated handset OEMs (examples: VTech, Panasonic, AT&T) — OEMs control specification and have the most direct route to standardize compliant battery packs for new handset lines. They are also the primary locus for embedding Ecodesign compliance into new releases and shaping the market’s technical bar.
- Contract manufacturers and cell suppliers (examples: Shenzhen Tcbest Battery, EnerSys) — these vendors provide the manufacturing capacity and engineering know‑how necessary for scale and customized pack solutions. Their role becomes pivotal when OEMs pursue rapid spec changes to meet regulation or new DECT features.
Our report contains concise strategic profiles of these firms, highlighting supply strengths, channel footprints, and M&A posture — enabling quick benchmarking and partner selection in 2026.
Commercial dynamics: aftermarket vs OEM
The aftermarket replacement economy remains the primary margin and volume engine for the cordless battery market. OEM replacement and bundled supply are strategically important for new handset launches and brand‑protected channels. For 2026, the tactical priorities differ by role:
- Retailers and aftermarket specialists should invest in warranty clarity, compatibility search tools, and compliance labeling to capture consumers trading up under Ecodesign awareness.
- OEMs need to accelerate battery validation programs and consider extended service/recertification offers to capture lifecycle revenue while conserving device longevity in a regulation‑tightened environment.
Practical recommendations for 2026
Leaders who intend to use 2026 to build durable advantage should prioritize five actions:
- Operationalize regulation: Build a cross‑functional Ecodesign readiness program (product, test labs, compliance, marketing) with a 6–12 month roadmap and clear acceptance criteria linked to warranty and R&D budgets.
- Flexible sourcing: Move to smaller, more frequent cell procurement contracts with dual qualified suppliers to buffer short‑term swings while maintaining price discipline.
- Aftermarket monetization: For OEMs, create certified replacement programs and trade‑in pathways that capture revenue and reduce gray‑market leakage.
- Portfolio triage: Apply a profitability heatmap across SKU families to decide which battery technologies and handset lines justify engineering investment versus those better suited to aftermarket replacement strategies.
- M&A and partnerships: Given mid‑market concentration, identify tuck‑in targets among regional pack assemblers or aftermarket specialists to accelerate channel scale and technical capabilities.
What PW Consulting’s report delivers
Our Worldwide Cordless Telephone Battery Market report is designed as a practical playbook for 2026. It includes:
- Top‑line forecasts and scenario modelling (base case, high demand, regulation‑forced redesign) for 2026–2032, with stress testing for energy‑efficiency and unit‑life assumptions.
- Supplier and channel heatmaps with qualitative supplier capability assessments and an M&A watchlist.
- Regulatory impact matrix (including Ecodesign obligations and DECT NR+ implications) that links compliance actions to capex and product timelines.
- Operational annexes: test protocols, recommended battery validation matrices, warranty framing templates, and an aftermarket monetization playbook.
- Executive dashboards and a downloadable scenario model so commercial teams can run "what‑if" cases specific to their product and region strategies.
How to use this insight in the boardroom
Board conversations in 2026 should move beyond positional statements about "market decline" to granular decisions tied to procurement cadence, product roadmap triage, and channel economics. Use the report’s scenario tool to quantify the P&L impact of: changing minimum cycle life requirements, supplier consolidation, and an increasing share of sales moving to certified replacement channels. That work will identify whether to accelerate R&D (for regulated compliance), de‑risk supply, or double down on aftermarket services.
Next steps and where to find the full segmentation
In keeping with our "trailer" approach, this release highlights the strategic takeaways and supporting context you need to prioritize 2026 actions while deliberately reserving the granular, segment‑level tables and model outputs for the full report. For access to detailed region, chemistry and channel split data, downloadable models, and vendor scorecards, please visit the PW Consulting report page or contact our industrial practice team for a tailored briefing.
Prepared by PW Consulting — Senior Strategy & Industry Analysis. For executive briefings or bespoke modelling workshops tied to this market, our team is available to support rapid, board‑level decision cycles in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Cordless Telephone Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com