

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Automotive Platooning System Market Set to Soar at a 34.56% CAGR, Driving Rapid Industry Expansion

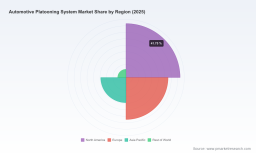
Worldwide Automotive Platooning System Market: Strategic Preview for 2026 Decision‑Makers
PW Consulting’s new market study, Worldwide Automotive Platooning System Market, synthesizes five years of historical performance and a seven‑year forecast to equip executive teams with the evidence and frameworks required to make high‑stakes investments in freight automation in 2026. The study shows platooning moving from pilots into commercially material deployments: the global market is modeled rising from a base of USD 126.5 Million (base year 2025) to a projected USD 1,010.92 Million by 2032, expanding at a compound annual growth rate of 34.56% through the forecast window.
Worldwide Community Platforms Market
Why this study matters for 2026 strategy
-
Acceleration point: 2026 will be a pivotal year when regulatory pressure, fleet electrification initiatives, and maturation of vehicle‑to‑vehicle communications converge to change investment calculus. Companies that move from experimentation to structured commercial pilots now will be best positioned to scale in the 2027–2030 inflection period.
Disposable Medical Anticoagulation Tube Market -
Risk‑aware scaling: The market’s rapid projected expansion offers large upside, but uptake is uneven across geographies, vehicle types and business models. Our report supplies decision‑grade scenario analysis to quantify upside and downside across those variables without relying on simple extrapolation.
Nursing Reception Station Market -
Operational realism: Platooning is not just a software play. Implementation carries meaningful hardware, integration and human‑capital costs — we model typical per‑truck implementation costs and the real TCO breakpoints that determine fleet ROI.
Key dynamics shaping the market
-
Regulatory drivers and compliance pathways: Policymaking is defining near‑term demand. The EU’s heavy‑duty CO₂ reduction commitments and recent safety mandates (including required automated emergency braking on new trucks) create both obligations and enabling conditions. In the U.S., state‑level approval regimes and fleet decarbonization rules (for example, California’s advancing clean fleets requirements) create pockets of early commercial opportunity for platooning as a fuel‑efficiency and operational‑compliance lever.
-
Technology stack evolution: Successful platooning deployments require a tightly integrated stack of sensors, controls, V2V communications and fleet orchestration software. Operators face tradeoffs between communication technologies, integration complexity, and upgrade paths for mixed fleets. Our technical due diligence maps current options, maturity levels, and interoperability constraints to practical decision rules.
-
Cost and ROI constraints: Implementation incurs material upfront costs — driven by sensors, compute, communications and driver program costs — which our sector analysis places in a range that requires careful fleet economics to justify. The report’s TCO models show how utilization, route geometry, fuel prices, and regulatory penalties materially alter payback timelines.
-
Commercial concentration and ecosystem structure: The market shows emerging concentration among a handful of systems providers, OEMs and tier‑one suppliers. Our concentration analysis (CR3/CR5) quantifies current market share dynamics and provides a competitive map for partnership or M&A plays.
What the report contains — practical deliverables for 2026
-
Market sizing and forecast model: Full historical series (2020–2025) and bottom‑up forecasts (2026–2032) by total market value, with scenario variants to stress test CAGR outcomes under different regulatory, technology and macroeconomic assumptions.
-
TCO and pilot design toolkit: Configurable calculators that translate vendor quotes and fleet telematics into break‑even distances, utilization thresholds and expected emissions reductions — designed to support board‑level approvals for pilot investments.
-
Regulatory and standards playbook: A jurisdictional map of policy drivers, approval pathways and near‑term regulatory changes that materially affect fleet operability, including recommended compliance workflows for commercial pilots.
-
Competitive landscape and supplier scorecards: Independent assessments of incumbent vendors, OEM initiatives and tier‑one component suppliers across technical competence, commercial readiness and partnership fit — enabling defensible vendor shortlists.
-
Use‑case playbooks: Operational templates for freight corridors, cross‑dock logistics, and dual‑use (commercial/defense) applications, each with recommended runbooks, staffing models and safety oversight measures.
-
M&A and partnership frameworks: A set of diligence checklists, valuation sensitivities and integration risk matrices tailored for strategic investors considering minority stakes, joint ventures or bolt‑on acquisitions.
Competitive landscape: who matters and why
-
Systems innovators and scale players: A small group of technology companies and OEMs are defining early production deployments and commercial interfaces. These players combine vehicle integration capabilities with either proprietary communications stacks or open integration strategies. Their differing approaches to V2V communications, safety validation and fleet‑centric orchestration shape lock‑in risks and interoperability outcomes.
-
Case highlights — exemplar profiles
-
Peloton Technology (Mountain View, CA) has operationalized driver‑assistive platooning around DSRC‑based V2V links and emphasizes incremental safety and efficiency gains in commercial fleets.
-
Kratos Defense & Security Solutions (San Diego, CA) demonstrates cross‑domain application potential — expanding automated platooning support for logistics in high‑visibility events and dual‑use testing programs demonstrates an ability to deploy at scale rapidly and to adapt systems for ruggedized or mission‑critical use cases.
-
Major OEMs (including longstanding European and North American truck manufacturers) are integrating platooning capabilities into production vehicles, focusing on aerodynamic gains, platform reliability and multi‑brand convoy interoperability — a dynamic that will accelerate OEM‑led adoption once regulatory and market conditions align.
-
Tier‑one suppliers (sensor, brake and control specialists) are positioning to be the integration backbone by offering validated subsystems and retrofit packages that shorten time‑to‑pilot for fleets reluctant to rely on single‑vendor stacks.
-
-
Consolidation risk and partnership opportunities: Market concentration metrics indicate material advantages for early leaders yet leave substantial room for specialist vendors and integrators. For incumbent transport operators, partnering with validated system integrators rather than building in‑house end‑to‑end systems is often the lower‑risk path to early commercial benefit.
Recent market movements to watch in 2026
-
Deployment expansions by dual‑use providers, including high‑profile logistics support for major events, signal that platooning systems are operationally maturing and being stress‑tested in complex, long‑haul environments. These deployments yield real‑world performance data that materially shorten validation cycles for other fleets.
-
Regulatory updates and pilot approvals in multiple jurisdictions continue to shape where fleets can operate at scale; operators who align pilots with jurisdictional approval pathways secure first‑mover corridor advantages.
Strategic recommendations for executives (actionable in 2026)
-
Design tiered pilots: Launch a two‑stage pilot program that separates technology validation from commercial scaling. Stage one focuses on safety, communications interoperability and driver workflows; stage two emphasizes route optimization, pricing and commercial KPIs.
-
Prioritize interoperability and standards alignment: Avoid single‑vendor lock‑in by requiring open interfaces for telematics, over‑the‑air updates and fleet operations software. Insist on supplier commitments to multi‑brand convoy demonstrations as part of procurement criteria.
-
Model regulatory scenarios: Build financial models tied to specific policy outcomes (e.g., targeted emissions reduction mandates or state approval timelines). Use these models to determine optimal investment timing and the scale of pilot commitments.
-
Explore commercial innovations: Consider subscription models, retrofit service bundles, and performance‑based contracting with system providers to spread capital cost and align incentives for fuel‑savings delivery.
-
Prepare for human factors and training: Invest in driver training and revised operating procedures early. Effective human‑systems integration materially shortens time‑to‑value and reduces operational risk during scaling.
What PW Consulting recommends next
For boards, corporate strategy teams and private investors, the question is not whether platooning will be relevant — it already is — but how rapidly and where it will become profitable. Our report converts market momentum into decision‑grade intelligence: it quantifies market expansion, models plausible adoption curves under multiple policy and technology assumptions, and delivers practical toolkits to design, bid, and scale pilots with measurable KPIs.
We deliberately present this preview to demonstrate the analytical depth and practical orientation of the full study while preserving the proprietary granularity that underpins robust commercial decisions. To access the full forecast models, vendor scorecards, TCO calculators and jurisdictional playbooks that will inform board‑level investment decisions in 2026, please consult PW Consulting’s official report page and contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Platooning System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com