

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting Report: Worldwide Diclofenac Transdermal Patches Market Poised to Expand at a 6.5% CAGR Through 2032
By pmarketresearch, 2026-08-18
Worldwide Diclofenac Transdermal Patches Market: Strategic Imperatives for 2026
Executive summary
As healthcare systems accelerate shifts toward non-opioid pain management and payers sharpen reimbursement criteria, diclofenac transdermal patches have entered a new phase of strategic relevance. PW Consulting’s latest market study positions the worldwide diclofenac transdermal patches market at USD 648.55 Million in 2025, having grown from a mid-single‑hundred million base in 2020. Under a 6.5% compound annual growth rate (CAGR), the market is projected to approach roughly USD 1.01 Billion by 2032. This trajectory reflects a steady, durable expansion driven by clinical preference for topical NSAIDs, regulatory convergence on combination‑product quality, and new commercial pathways such as authorized generics and payer-led non‑opioid programs.
Translational Chip Testing and Sorting Machine Market
Why this report matters for 2026 decision-makers
- Actionable foresight: The study translates macro momentum into decision-ready scenarios for 2026—detailing where to prioritize manufacturing scale, commercial investment, and regulatory preparation.
- Market structure insights: While the category remains competitive, concentration metrics indicate meaningful scale benefits—top-three incumbent positions account for under half the market while the top five approach two-thirds—creating both competitive pressure and acquisition opportunities for mid‑sized players.
- Risk‑aware growth planning: The report integrates regulation, reimbursement, and safety risk layers (including the implications of boxed warnings and combination‑product oversight) into go‑to‑market models so executives can size opportunity against foreseeable constraints.
Core market dynamics shaping 2026 strategies
Four converging forces will define priorities for the coming year.
Worldwide Hydro Stoves Market
- Payer and clinical preference shifts: Public and private payers in several markets are actively emphasizing non‑opioid pain pathways in outpatient and post‑operative care. Inclusion in payer policies and favorable reimbursement criteria are increasingly decisive for adoption in ambulatory settings.
- Regulatory intensity for combination products: Transdermal diclofenac systems are regulated as combination products in several major jurisdictions, requiring stringent compliance with cGMP and device‑quality expectations. This raises the bar for manufacturing and quality assurance investments.
- Product differentiation via formulation and delivery: Hydrogel systems enabling extended (e.g., 12‑hour) relief, patch size and reservoir design, and variations in diclofenac salt forms create meaningful clinical and commercial differentiation points that affect prescribing and patient adherence.
- Commercial mechanics—brand, authorized generics, and access programs: Brand‑originator programs (including copay and direct patient assistance) coexist alongside authorized generics, creating a two‑front commercial playbook for price competitiveness and brand protection.
Strategic implications and recommended actions for 2026
- Prioritize payer engagement and evidence generation: Secure formulary placement through targeted real‑world evidence (RWE) and health economic dossiers that demonstrate topical NSAIDs’ benefits in reducing opioid exposure and improving recovery metrics.
- Invest in manufacturing and quality infrastructure: Given combination‑product regulation and the premium on consistent delivery performance, scale up cGMP‑aligned production, supplier qualification, and device testing to reduce regulatory and supply risk.
- Pursue flexible commercialization models: Evaluate authorized generic strategies, co‑promotion and licensing deals, and patient assistance programs as mechanisms to protect share while participating in price‑sensitive channels.
- Differentiate clinically and commercially: Leverage unique delivery technologies (e.g., hydrogel patches providing extended relief) and adherence‑focused support to command premium positioning versus commodity patches.
- Scan for value‑accretive M&A and manufacturing partnerships: Moderate top‑end concentration creates buy‑and‑build opportunities—target bolt‑on assets that add formulation expertise, geographic reach, or contract‑manufacturing capacity.
Competitive landscape — who matters and why
The player set comprises brand originators, global generics houses, specialist manufacturers, and integrated local producers. A succinct assessment of leading strategic positions follows:
Worldwide Anti Mould Paints Market
- IBSA Institut Biochimique SA (IBSA Pharma Inc.): The originator position remains strategically valuable because it anchors clinical recognition and payer discussions. IBSA’s branded topical system leverages hydrogel technology, extended relief claims, and proactive patient access programs—factors that sustain premium positioning even as generic alternatives proliferate. Recent updates to prescribing information and inclusion in payer policies underscore an active lifecycle management approach.
- Teva Pharmaceutical Industries Ltd.: As a major generics player, Teva’s presence with an authorized generic equivalent provides immediate scale and channel penetration. Large‑scale generics capability can rapidly commoditize pricing, making Teva a key competitor for volume‑oriented channels.
- Yaral Pharma (IBSA affiliate): Positioning as an authorized generic from the originator group enables a two‑tier commercial strategy: retain premium brand positioning while capturing price‑sensitive segments through an identical, lower‑cost alternative.
- Contract and specialist manufacturers (e.g., Teikoku Seiyaku, Sparsha Pharma, Gangwal Healthcare): Their cGMP transdermal capabilities are strategic enablers for sponsors seeking rapid scale or geographic diversification. Outsourcing to experienced patch manufacturers minimizes time‑to‑market and capital expenditure but requires careful supplier qualification to meet combination‑product expectations.
- Regional formulary players (selected local healthcare companies): Companies marketing diethylamine and sodium salt forms bring localized access and familiarity with national prescribing patterns—useful acquisition targets for players seeking market entry or broader product portfolios.
Regulatory and safety considerations
Executives must treat regulatory and safety developments as strategic variables rather than compliance checkboxes. Diclofenac topical systems carry class‑level cardiovascular and gastrointestinal safety considerations and peri‑operative contraindications that influence labeling, patient selection, and payer policy language. Notably, regulatory updates to prescribing information and payer policy inclusions over the last 18 months signal ongoing scrutiny; forward plans should include robust pharmacovigilance, targeted post‑marketing studies, and label management strategies aligned with global regulators’ combination‑product expectations.
What PW Consulting’s report delivers to operational teams
The report is structured to move executives from insight to execution. Highlights include:
- Financial models: rolling forecasts from 2026 through 2032 with scenario toggles for pricing, uptake, and reimbursement shocks calibrated to a 6.5% base CAGR and built off a 2025 market benchmark.
- Competitive playbooks: granular profiles of originators, generics, and specialist manufacturers with assessed strategic levers and likely near‑term moves.
- Go‑to‑market tools: payer engagement templates, launch sequencing plans, and contracting strategies for both branded and authorized generic approaches.
- Manufacturing and supply‑chain maps: capacity assessments, CMO shortlists, and risk mitigation checklists tailored to combination‑product production.
- Regulatory and safety matrix: jurisdictional requirements, label‑change risk assessments, and recommended post‑launch evidence strategies.
- M&A and partnership screening: diligence frameworks and candidate shortlists aligned to specific corporate objectives (scale, portfolio diversification, or capability acquisition).
To preserve competitive value for subscribing clients, the report intentionally withholds raw breakdowns of certain sub‑segment revenue shares and regional splits in this public summary. These detailed tables and interactive dashboards are accessible in the full report package.
Immediate actions recommended for 2026 planning cycles
- Embed payer evidence generation into 2026 budgets—allocate resources for targeted RWE and health economic modeling that aligns with non‑opioid performance metrics.
- Qualify at least two cGMP transdermal manufacturers for commercial supply to mitigate regulatory and capacity risk.
- Run rapid commercial scenarios evaluating authorized‑generic launch versus co‑promotion with brand originators to select the most value‑accretive pathway.
- Establish a safety‑communications and label‑management task force to proactively address regulatory updates and payer policy shifts.
- Scan and prioritize acquisition or partnership targets that fill key capability gaps—formulation science, device engineering, or regional distribution.
Concluding viewpoint
Diclofenac transdermal patches occupy a strategic intersection of clinical utility, payer interest, and manufacturing complexity. The category’s steady compound growth—anchored by a 6.5% CAGR to a near‑billion‑dollar opportunity by 2032—rewards players that combine rigorous regulatory compliance, clinical differentiation, and flexible commercial models. For 2026 planning, the signal is clear: investment in manufacturing quality, payer evidence, and differentiated delivery technology will determine which organizations capture sustainable share. PW Consulting’s report converts these high‑level signals into executable programs for teams ready to move from assessment to action.
About PW Consulting
PW Consulting is a specialty strategy advisor to healthcare executives, combining market analytics, regulatory insight, and commercial execution frameworks. This study leverages an historical data series (2020–2025), a 2025 base year, and forward projections covering 2026–2032. For access to the full dataset, segmented tables, interactive models, and bespoke advisory engagement, please consult the complete Worldwide Diclofenac Transdermal Patches Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Diclofenac Transdermal Patches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Follow‑Me Autonomous Tech Propels Worldwide Hands‑Free Caddie Market to USD 587.14 Million by 2032 at 10.45% CAGR
By pmarketresearch, 2026-08-18
Worldwide Hands‑Free Caddie Market: Strategic Preview for 2026 — Insights from PW Consulting
PW Consulting’s latest market intelligence on the worldwide hands‑free caddie market provides a focused, decision‑ready briefing for executives planning investments, product launches, channel plays, or operational pilots in 2026. This executive summary teases the analytical depth of the full report — including validated market-sizing, forward forecasts, go‑to‑market frameworks, supplier scorecards and risk matrices — while preserving the proprietary sub‑segment detail reserved for the full dossier.
Worldwide General Medicine Education Publishing Market
Why 2026 Is a Pivotal Year
- Market momentum: After an aggressive recovery and expansion phase through the early 2020s, the market reached an estimated USD 292.8 Million (base year 2025). Our forecast shows sustained expansion over 2026–2032, with the market more than doubling from the 2025 base by the end of the forecast window.
- Structural acceleration: A measured but steady compound annual growth rate (CAGR) of 10.45% underpins this trajectory, reflecting both unit adoption and premiumization driven by autonomy, sensor integration, and service models.
- Decision timing: 2026 represents an inflection point where product maturity, regulatory attention, and buyer readiness align — making it the year to convert strategy into pilots, partnerships, and scaled deployments.
Key Market Dynamics Shaping Strategy
- Technology convergence: Hands‑free systems are converging around multi‑sensor stacks (visual AI, LiDAR/TOF, UWB/ultrasound, RF and Bluetooth) plus advanced control software. That convergence is creating a “feature battleground” in obstacle avoidance, slope management and power efficiency — areas that determine user satisfaction and course acceptance.
- Safety and standards pressure: Product safety design is no longer peripheral. Automatic downhill braking and stability systems are becoming mandatory features in leading models, and course operators now expect proof points on fail‑safe behaviors. This raises engineering costs but reduces operational risk for lessees and courses.
- Commercialization models: Leasing and fleet models for clubs and rental operators are becoming the dominant adoption path for institutional buyers, while retail and hybrid ownership remain important for individual golfers. Course operators evaluating hands‑free caddies are increasingly focused on lifecycle costs, uptime SLAs, and training/maintenance requirements.
- Consolidation and concentration: Market concentration indicates room for scale plays. Leading firms together command a meaningful share of market revenue, with the top three and top five vendors accounting for substantial portions of market revenue — a dynamic that favors well‑capitalized incumbents and disciplined consolidators.
Strategic Implications — What Leading Executives Should Do in 2026
Executives who treat 2026 as a trial‑and‑scale year will capture share and shape standards. Practical priorities include:
Worldwide Automatic Tolling Systems Market
- Prioritize partner pilots that validate safety and terrain performance. Shortlist vendors that can demonstrate robust downhill braking, obstacle avoidance and slope handling in club‑grade conditions, then run week‑long pilots across representative holes rather than single‑day demos.
- Design commercial models around total cost of ownership (TCO) and uptime. For clubs and rental fleets, make maintenance, training and spare‑parts logistics core to commercial negotiations. For consumer channels, emphasize warranty, drop‑in accessory ecosystems and trade‑in paths.
- Upgrade procurement RFPs to include standardized performance tests. Include pass/fail criteria for sensor redundancy, battery life under load, and recovery behaviors after communication loss. Use those tests in supplier scorecards to reduce post‑deployment surprises.
- Invest in a modular product roadmap. Given the rapid pace of sensor and AI improvements, companies should decouple hardware platforms from perception and autonomy stacks to accelerate feature upgrades while protecting hardware investments.
- Monitor regulatory developments and build compliance playbooks. From safety device requirements to worker‑classification implications in key markets, regulatory shifts will influence operating models, insurance and leasing structures.
Competitive Landscape — Who Matters and Why
The competitive field spans global incumbents, specialized innovators, and established outdoor/automotive OEMs pivoting into golf mobility. Below are the strategic positions of key players covered in our research and what to watch from each in 2026.
Worldwide Property & Casualty Policy Administration Systems Software Market
- MGI Golf — Australia HQ with significant US operations. MGI has pushed the envelope on productization with intelligent navigation series and a visible presence at trade events. Its January 2026 PGA Show introductions — including a LiDAR‑enabled follow/avoidance system and a lightweight on‑demand motorized pushcart — underline its dual focus on AI navigation and consumer convenience. For partners, MGI is notable for rapid market activation and strong channel execution in key markets.
- Stewart Golf — British engineering heritage. Stewart’s premium “follow” platforms emphasize mechanical stability and pace‑of‑play benefits on hilly courses. Its design and material choices support premium placements within club‑owned fleets and affluent consumer segments interested in engineered durability.
- CaddyTrek (FTR Systems) — US‑based robotic specialist. CaddyTrek’s product family includes ultrasound/RF and AI‑vision variants, offering multiple modes and proven terrain capability. Their product breadth makes them an attractive supplier for operators wanting flexible deployment options across varied course topographies.
- Robera — Product‑led innovator. Robera’s offerings prioritize gesture control and AI visual guidance with obstacle‑avoidance stacks that include iTOF/UWB. Their emphasis on robust sensor fusion positions them well where precision following and pedestrian safety are priority evaluation criteria.
- Kangaroo Golf — US‑based mass market and ergonomics focus. Kangaroo balances remote control simplicity with practical design — quick‑fold mechanisms and reliable autobrake systems — making it suitable for consumer retail channels and rental fleets seeking value and easy serviceability.
- Motocaddy, PowaKaddy, Alphard Golf, QOD Golf USA, Club Car (Ingersoll Rand) — Range of approaches from GPS‑integrated remote control to OEM‑scale deployments. These firms represent the trade‑off set between legacy electric trolley expertise and new autonomy features; some keep legacy products relevant via incremental autonomy integrations and OEM partnerships.
Regulation, Standards and Operational Risk
- Product safety requirements — including downhill braking and stability systems — are material for certification and course acceptance. Buyers should request third‑party test evidence and include safety clauses in contracts.
- Standards for follow technologies are not uniform: vendors use RF/ultrasound, visual AI, LiDAR/TOF and UWB in different combinations. Procurement teams should specify minimum sensing redundancy and obstacle‑avoidance performance rather than a single technology preference.
- Labor and insurance considerations can affect deployment models. In some jurisdictions, human caddies are subject to specific worker‑classification rules and compensation frameworks that can influence the cost calculus of shifting to autonomous fleets.
What the PW Consulting Report Includes (Practical, Actionable Deliverables)
The full report is designed as an operational toolkit for executives, including:
- Validated market sizing (historical 2020–2025 and forward 2026–2032 forecasts) and scenario analyses to stress‑test assumptions under different adoption curves.
- Go‑to‑market playbooks for three buyer archetypes: course operators (fleet/lease), consumer retail (direct and dealer), and hybrid rental marketplaces.
- Supplier diligence templates and a bespoke procurement RFP checklist that embeds performance pass/fail criteria for safety, terrain handling and maintenance economics.
- Commercial models comparing lease vs. purchase vs. managed‑service economics for club fleets, including sensitivity analyses for battery replacement, sensor upgrades and downtime penalties.
- Competitive scorecards and partnership matrices identifying best‑fit vendors by buyer need, integration complexity and scale readiness.
- Risk and compliance playbooks with recommended contract language, insurance considerations and pilot validation scripts to de‑risk rollouts.
How to Use These Insights in 90, 180 and 365 Days
- 90 days: Run a closed‑loop pilot with a single vendor across a small set of holes. Use our RFP checklist and pilot protocol to validate downhill braking, obstacle handling and service logistics.
- 180 days: Negotiate a scalable lease or managed‑service that includes spare‑parts provisioning, training and defined uptime SLAs. Use TCO models to compare vendor proposals.
- 365 days: Transition successful pilots into fleet rollouts or retail launches with staged feature upgrades. Lock in sensor‑stack modularity to preserve upgrade paths while amortizing hardware.
Next Steps and Where to Get the Full Dataset
This public briefing is a strategic preview that highlights why 2026 is a decisive year for market entry, scaling and consolidation decisions. For access to the full dataset — including the detailed segmentation tables, vendor scorecards, downloadable RFP templates, and the granular forecast model — visit PW Consulting’s report page for the Worldwide Hands‑Free Caddie Market. The full report contains the proprietary sub‑segment figures and channel‑level breakouts that underpin the recommendations summarized here.
PW Consulting’s global industry team remains available to support tailored procurement design, vendor selection facilitation, and pilot governance for organizations preparing to act in 2026. Contact us to book a briefing or to commission a custom variant of the market model aligned to your strategic objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Hands-Free Caddie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide 3D-Printed Prosthetic Hands Market to Reach USD 371.66 Million by 2032, Growing at a 15.12% CAGR
By pmarketresearch, 2026-08-18
Worldwide 3D Printed Prosthetic Hands Market — Strategic Imperatives for 2026
PW Consulting’s latest market intelligence on the Worldwide 3D Printed Prosthetic Hands Market frames 2026 as a decision-rich year for manufacturers, payers, clinical providers, and technology partners. Our analysis shows the market at USD 138.7 Million in the 2025 base year, and, under current dynamics, on a trajectory to expand at a 15.12% CAGR through the 2026–2032 forecast window, approaching roughly USD 372 Million by 2032. This growth is being driven by simultaneous advances in additive manufacturing, clearer reimbursement signals, and stronger clinical evidence — creating both immediate opportunities and execution risks for firms that must choose where to compete, how to scale, and whom to partner with.
Worldwide Workplace Innovation Platforms Market
Why 2026 Is an Inflection Point
-
Reimbursement alignment: The September 2025 DME MACs and PDAC joint guidance recognizing additive manufacturing as an acceptable, reimbursable fabrication method for custom prosthetic devices removes a key commercial barrier. For suppliers and hospital systems, this shifts conversations from “will payers pay?” to “on what terms and for which use cases?”
Worldwide Big Data Analytics Software Market -
Commercial scale-up of digital manufacturing: Market actors are moving rapidly from prototyping to production-grade additive manufacturing. Notably, a major supplier has announced Medicare coverage while expanding in‑house 3D printing capacity fivefold using desktop resin systems, signalling that cost per unit and time-to-delivery are now management levers rather than immutable constraints.
Worldwide Asphalt Anti Strip Agent Market -
Regulatory and clinical convergence: FDA’s maturity in 3D printing guidance and a growing body of clinical literature demonstrating improved dexterity and satisfaction in upper‑limb prosthesis users make clinical adoption more defensible — but also raise the bar on quality systems, traceability, and post-market surveillance.
Market Structure and Competitive Dynamics — What Executives Need to Know
The market remains fragmented: CR3 sits below 20% and CR5 below 25%, underscoring that no single incumbent dominates the space. This fragmentation is fertile ground for focused entrants, rapid innovators and payer‑aligned partners — but it also demands disciplined portfolio choices.
-
Specialists focused on myoelectric, multi‑grip solutions are demonstrating how clinical approvals and insurance reimbursement unlock premium channels (pediatric care, orthotic‑prosthetic clinics, and major health systems).
-
Lean makers of body‑powered and partial‑hand devices are carving an adjacent low‑cost, high‑utility niche by leveraging robust additive nylon technologies and simplified mechanical designs to restore specific activities of daily living.
-
Nonprofit and humanitarian players emphasize localized printing and training models that change unit economics in low‑resource settings, influencing procurement practices and partner expectations in emerging markets.
Profiles and Strategic Implications of Core Competitors
-
Open Bionics — Clinically oriented bionics with insurance pathways and a strong product family strategy (multi‑grip hands, waterproof models, breathable sockets). Strategic implication: demonstrating the commercial value of clinically validated aesthetic and functional devices; a model to emulate for firms seeking payer coverage and pediatric focus.
-
PSYONIC — Lightweight, touch‑sensing Ability Hand leveraging 3D printed resins and now covered by Medicare, while materially scaling in‑house additive capacity. Strategic implication: combining product differentiation (haptic feedback) with scalable digital manufacturing creates a defendable cost/feature advantage — a competitive playbook for incumbents and fast followers.
-
Naked Prosthetics — Focus on durable, 3D printed body‑powered and partial‑hand devices using nylon additive technologies. Strategic implication: there is a sizable, under‑served segment where mechanical simplicity and material performance trump electronic complexity.
-
Unlimited Tomorrow — Verticalized model integrating 3D scanning, sockets, and hands to reduce cost while delivering realistic aesthetics. Strategic implication: vertical integration can compress lead times and margin leakage across the supply chain — a template for vertically minded companies or consolidators.
-
Limbitless Solutions — Innovation-led, donation-driven EMG devices that strengthen clinical trial pipelines and community goodwill. Strategic implication: philanthropic and trial activity can accelerate technology acceptance and provide low‑risk paths to evidence generation.
-
Victoria Hand Project — Low‑cost, localized printing and training solutions tailored to underserved regions. Strategic implication: humanitarian and local-manufacture models will increasingly influence pricing expectations and distribution strategies in international markets.
Operational Priorities — From Materials to Manufacturing
-
Materials and processes: Nylon and PA11 printed via SLS/MJF are the workhorses for durable, patient‑facing components; resin systems are enabling rapid iteration and embedded sensor housings. Procurement strategies should prioritize long‑term supply agreements for bio‑compatible grades and secondary certification pathways for sterilization and traceability.
-
Quality and regulatory architecture: FDA 510(k) pathways remain the most common route for externally applied prosthetics; additive manufacturing introduces process‑centric validation requirements. Firms must invest in process validation, device histories, and software change control now, not as a later add‑on.
-
Manufacturing footprint: Firms must choose between centralizing to capture scale‑economies and decentralizing to shorten clinical lead times and enable localized customization. Business models that hybridize (centralized critical components with localized final fitting) are emerging as pragmatic compromises.
Commercial and Reimbursement Playbook for 2026
-
Engage payers with evidence packages aligned to HCPCS descriptors and PDAC guidance; early alignment with DME MACs will materially reduce authorization friction for new prosthetic fabrication workflows.
-
Differentiate through service: bundled offerings combining scanning, socket customization, device fitment and follow‑up rehab services command premium positioning versus pure hardware sales.
-
Leverage clinical champions and real‑world evidence: multi‑center outcomes data demonstrating improved function and satisfaction shorten sales cycles with hospital systems and enhance payer negotiations.
-
Channel strategy: sustainable routes-to-market will include hospitals and clinics, rehab centers, direct-to-user models, and NGO partnerships — each requires different pricing, warranty and logistics planning.
Where PW Consulting’s Report Adds Tactical Value
Our full report is written for leaders making capital allocation, M&A, manufacturing, and go‑to‑market decisions in 2026. The publisher’s deliverables are purpose-built to be actionable:
-
Scenario‑based financial models that stress test manufacturing strategies, reimbursement outcomes, and pricing strategies.
-
Reimbursement playbook that walks through HCPCS alignment, PDAC submission considerations, and payer engagement timing following the 2025 guidance.
-
Supplier and technology matrix comparing SLS/MJF, resin systems, post‑processing, and material choices (with vendor benchmarking and unit‑cost sensitivities).
-
Go‑to‑market blueprints tailored to direct sales, clinical partnerships, NGO distribution, and hybrid service models, with contract templates and pilot KPIs.
-
Competitive playbooks with strategic counter‑moves for the firms profiled above, and an M&A screening tool to identify consolidation and capability‑acquisition targets.
Note: To preserve the strategic value of this briefing and to respect client confidentiality requirements, this public summary highlights aggregate market size and growth rates but does not disclose detailed regional, product, or end‑user share tables. The full report contains granular segmentation, regional revenue schedules, and unit‑level pricing models that are available only through PW Consulting’s report access channels.
Immediate Decisions for 2026
-
Prioritize quick wins in reimbursement: finalize PDAC coding strategies and pilot Medicare billing pathways now to realize revenue lift in 2026.
-
Decide on manufacturing posture: conduct a rapid make‑vs‑buy analysis that incorporates 3D printing CAPEX, capacity lead times, and labor upskilling needs.
-
Invest in outcomes data: fund at least one multi‑site real‑world outcomes study to support payer negotiations and differentiate in procurement bids.
-
Map strategic partnerships: identify clinical, technology and NGO partners that complement your chosen route-to-market and can accelerate adoption with minimal capital outlay.
PW Consulting’s Worldwide 3D Printed Prosthetic Hands Market report is designed as an operational playbook for 2026 decision‑makers who must transform regulatory and manufacturing momentum into sustainable commercial advantage. For access to the full dataset, regional and subsegment schedules, and bespoke advisory engagements, please visit our report page or contact PW Consulting directly for an executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide 3D Printed Prosthetic Hands Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide RNA Cleanup Market at USD 525.0 Million in 2025, Forecast to Reach USD 950.5 Million by 2032 at 8.85% CAGR
By pmarketresearch, 2026-08-18
Worldwide RNA Cleanup Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive snapshot
Between 2020 and 2025 the worldwide RNA cleanup market expanded from approximately USD 345.5 million to USD 525.0 million, driven by accelerating throughput in next‑generation sequencing (NGS), expanded in vitro transcription (IVT) workflows for mRNA modalities, and growing adoption of automation across life‑science laboratories. Our base‑case forecast projects the market to reach roughly USD 574.4 million in 2026 and to approach USD 950.5 million by 2032, corresponding to a compound annual growth rate of 8.85% over the 2026–2032 forecast window. For executive teams planning investments, partnerships or portfolio pivots in 2026, these macro dynamics create a narrow window to lock in supply, validate next‑generation offerings, and shape commercial positioning ahead of sustained growth.
Worldwide HTAP-Enabling In-Memory Computing Technologies Market
Why this report matters for 2026 decision cycles
Strategic choices made in 2026 will determine whether organizations capture disproportionate share of the expansion that follows. The market is maturing: demand is less about single‑use commodity sales and more about integrated workflows, regulatory alignment for therapeutic applications, and supply resilience. Our report synthesizes quantitative forecasting with executable commercial playbooks — enabling leaders to prioritize R&D allocation, procurement safeguards, and channel strategies without getting lost in tactical minutiae.
Worldwide 5G Network Equipment on Top of Antennas Market
Key trends shaping strategy
- Therapeutics and diagnostics are raising the bar. Regulatory guidance from major authorities emphasizes rigorous characterization of RNA integrity and purity for therapeutic use, moving cleanup from a “laboratory convenience” into a documented critical control point. This drives demand for GMP‑grade inputs, validated protocols, and supplier traceability.
- Automation and throughput are non‑linear drivers. Automation investments—spurred by high‑throughput sequencing centers, spatial transcriptomics, and contract testing laboratories—are accelerating adoption of bead‑based and automated cartridge solutions that simplify hands‑on time and reduce variability.
- Raw‑material and supply chain constraints. Critical components such as silica membranes and magnetic beads are regionally concentrated and experienced multi‑week delivery delays in prior cycles. GMP‑compliant chemistries and plastics face capacity constraints that can bottleneck scale‑up for therapeutics.
- Cost and material policy pressures. Episodic reagent price spikes during demand surges have been observed historically, and regulatory measures (for example, directives on single‑use plastics) are extending product development timelines as vendors redesign components for recyclability or alternative polymers.
- Competitive consolidation alongside specialist insurgency. The market displays a measurable degree of concentration: a handful of large, diversified life‑science suppliers dominate core workflows, while nimble specialists and platform partners push innovation in bead chemistry, miniaturization, and high‑recovery formats.
Practical contents of the PW Consulting report
Clients can expect an operationally focused deliverable that bridges strategic foresight and implementation. The report contains:
Short Drama Promotion Authorization Platform Market
- A transparent market model with historical (2020–2025) actuals and scenario‑based forecasts to 2032, enabling sensitivity testing against price shocks, adoption curves, and capacity constraints.
- Supply‑chain risk mapping: supplier concentration, critical raw‑material sourcing, lead‑time stress tests, and mitigation playbooks for dual‑sourcing and inventory strategy.
- Technology and product taxonomy: evaluation of silica‑based, magnetic bead, and alternative chemistries; automation readiness scoring; and technology migration timelines aligned to therapeutic and diagnostic requirements.
- Regulatory pathway dossiers: implications of FDA/EMA guidance on analytical characterization and GMP sourcing, plus compliance checklists for developers entering therapeutic markets.
- Commercial playbooks and price‑elasticity analysis: GTM segmentation, channel configuration guidance, and recommended pricing approaches under volatile reagent cost scenarios.
- Competitive landscaping and vendor scorecards: capability matrices, strategic strengths and vulnerabilities, and prioritized partnership targets for M&A or co‑development.
- Actionable 90‑ to 360‑day implementation plans tailored to incumbent vendors, emerging suppliers, and end‑user laboratories.
Competitive landscape: how incumbent and specialist strategies diverge
The vendor field is a mix of global life‑science titans and focused innovators. Leading multinational suppliers leverage broad portfolios, global distribution, and integrated automation platforms to offer end‑to‑end workflows that appeal to large sequencing centers and clinical labs. Specialists and medium‑sized players compensate with rapid product iterations, niche chemistry advances, and targeted channel partnerships.
- Large OEMs and platform players. Companies with extensive automation and reagent portfolios are positioned to bundle cleanup solutions into higher‑value offerings for clinical and high‑throughput segments. Their scale enables global regulatory support and integration with instrument systems, making them preferred partners for translational and clinical customers.
- Mid‑market innovators. Specialized firms compete on recovery rates, low‑volume concentration performance, and ease of automation. Their agility is reflected in targeted launches and collaborations that extend into spatial transcriptomics and IVT workflows.
- Startups and service providers. Small entrants find footholds in niche use cases—single‑cell prep, small RNA cleanup, or high‑throughput bead‑based plates—often becoming acquisition targets for larger players seeking rapid capability build‑out.
Notable market moves and tactical implications
- Product launches expanding magnetic bead automation have shortened throughput timelines for RNA purification, enabling vendors and labs to advertise same‑day IVT‑to‑sequencing workflows. Organizations should evaluate pilot integrations now to be deployment‑ready in 2026.
- Collaborations between purification specialists and sequencing platform companies are emerging, particularly around spatial transcriptomics. These partnerships accelerate adoption cycles by delivering validated, end‑to‑end solutions favored by translational researchers.
- Planned discontinuations and portfolio rationalizations—paired with suppliers transitioning to new chemistries or disposable designs—require customers to assess migration paths and re‑qualify processes to avoid downstream disruption.
- Regulatory expectations and GMP constraints are driving up the cost and time required to certify materials at scale; firms that pre‑qualify suppliers and invest in secured manufacturing capacity will gain first‑mover advantage for therapeutic supply contracts.
Strategic recommendations for 2026 decision‑makers
- Lock in dual sourcing for critical inputs. Given historical multi‑week lead‑time volatility for beads and membranes, buyers should establish validated secondary suppliers and safety stock policies to prevent program delays.
- Prioritize automation‑ready R&D. Invest in bead‑based and cartridge formats designed for robotics and high‑throughput platforms. Early pilots with key sequencing or automation partners accelerate commercial uptake.
- Accelerate regulatory alignment. For firms targeting therapeutic markets, commence analytical validation and GMP supplier qualification now—regulatory guidance has elevated cleanup to a measurable quality attribute.
- Mitigate material‑policy risk. Re‑engineer single‑use designs in anticipation of plastics‑policy changes to avoid late‑stage development delays and ensure continuity in European markets.
- Use pricing hedges and cost‑transparency clauses. Protect margins against episodic reagent price spikes via indexed contracts, advance purchase agreements, and pass‑through mechanisms where appropriate.
- Consider bolt‑on acquisitions or partnerships. For companies seeking rapid access to high‑recovery chemistries, automation compatibility, or validated clinical supply chains, targeted M&A or licensing can compress time‑to‑market significantly.
How PW Consulting positions clients for execution
Our approach moves beyond forecasting to executable plans. We provide clients with vendor‑level scorecards, procurement negotiation templates, a validated supplier shortlist for GMP inputs, and a 12‑month operational roadmap that aligns R&D milestones with regulatory submission timelines and commercial launch windows. For commercial teams, we model go‑to‑market permutations (direct, distributor, instrument bundling), and quantify revenue and margin impacts under multiple demand and price‑shock scenarios.
Closing perspective
As the RNA cleanup market scales toward therapeutics and high‑throughput applications, competitive advantage will accrue not to the company that claims the best chemistry, but to the organization that couples technical excellence with supply resilience, regulatory credibility and seamless automation support. 2026 is a pivotal planning year: choices about supplier strategy, product architecture, and partner ecosystems will determine who captures the disproportionate returns of the next growth phase.
Next steps
This brief outlines the strategic stakes and immediate implications. For access to the full dataset, vendor scorecards, confidential M&A targets, and the step‑by‑step 90‑ to 360‑day implementation playbooks referenced here, please consult the complete PW Consulting Worldwide RNA Cleanup Market report and supporting models on our client portal.
For detailed analysis of this topic, please visit the official page: Worldwide RNA Cleanup Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Naval Vessel MRO Market to Reach USD 89,260 Million by 2032
By pmarketresearch, 2026-08-18
Worldwide Naval Vessel Maintenance, Repair and Overhaul (MRO) Market: Strategic Imperatives for 2026 Decisions
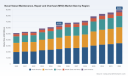
PW Consulting’s newest Worldwide Naval Vessel MRO Market study synthesizes five years of historical performance and a forward-looking forecast to 2032, delivering a rigorous, decision-grade resource for defense planners, shipyard executives, OEMs, and private equity investors preparing for 2026. The market reached approximately USD 64,120 Million in 2025 and is projected to expand to roughly USD 68,315 Million in 2026, with a modeled trajectory that reaches near USD 89,260 Million by 2032 — a 4.84% compound annual growth rate across the 2026–2032 forecast window. This release explains why 2026 is a turning point for strategic investments and operational choices in naval sustainment, and which levers will determine who captures the long-term value.
Worldwide Industrial Arc Furnaces Market
Why 2026 is a Pivotal Year
-
Geopolitics and the shifting maintenance footprint: Recent awards and partnerships, particularly in the Indo‑Pacific, have accelerated allied MRO capacity outside traditional Western hubs. Several South Korean yards have secured high-profile U.S. Navy logistics vessel contracts, underscoring a more distributed approach to fleet sustainment that will affect basing, supply chains, and contingency planning in 2026.
Turntable Slip Rings Market -
Regulatory guardrails that reshape choices: Statutory constraints such as U.S. domestic repair requirements for homeported Navy vessels continue to create a bifurcated market for domestic vs. allied MRO activity. At the same time, defense budget allocation patterns indicate a heavy emphasis on propulsion and dry‑dock workstreams — engine and dry‑dock activities now exceed 55% of reported maintenance spending in several analyses — focusing attention on specialized capability nodes.
Worldwide Impairment Goggles Market -
Cost drivers and operational risk: Raw material and labor dynamics are increasing unit costs for shipyards and sustainment providers. For example, naval‑grade steel prices in Northeast Asia rose to roughly USD 1.81/kg in early 2026, while U.S. shipyard labor income levels remain high and workforce shortages persist, intensifying upward pressure on MRO margins and creating a premium for productivity improvements.
What the Report Delivers — Practical, Executable Intelligence (keeps the granular splits secure)
-
Robust market sizing and trend analysis: A verified historical dataset covering 2020–2025 and a transparent forecasting engine for 2026–2032 that isolates demand drivers by vessel lifecycle stage, service type, and macroeconomic scenarios. The headline market totals and CAGR are published to guide portfolio sizing; granular segment tables and regional detail are included in the full report.
-
Actionable decision frameworks: Bid/no‑bid thresholds for large‑scale depot contracts, investment case templates for greenfield/expansion capex, and contract structuring checklists to minimize revenue volatility from lifecycle peaks.
-
Supply‑chain stress tests and scenario planning: Quantified scenarios modeling commodity spikes, labor constraints, and base‑relocation events, each mapped to P&L impacts and capex timing recommendations.
-
Competitive playbooks and M&A scouting: Empirically grounded profiles of incumbent and emerging MRO players, capability gap maps, and an M&A prioritization matrix that balances strategic fit, regulatory exposure, and integration risk.
-
Operational modernization roadmaps: Step‑by‑step guidance on digital MRO adoption, remote diagnostics, predictive maintenance deployment, and workforce reskilling to lift throughput while protecting quality and compliance.
Competitive Landscape — Who Matters and Why
The global MRO ecosystem remains concentrated around diversified prime integrators and specialty engineering houses. Market concentration metrics show that the top three players hold a meaningful share of industry revenues and that the top five firms capture a clear majority of identifiable market turnover — a structure that favors scale, integrated logistics, and strategic relationships with navies and defense ministries.
-
Huntington Ingalls Industries (Newport News, VA): A dominant US‑flag platform for high‑complexity sustainment — notably nuclear carrier refueling and submarine overhauls — HII’s recent supply‑chain and capacity expansions are explicitly geared to cement lead positions in long‑cycle naval programmes.
-
General Dynamics (Reston, VA): Through its NASSCO and Electric Boat units, General Dynamics provides a geographically diversified sustainment footprint across auxiliary and submarine fleets. Its portfolio emphasizes depot capabilities and multi‑port support lanes.
-
BAE Systems and Babcock (UK): These firms combine dry‑dock heft with systems‑level upgrade and combat‑system sustainment, serving both domestic fleets and export customers via through‑life support contracts.
-
Naval Group, Fincantieri, Navantia, and ThyssenKrupp: European primes that integrate design, newbuild, and refit expertise — their through‑life support offers remain significant for allied and export customers seeking one‑stop sustainment partners.
-
OEM and systems specialists (Rolls‑Royce, Thales, Kongsberg, Lockheed Martin): These companies increasingly capture higher‑margin MRO work around propulsion, sensors, combat systems, and prime electronics through long‑term support contracts and spare‑parts agreements.
-
Regional and niche players (Austal, HD Hyundai, Larsen & Toubro, Damen): These yards compete on rapid turnaround, specialized hull materials (e.g., aluminium), and regional proximity — factors that matter for littoral fleets and logistics ship sustainment.
Recent developments underscore competitive dynamics that will shape 2026 strategic choices: HD Hyundai’s contract wins for logistics‑class vessel overhauls and the entry of Korean yards into U.S. Navy logistics work signal a more competitive global market for auxiliary sustainment; Huntington Ingalls’ acquisitions to strengthen submarine MRO supply chains indicate continued consolidation at the high‑complexity end of the market.
Operational Levers for 2026 Decision‑Making
-
Prioritize capability adjacency over scale alone: Investment in propulsion overhaul capabilities, dry‑dock availability, and nuclear/complex systems know‑how yields premium revenue access. For firms without those capabilities, partnerships or minority stakes in specialists provide faster access than full greenfield builds.
-
Design contracts around predictability: Shift fixed‑price elements to indexed or milestone‑based structures that account for material price swings and labor availability. Hedging strategies for naval‑grade steel and long‑lead components materially reduce margin erosion.
-
Localize selectively to manage regulatory exposure: Understand where domestic repair statutes or basing patterns create protected workstreams versus where allied ports are viable for auxiliary classes. For U.S. Navy homeported assets, domestic compliance remains non‑negotiable; allied hubs can serve logistics and ancillary flows.
-
Invest in digital MRO and workforce productivity: With labor representing a substantial share of ship costs and with skills shortages persistent, adoption of predictive maintenance, augmented reality for diagnostics, and modular tasking models delivers outsized returns on throughput.
-
Adopt a portfolio approach to risk: Balance legacy, high‑complexity work (steady, long‑duration margins) with faster‑turnaround, lower‑duration contracts that smooth revenue and utilize spare capacity between major availabilities.
Implications for Capital Allocation and M&A in 2026
Capital discipline will separate winners. The market’s structural growth (mid‑single digit CAGR across the forecast window) justifies selective capacity expansion, but investments must be prioritized where barriers to entry are highest — nuclear/complex propulsion, integrated combat systems MRO, and strategic dry‑dock assets. M&A targets that offer regulatory advantage, unique technical capabilities, or a foothold in allied basing networks should command premium valuations. Our report provides a prioritized watch list and valuation bands calibrated to 2026 contracting cycles and policy timelines.
How PW Consulting Can Help
-
Customized scenario modeling calibrated to your asset base and contract profile (including commodity and labor stress tests).
-
Bid/no‑bid decision support and contract optimization templates tailored to naval sustainment procurement rules and local content constraints.
-
M&A diligence playbooks and integration roadmaps for acquiring technical specialists or expanding regional repair networks.
Next Steps — Secure the Full Intelligence Package
This bulletin outlines the strategic contours and executive implications of our full Worldwide Naval Vessel MRO Market study. The comprehensive report contains the granular segmentation tables, regional breakdowns, and supplier‑level financial models that underpin the actionable recommendations summarized here. For a copy of the complete report, the M&A watch list, and a tailored briefing on what the 2026 contracting environment means for your organization, please visit PW Consulting’s report page or contact our naval sustainment practice. The full dataset and scenario models are available to subscribers and clients who require decision‑grade detail.
For detailed analysis of this topic, please visit the official page: Worldwide Naval Vessel Maintenance, Repair and Overhaul (MRO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide In‑Car Infotainment Market Set to Expand at a 10.21% CAGR Through 2032, New Report Finds
By pmarketresearch, 2026-08-18
Worldwide In‑Car Infotainment Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
PW Consulting’s new market study on the Worldwide In‑Car Infotainment Market sets the strategic frame for decisions that will define supplier positions, OEM roadmaps, and investor value creation through the rest of this decade. The in‑car infotainment market has accelerated from an early‑decade base to exceed USD 33.6 billion in our 2025 base year and is projected to roughly double by the end of the 2026–2032 forecast window, tracking a compound annual growth rate of approximately 10.21%. That momentum — underpinned by rapid software migration, 5G-enabled experiences, and growing services monetization — creates both urgent opportunities and material risks for market participants planning 2026 investments.
Worldwide Subscription Analytics Software Market
Why 2026 is the strategic inflection point
-
Technology convergence is changing the value equation. The shift to software‑defined vehicle (SDV) architectures, combined with the mainstreaming of Android Automotive and partnerships between chipset and cloud providers, is compressing time‑to‑market for advanced cockpit capabilities. Recent industry moves — including expanded Qualcomm–Google collaboration and OEM supply agreements announced in early 2026 — make platform selection and long‑term supplier commitments high‑stakes decisions this year.
Worldwide 5-Fluorouracil Market -
Regulatory and privacy dynamics are tightening monetization levers. In 2026, new enforcement actions and state‑level privacy rules are reshaping how vehicle data can be collected, shared, and commercialized. Suppliers and OEMs can no longer assume consumer data will remain a free, unrestricted source of value; consent architectures and transparent data governance must be operationalized before new subscription models are launched.
Worldwide Gas Gravitometers Market -
Cost and supply considerations are crystallizing hardware‑software trade‑offs. The industry is balancing the incremental value of 5G and AI features against module, TCU and roadside infrastructure costs. Hardware choices made in 2026 will lock in cost bases and upgrade paths for multiple model cycles — influencing margins and upgrade economics through 2032.
Market dynamics shaping strategic choices
-
Software first, hardware second: Infotainment is migrating from a hardware‑driven product to a software and services platform. Feature differentiation increasingly comes from user experience, AI services, cloud connectivity and OTA update capabilities rather than raw display or audio specs. This accelerates the importance of middleware, lifecycle support, and recurring revenue models.
-
Connectivity and edge compute: 5G and edge services enable new media, safety, and location experiences — but they also introduce new distribution costs. The emergence of retrofitable AI extension platforms and long‑term chipset supply agreements reported in early 2026 demonstrates how the ecosystem is moving to decouple new capabilities from wholesale hardware redesigns.
-
Regulatory and privacy pressure: In 2026 regulators have intensified scrutiny of vehicle data use. Enforcement actions and new consent requirements mean commercial pilots and subscription rollouts must embed privacy‑by‑design and auditable consent flows. Failure to do so risks not just fines, but loss of consumer trust and blocked business models.
-
Consolidation and collaboration: The competitive landscape shows both vertical integration by large Tier‑1s and strategic alliances among chipset vendors, cloud providers and OEMs. This hybrid model strengthens incumbents with platform capabilities while creating white‑space for specialized suppliers that can demonstrate unique services or integration speed.
Competitive landscape — who matters and why
The market is populated by a mix of global Tier‑1s, OEM captive suppliers, consumer electronics entrants, and specialized aftermarket players. Critical firms to watch include established infotainment and cockpit platform providers, audio and head‑unit specialists, and those advancing SDV enablement:
-
Harman International (Samsung) — premium connected infotainment systems, digital cockpit platforms and Android Automotive solutions embedded in many global OEM programs.
-
Robert Bosch GmbH — integrated infotainment and AI cockpit solutions with a growing focus on retrofitable software extensions demonstrated at CES 2026.
-
Continental AG — smart vehicle architectures and biometric features that bridge infotainment with ADAS and domain control strategies.
-
Denso Corporation — deep OEM relationships, telematics expertise, and user‑experience focused solutions aligned with major manufacturing programs.
-
Panasonic (Automotive Systems), Pioneer, Visteon, Aptiv, Alpine/ALPS ALPINE, JVCKENWOOD (Clarion), LG Vehicle Component Solutions, Mitsubishi Electric, Garmin, Hyundai Mobis and FORVIA (Faurecia) — each plays distinct roles across head units, displays, HMI, platform software and integration services.
These companies are simultaneously competitors and partners. Strategic alliances — for example, OEMs locking in chipset roadmaps with large silicon vendors or partnering with cloud/OS providers — will determine who captures platform economics versus who earns integration premiums.
Recent developments with immediate strategic implications
-
Bosch’s January 2026 announcement of an AI extension platform illustrates a practical pathway to retrofit AI capabilities into existing cockpits without full hardware replacement — an attractive option for OEMs seeking feature acceleration while deferring capital‑intensive redesigns.
-
Qualcomm’s expanded collaboration with Google and the Volkswagen Group’s supply intent for Snapdragon Digital Chassis solutions signal that long‑term chipset‑to‑software alliances are central to SDV success. Firms must evaluate supplier roadmaps, update cadences and service layers when negotiating 2026 supply contracts.
-
Toyota’s integration of carrier 5G connectivity in refreshed models shows how OEMs are embedding operator relationships into product offers, a trend that will shape financing and subscription bundles.
-
Regulatory moves — including recent FTC action and accelerated state privacy rules — require companies to reconcile product roadmaps with consent mechanics, data localization and audit trails; these requirements influence not just compliance costs but the feasibility of certain data‑driven services.
What the PW Consulting report delivers (practical, decision‑ready contents)
-
Forward‑looking market model with annualized revenue forecasts across 2026–2032, stress‑test scenarios for alternate technology and regulatory outcomes, and sensitivity analyses tied to hardware cost trajectories and subscription uptake.
-
Strategic supplier heatmaps and capability matrices that map technology ownership, service readiness, and integration risk — enabling procurement teams to prioritize partners by program risk and margin impact.
-
Commercial playbooks for monetization, including subscription rollout sequencing, bundling strategies with connectivity providers, and privacy‑aligned consent frameworks that meet emergent regulatory expectations.
-
Technology roadmaps and scenario planning for 5G, edge compute, AI‑enhanced UX, and OTA architectures — calibrated with component cost inputs and infrastructure considerations to quantify TCO and upgrade economics.
-
M&A and partnership target shortlists based on capability gaps, go‑to‑market acceleration potential, and platform fit — accompanied by valuation sensitivities and integration playbooks.
Actionable recommendations for leaders planning 2026 investments
-
Prioritize platform modularity and OTA lifecycle management. Whether you are an OEM or Tier‑1 integrator, designing for continuous software delivery and decoupled hardware refresh cycles preserves optionality and reduces stranded investment risk.
-
Embed privacy and consent into product architecture today. New enforcement trends mean that subscription and data monetization pilots must include auditable consent flows and data minimization by default — retrofitting these mechanisms later is costly and brand‑damaging.
-
Structure supplier agreements for shared roadmap visibility. Long‑term chipset and cloud relationships are now strategic assets; contracts should include update cadences, security SLAs and co‑development clauses to avoid platform lock‑in or capability gaps.
-
Run parallel hardware‑light and hardware‑heavy scenarios. Bosch’s AI extension approach and similar retrofit strategies offer a lower‑capex path to deliver advanced features; concurrently maintain options for integrated hardware redesigns where OEM differentiation justifies the spend.
-
Quantify infrastructure and lifecycle costs for connectivity. Decision models must include 5G module pricing, TCU economics and potential roadside unit investments when evaluating total cost of ownership and service margins.
How PW Consulting’s insights convert to board‑room decisions
This report is designed to convert market intelligence into executable plans: it aligns financial forecasts with procurement choices, maps competitive moves to partnership opportunities, and ties regulatory scenarios to product and legal risk. For boards and C‑suites preparing budgets and strategic plans in 2026, our analysis clarifies where to allocate incremental capital, which partnerships accelerate time‑to‑market, and how to defensibly price subscription services within tightening privacy regimes.
Next steps
The preview above highlights high‑level conclusions and actionable recommendations drawn from PW Consulting’s full Worldwide In‑Car Infotainment Market report. To preserve the utility of our proprietary segment models and supplier scorecards, we intentionally limit publication of granular splits in this release. The full report includes detailed regional and component-level modeling, supplier concentration analysis, and playbooks tailored to OEMs, Tier‑1s, aftermarket players and financial sponsors.
For access to the comprehensive dataset, scenario models, and executive briefing packages that support 2026 decision cycles, please visit PW Consulting’s report page or contact our research team to schedule a tailored executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide In-Car Infotainment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Automotive Connectivity Control Unit (CCU) Platform Market Set to Surge to USD 11,186.13 Million by 2032 on a 15.62% CAGR
By pmarketresearch, 2026-08-18
Worldwide Automotive Connectivity Control Unit (CCU) Platform Market — Strategic Preview for 2026 Decision-Makers
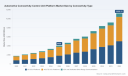
PW Consulting today releases a strategic preview of our forthcoming Worldwide Automotive Connectivity Control Unit Platform Market report. As vehicle architectures pivot toward centralized compute, software-defined functions and multi-modal connectivity, CCU platforms have become a mission-critical node for monetization, safety and fleet operations. Our research projects a robust medium-term expansion — underpinned by a compounded annual growth rate (CAGR) of 15.62% — that turns connectivity hardware decisions made in 2026 into value-creation or value-eroding choices across 2026–2032.
Worldwide Synthetic Lace Front Wigs Market
Why this report matters for 2026
-
Timing: 2026 is the inflection year when early production programs incorporating 5G, satellite-assisted telemetry and consolidated central compute move from pilot to scale. OEMs and Tier-1 suppliers deciding platform architectures this year will lock in technology, supply chain and partner obligations that influence product roadmaps for the next decade.
Worldwide MySQL Training Service Market -
Scale: Our topline market model shows a multi-billion-dollar market expanding substantially through the forecast period, driven by rapid adoption of high-bandwidth telematics, OTA orchestration, and new vehicle-to-cloud business models.
Worldwide Lithium Battery Anode Materials Market -
Concentration and competitive dynamics: The market is partially concentrated among a small set of established Tier-1s and technology players. This creates both consolidation risk and partnership opportunity — a critical input for M&A and procurement strategy.
Report utility — what executives and strategy teams will get
-
Board-grade market sizing and forecast: A rigorous base-year assessment and detailed scenario projections through 2032 that quantify upside under accelerated 5G/NTN adoption and downside under semiconductor constraints.
-
Decision-ready segmentation and architecture analysis: Comparative evaluations of centralized versus zonal approaches, dedicated CCUs versus integrated domain controllers, and the trade-offs in cost, weight, cybersecurity surface, and upgradeability.
-
Supply chain stress tests: Vendor concentration mapping, single-source risk flags, and mitigation playbooks that translate semiconductor shortage or supplier disruption into quantified operational risk metrics.
-
Vendor benchmarking and engagement frameworks: A performance matrix that rates functional capability (e.g., multi-modal connectivity, OTA maturity, edge compute capacity), commercial posture, and integration complexity — enabling rapid shortlisting for design-in and partnership pilots.
-
Commercial models and revenue levers: Paths to capture subscription, data monetization and fleet management revenue, and the implications of software lifecycle economics (e.g., OTA cadence, security updates) on TCO and residual value.
-
Regulatory & standards playbook: Mapping of emerging global standards (digital key, V2X) and a compliance roadmap to minimize time-to-market friction across major jurisdictions.
-
M&A and investment signals: Identification of strategic gaps where bolt-on acquisitions or minority investments unlock capabilities (satellite comms, cybersecurity, OTA cloud orchestration, edge AI) more quickly than in-house builds.
Competitive landscape — what the major players are positioning
-
Robert Bosch GmbH: Continuing to position CCUs as a central connectivity hub, Bosch emphasizes hardware robustness and integration with vehicle-to-cloud services — attractive for OEMs prioritizing deep systems integration and proven automotive-grade supply chains.
-
Continental AG: Focused on telematics control units that align with software-defined vehicle architectures, Continental’s offerings are tailored for OEMs seeking modularity and lifecycle OTA governance.
-
HARMAN International: Notably active on the multimodal front, HARMAN couples telematics units with infotainment ecosystems and has accelerated satellite-native connectivity capabilities through recent partnerships.
-
Aptiv PLC: Aptiv’s emphasis is on high-speed electrical architectures and holistic vehicle compute platforms, which suit programs aiming to minimize wiring complexity while maximizing data throughput.
-
Denso Corporation: Denso continues to be a key player for communications devices and telematics modules, leveraging longstanding OEM relationships in Asia and beyond.
-
LG Electronics: Recent product unveilings highlight LG’s push into 5G telematics with AI-enabled features — positioning for premium segments and next-gen connected services.
-
Visteon Corporation: Visteon’s cockpit and connectivity domain controllers appeal to OEMs pursuing zonal or centralized cockpits that integrate CCU functions for seamless user experiences.
-
AutoCore (China): Emerging platform specialist offering integrated CCU/ZCU solutions and software stacks — a candidate for partnerships or supply diversification on programs prioritizing local sourcing or cost leadership.
Our qualitative and quantitative benchmarking highlights that while legacy Tier-1s bring automotive-grade reliability and deep OEM relationships, newer entrants and semiconductor-aligned players are rapidly closing capability gaps — especially in areas like satellite-native telematics, secure enclave architectures, and integrated modem-software stacks.
Recent market signals that must inform 2026 choices
-
Standards and industry coordination: Initiatives such as the Car Connectivity Consortium’s recent assemblies are accelerating harmonized approaches to digital keys, V2X and fleet management — reducing fragmentation risk but also compressing windows for standards-driven product updates.
-
Technology inflection: The industry shift toward “One Board / One Chip” central compute architectures materially changes CCU design trade-offs — shrinking size and weight but increasing integration complexity and thermal management requirements.
-
Supply-side fragility: Semiconductor interruptions in late 2025 exposed fragilities that continue to affect choice of silicon partners, dual-sourcing strategies and inventory policies. Our supply-chain modules quantify the cost of single-source dependencies and scenario-test buffer strategies.
-
Multi-modal connectivity: The emergence of satellite-enabled telematics and native NTN support elevates resilience and reach for fleet and remote operations — with new partnerships forming between wireless chipset vendors, platform integrators, and telematics specialists.
Implications by stakeholder — practical guidance for the 2026 playbook
-
OEMs and system architects: Prioritize platform decisions that preserve headroom for OTA-driven feature enrichment and ensure modularity to accommodate semiconductor substitution. Evaluate centralized compute not as a cost-saver alone but as a strategic anchor for lifecycle monetization.
-
Tier-1 suppliers: Balance long-term R&D investment in software and cloud orchestration with selective partnerships for radio and satellite front-ends. Use the report’s vendor matrix to structure win-win roadmaps with lead OEM customers.
-
Telecom and cloud providers: Position offerings around managed connectivity bundles, edge-cloud orchestration and security subscriptions rather than raw connectivity, as OEMs seek simplified integration and predictable TCO.
-
Investors and corporate development: Use our M&A heatmaps to identify targets that complement existing stacks — especially those that accelerate access to satellite, secure trust anchors, or OTA platforms without protracted integration timelines.
How to operationalize the insights in 90–180 days
-
Day 0–30: Run a rapid “architecture safety audit” using our checklist to flag single-source risks, thermal constraints and OTA readiness for active programs.
-
Day 30–90: Shortlist a small set of CCU platform partners using our benchmarking matrix and initiate integration pilots that exercise OTA flows, satellite fallbacks and cybersecurity incident response.
-
Day 90–180: Finalize sourcing and partnership contracts with staged delivery milestones tied to interoperability tests, semiconductor resilience clauses and clear IP governance for data monetization.
What we intentionally withhold in this preview
Consistent with the report’s role as a boardroom-grade commercial instrument, this preview intentionally avoids granular disclosure of segment-level revenue splits, regional allocation percentages, and confidential vendor share estimates. Those high-resolution data and the underlying modelling assumptions are core deliverables of the full report and are provided to clients and subscribers to preserve commercial integrity and enable defensible negotiations.
Closing — the strategic value for 2026
Decisions made in 2026 on CCU platforms will have cascading effects across product cost, cybersecurity posture, customer experience and recurring revenue potential. PW Consulting’s report synthesizes market sizing, competitive strategy, supply-chain contingencies and practical execution roadmaps to turn that complexity into executable strategy. With a market trajectory growing at a 15.62% CAGR and clear consolidation pressure among leading suppliers, the choice is not whether to act — it is how to act with precision.
For an executive summary, vendor scorecards and access to the full report and modelling workbooks, visit our Worldwide Automotive Connectivity Control Unit Platform Market page or contact PW Consulting’s Automotive Practice to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Connectivity Control Unit Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Infrastructure-as-a-Service Market to Expand at a 21.04% CAGR Through 2032
By pmarketresearch, 2026-08-18
Worldwide Infrastructure as a Service Market — Strategic Outlook for 2026 Decision-Makers
Executive summary: why this matters for 2026
As enterprises finalize 2026 budgets and multi-year cloud roadmaps, Infrastructure as a Service (IaaS) is no longer a peripheral operational choice — it is a core strategic lever. Our new Worldwide IaaS Market report synthesizes market-scale forecasting, vendor-level competitive mapping, regulatory and energy-cost scenario analysis, and pragmatic buyer playbooks to guide decisions that will shape cost structures, time-to-market, and risk exposure through 2032. The purpose of this executive note is to highlight the report’s strategic value for corporate and public-sector leaders while intentionally omitting the granular segment tables and region/application splits that are available in the full report on our site.
Worldwide Golf Software Market
Market trajectory at a glance
The IaaS market has moved from early rapid adoption to mature, hyperscale-driven expansion. Our historical base (2020–2025) shows a compound acceleration from a global market of approximately USD 64.3 billion in 2020 to USD 248.4 billion in 2025. Looking forward, we model continued high growth with a compounded annual growth rate (CAGR) of 21.04% over the 2026–2032 forecast horizon, driving the market to an estimated USD 944.6 billion by 2032. The 2026 inflection point — projected at roughly USD 290.9 billion — is particularly important for procurement cycles and capital planning: organizations that align sourcing, governance, and architecture decisions with this inflection will capture disproportionate operational and competitive advantages.
Worldwide Electronic Trading Platform Market
Key dynamics shaping 2026 decisions
- AI workload specialization and capex-to-opex trade-offs: Demand for AI-optimized infrastructure is a critical growth vector. Independent forecasts project tens of billions of dollars in end-user spending on AI-optimized IaaS in 2026, with more than half supporting inference workloads. Buyers must translate AI performance requirements into specific instance and networking commitments, balancing on-demand elasticity with reserved capacity economics.
- Energy cost volatility and data center economics: Rising electricity demand at hyperscale is changing TCO math. Published projections show U.S. data center electricity consumption expanding substantially by the later part of the decade, and regionally concentrated grid impacts have already added billions to regional electricity costs. These dynamics make energy-aware placement, renewable contracting, and power-efficiency attributes material factors in vendor selection and long-term sourcing agreements.
- Regulatory friction and data residency: The regulatory backdrop has tightened: rules like the EU Data Act and the NIS2 Directive increase contractual obligations, portability expectations, and cybersecurity responsibilities for IaaS providers and their enterprise customers. Data sovereignty laws across jurisdictions continue to affect where and how enterprises host regulated workloads; these constraints should be embedded in 2026 migration and cloud native architectures.
- Concentration and competitive pressure: Market concentration remains meaningful at the global level. The leading cloud vendors collectively account for the majority of enterprise infrastructure spending, prompting both consolidation strategies and differentiated plays from regional or vertical-focused providers. Procurement teams must weigh the benefits of hyperscale economies against concentration risks and vendor-specific interoperability constraints.
Competitive landscape — what buyers need to know
The competitive field remains anchored by a set of global hyperscalers that dominate enterprise spend and innovation, complemented by enterprise-focused, regional, and developer-centric providers. Recent market recognitions and analyses underscore the current pecking order while also signaling where displacement is possible.
Worldwide HTAP-Enabling In-Memory Computing Technologies Market
- Hyperscalers (AWS, Microsoft Azure, Google Cloud): These providers lead on breadth of compute, storage, networking offerings, global footprint, and partner ecosystems. Independent user-feedback-based awards continue to recognize their strengths in performance, scalability, security, and cost optimization. For 2026 sourcing strategies, expect these vendors to compete on differentiated AI infrastructure, specialized networking services, and deeper enterprise systems integration.
- Enterprise-specialists (Oracle, IBM): Firms with legacy enterprise relationships and database-optimized infrastructure emphasize performance for mission-critical workloads and provide options such as bare-metal compute and tightly coupled storage/networking. They are attractive where workload performance and compliance carry a premium.
- Regional and developer-first players (Alibaba Cloud, Tencent Cloud, OVHcloud, DigitalOcean, Rackspace): Regional providers and developer-focused platforms remain important for geography- and developer-centric strategies. They offer differentiated propositions around data sovereignty, cost predictability, and customer support models tailored to SMBs and specific verticals.
Strategic takeaway: shortlists for 2026 should be constructed by overlaying performance, regional compliance posture, energy footprint, and AI roadmap fit — not by price alone. Our report includes vendor scorecards and battlecards that operationalize these decision criteria for RFPs and Proof-of-Concepts.
What the full report delivers (highly pragmatic content)
- Market sizing and forecasts (2020–2032) with scenario variations and sensitivity to energy and AI adoption assumptions.
- Vendor benchmarking: product capability matrices, TCO templates, go-to-market tactics, and negotiated contract levers.
- Regulatory and compliance playbook: clauses and contract language aligned to the EU Data Act, NIS2, and major data residency regimes.
- Energy and sustainability modelling: location-based electricity scenarios, renewable procurement pathways, and PUE-driven cost differentials.
- Buyer-focused tools: RFP templates, migration sequencing roadmaps, scorecards for hybrid and multi-cloud designs, and AI-workload procurement checklists.
- M&A and partnership guidance: criteria for acquiring cloud-enabled startups, assessing managed-service partners, and structuring reseller alliances.
Note: this summary is intentionally a trailer. Detailed segment tables (regional, solution, vertical splits) and complete vendor financials are available only in the full report and are withheld here to preserve the report’s utility as a primary source for decision-makers.
Strategic implications and recommended actions for 2026
- Adopt a workload-centric sourcing strategy: Classify workloads by performance, security, and sovereignty needs. Route AI inference and training to providers or configurations that demonstrably meet latency, networking, and GPU availability requirements — and document outcomes in procurement scorecards.
- Price energy risk into TCO: Run at least two electricity-cost scenarios (baseline and stress) when comparing regional deployments and include renewable energy contracts as negotiable supplier terms. Factor in grid-impact surcharges where applicable.
- Embed regulatory triggers in contracts: Update standard supplier agreements to include clauses for portability, data access rights, and cybersecurity incident reporting consistent with recent EU directives. Make remediation SLAs and audit rights procurement prerequisites for regulated workloads.
- Design for multivendor resiliency: For critical services, prioritize architectures that reduce lock-in through standard APIs, data export paths, and cross-cloud networking strategies. Use managed services only where the operational uplift outweighs portability risk.
- Negotiate outcome-based pricing for AI workloads: Move from raw capacity pricing to outcome or performance-based arrangements (e.g., per-inference or per-training-hour delivered SLAs) to align vendor incentives with business value.
How to convert this intelligence into board-ready actions
- Create a 90-day procurement playbook using our RFP and scorecard templates to reset vendor terms and capture pricing concessions.
- Run a 12–18 month hybrid migration plan that prioritizes cost, regulatory compliance, and AI performance criteria; short-list vendors for PoCs aligned to this plan.
- Task the CISO with a compliance roadmap tied to NIS2 and the EU Data Act milestones; use our audit checklist to validate vendor commitments.
- Align capital planning with forecasted IaaS market growth and energy scenarios — treat cloud spend as a strategic investment subject to internal chargeback and FinOps discipline.
Closing — next step
For executives and procurement leaders preparing 2026 decisions, the full Worldwide IaaS Market report from PW Consulting provides the quantitative foundation, vendor intelligence, and executable playbooks necessary to convert market growth into advantage. We have intentionally kept this briefing high-level and withheld the full regional, solution, and vertical split tables to ensure the report remains the definitive source for transaction-level decisions. Access the full report and supporting tools on the PW Consulting insights page to download detailed tables, vendor scorecards, and TCO models.
For detailed analysis of this topic, please visit the official page: Worldwide Infrastructure as a Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Synchronous Buck Converter Market to Rise from USD 4,625.5 Million in Base Year 2025 to USD 7,211.62 Million by 2032 at a 6.55% CAGR (2026–2032); Asia Pacific Leads with USD 2,156.73M
By pmarketresearch, 2026-08-18
Worldwide Synchronous Buck Converter Market: Strategic Outlook and Tactical Playbook for 2026
Executive summary
The Worldwide Synchronous Buck Converter Market is entering a phase of steady expansion and structural change that will shape corporate decisions in 2026 and beyond. According to PW Consulting’s latest report (base year 2025; historical window 2020–2025; forecast period 2026–2032), the market has grown from roughly 3.38 billion USD (2020) to about 4.63 billion USD in 2025, and is projected to approach 7.21 billion USD by 2032, representing a compounded annual growth rate (CAGR) of approximately 6.55% across the forecast window. The first forecast year, 2026, marks a continuation of growth (with an expected market size near 4.89 billion USD) and sets the stage for inflection points driven by wide-bandgap adoption, modularization in data-center power, and electrification in transportation.
Worldwide Proactive Notification Software Market
Why this matters for 2026 decision-makers
-
Timing matters: 2026 will be the first full planning cycle where executives can act on near-term forecasts that incorporate recent changes in supply-chain dynamics, lead-time normalization, and accelerating GaN/SiC deployments. Early movers who align product roadmaps, procurement, and go‑to‑market (GTM) plans to these shifts stand to capture disproportionate share gains.
Worldwide Healthcare Inventory Management Market -
Margin leverage through technology: Efficiency gains from wide-bandgap semiconductors and integration strategies are creating opportunities to reduce BOM cost, shrink system size, and raise power density. These are not incremental engineering tweaks — they affect product architecture choices, supplier selection, and serviceable addressable markets.
Worldwide AI in IoT Market -
Concentration and partner dynamics: The market exhibits moderate concentration (CR3 ≈ 38.5%, CR5 ≈ 52.1%), which means vendor decisions (both for sourcing and strategic partnerships) will materially influence timelines for qualification, design wins, and pricing dynamics in 2026.
-
Risk vs. reward in verticals: Growth trajectories vary by end-application and operating-voltage strategies. For procurement, R&D and corporate strategy teams, the immediate priority in 2026 is to map internal roadmaps to supplier capabilities and to design flexible architectures that tolerate second-source substitution.
What PW Consulting’s report delivers to executives and practitioners
This release is intentionally operational. Beyond headline forecasts and market sizing, the report provides a toolkit for action that supports board-level and product-team decision-making in 2026:
-
Forward-looking market model: A transparent model that spans 2026–2032 with scenario toggles (base, conservative, and accelerated) to stress-test revenue, unit, and component assumptions against adoption curves for GaN/SiC and multi-phase topologies.
-
Vendor intelligence and sourcing playbook: Detailed vendor profiles, gap analyses, and qualifying checklists tailored to common procurement constraints (thermal envelope, VIN range, EMI, and packaging). Profiles include product positioning, system-level trade-offs, and relative strength mapping for leading suppliers.
-
Technology roadmaps and switch-cost analysis: Comparative analysis of silicon MOSFETs, GaN, and SiC for typical buck topologies, including switching-frequency impacts on passive counts, thermal management trade-offs, and expected efficiency deltas that matter for system-level TCO.
-
Design‑win playbook: Practical guidance on reducing qualification cycles, accelerating reference-design uptake, and leveraging evaluation platforms to compress time‑to‑market for high-power-density solutions.
-
Regulatory and supply-chain risk matrix: Actionable mitigation strategies against export controls, geo-political disruption, and critical‑materials scarcity, aligned to sourcing scenarios and multi-year procurement commitments.
-
M&A and partnership screening: A prioritized list of strategic tuck‑ins and technology partners keyed to capability gaps (GaN integration, driver ICs, packaging, and reference‑design ecosystems) and backed by valuation heuristics informed by market concentration dynamics.
Competitive landscape — who matters and why
The report assesses incumbent suppliers and emergent specialists with a focus on capability, roadmap clarity, and ecosystem leverage. A non‑exhaustive synthesis of core players highlights the tactical choices firms need to make in 2026:
-
Texas Instruments — Broad portfolio depth and reference‑design breadth make TI the default partner for companies prioritizing design velocity and proven integration. Recent launches in high-voltage and GaN‑compatible modules underscore a push towards high power density reference platforms that accelerate OEM adoption.
-
STMicroelectronics — Strength lies in monolithic solutions with automotive-grade qualification. ST’s route to market is particularly compelling for manufacturers needing AEC‑Q100 qualified parts for harsh environments and for EV gate/traction auxiliaries.
-
Infineon Technologies — Infineon’s emphasis on thermal performance and system-level efficiency addresses the twin pressures of higher power density and stringent thermal design in computing and industrial systems.
-
Analog Devices — Multi‑phase controllers and high-density regulator ecosystems align Analog Devices well with data-center and HPC power architects pursuing scalable, synchronized voltage regulation.
-
ON Semiconductor, ROHM, Microchip, Renesas, Diodes Inc. — These vendors fill crucial niches across consumer, embedded, and automotive markets. Notably, recent product introductions (e.g., low-IQ, I²C-enabled buck converters and integrated-FET series) shift the balance toward compact, low‑standby-loss designs favored in portable and edge systems.
-
Efficient Power Conversion (EPC) — As a GaN-focused specialist, EPC’s evaluation boards and reference designs compress prototyping cycles for high‑power USB-PD and other point-of-load use cases; their ecosystem work materially reduces integration risk for OEMs pursuing GaN adoption.
Recent product and ecosystem developments (what to track in 2026)
-
Low‑IQ, smart-interface converters (e.g., I²C-enabled devices) are enabling system-level power management strategies that reduce idle losses — a differentiator for battery-powered and low‑power edge equipment.
-
GaN-based evaluation platforms and high‑VIN/high‑current GaN solutions are shortening design cycles for high power‑density applications such as USB‑PD and point‑of‑load regulation in servers.
-
Reference designs from both incumbents and specialists are becoming strategic assets. Manufacturers that leverage these ecosystems can reduce qualification time and secure early design wins in 2026 product cycles.
Technology and supply-chain dynamics shaping 2026 decisions
Three interlinked dynamics will drive procurement, R&D, and partnership priorities next year:
-
Wide‑bandgap adoption: Measurable efficiency gains (typically low‑single-digit percentage points at system level) and higher switching frequencies are enabling smaller passives and higher power density. Choosing when and where to adopt GaN/SiC will be a central trade‑off between BOM volatility and long‑term system competitiveness.
-
Geopolitical and onshoring pressures: Export controls and reshoring initiatives are affecting supplier maps and contractual terms. Manufacturers with global supply footprints must build contingency into 2026 sourcing arrangements and prioritize dual‑sourcing strategies for key wide‑bandgap components.
-
Normalized lead times: Lead times have improved markedly from their 2022 peak; this easing allows design teams to move from speculative buffer stock to leaner inventory strategies — but only if they can secure predictable supply from qualified second sources.
Scenario implications and tactical recommendations for 2026
-
For product leaders: Adopt a staged GaN integration roadmap tied to specific thermal and efficiency KPIs. Use evaluation‑board proof points to accelerate internal buy‑in and allocate NPI budget to packaging and EMI mitigation early in the design cycle.
-
For procurement and supply-chain heads: Negotiate conditional multi‑year volume commitments with clauses that account for lead‑time variability and export control risks. Design qualification pathways that permit rapid cross‑qualification of functionally equivalent parts from at least two vendors.
-
For corporate strategy and M&A teams: Prioritize tuck‑ins that accelerate GaN/SiC integration, packaging expertise, or reference‑design ecosystems. Pay attention to targets that provide near-term synergies in data‑center and automotive power modules.
-
For investors and market analysts: Monitor adoption velocity in high-growth subsegments where modularization and efficiency offer structural margin expansion opportunities. Leading indicators include reference‑design throughput, design‑win announcements, and ecosystem demos at trade events.
How to use this report — and where to find the hidden detail
PW Consulting’s report is designed as both an executive briefing and an operational playbook. It combines a defensible top‑down market model (with a 6.55% CAGR baseline), scenario analysis, supplier deep dives, and tactical checklists that teams can integrate into 2026 plans within weeks.
Consistent with our “trailer” approach to industry intelligence, this article highlights strategic findings and actionable directions while intentionally withholding the granular segmentation tables and application‑level revenue breakdowns that subscribers use for detailed planning. Those breakdowns — including voltage- and application-level forecasts, region-level scenarios, and supplier-specific revenue shares — are available in the full report and the interactive data workbook on our site.
Next steps
For executives preparing 2026 roadmaps: schedule a briefing with PW Consulting to map the report’s scenarios to your product pipeline and supplier base. For engineering teams: use the report’s vendor‑evaluation templates to accelerate qualification of wide‑bandgap and integrated‑FET solutions. For investors: request the full dataset to model M&A and valuation scenarios that reflect shifting concentration dynamics.
Detailed segmentation, downloadable models, and vendor scorecards are hosted on our report landing page — contact PW Consulting for access and to arrange a tailored workshop that translates insights into prioritized actions for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Synchronous Buck Converter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Enterprise IP Phones Market Poised for 4.82% CAGR Through 2032
By pmarketresearch, 2026-08-18
Worldwide Enterprise IP Phones Market 2026: Strategic Imperatives for Procurement, Deployment, and Vendor Strategy
As organizations plan communications investments for 2026, the enterprise IP phones market sits at the intersection of legacy migration, sustainability mandates, and distributed work models. PW Consulting’s newest market research — covering historical performance (2020–2025) and a forward-looking forecast (2026–2032) — projects the global enterprise IP phones market to grow from USD 3,230.2 Million in 2025 to USD 4,491.1 Million by 2032, representing a compound annual growth rate (CAGR) of 4.82% over the forecast horizon. This report is designed to convert market-level insight into immediate, risk-adjusted actions for procurement teams, IT leaders, and corporate strategists in 2026.
Household Copper Wire Market
Why this report matters for 2026 decision-makers
-
Timing investments against infrastructure transitions: Regulatory moves and carrier network upgrades are accelerating decisions. The FCC’s rules accelerating legacy copper retirements (March 2026) mean enterprises must coordinate device refreshes with carrier transition timelines to avoid stranded assets and service disruptions.
Worldwide Excavator Multi-Processors Market -
Managing TCO under constrained energy and construction dynamics: Large-scale data center and network expansion is reshaping where voice platforms run. With significant data center construction and grid-access pressures in North America and beyond, procurement strategies must now embed energy, colocation, and edge costs into device lifecycle models.
Medical Atomization Disinfection Machine Market -
Balancing cloud migration, sovereignty, and on-prem risk: Growing data-sovereignty and privacy mandates are prompting hybrid architecture decisions. The right blend of on-premises survivability and cloud-hosted UC services optimizes compliance and latency without sacrificing cost-efficiency.
What’s in the PW Consulting report (practical, executable content)
-
Market sizing and trend intelligence: A validated historical series (2020–2025) and a granular forecast through 2032 that quantify market expansion drivers and cyclical risks at the global level.
-
Vendor benchmarking framework: A comparative scorecard that assesses product breadth, enterprise feature parity (QoS, PoE profiles, handset security), cloud readiness, and sustainability credentials across established and emerging vendors.
-
Procurement playbook: Ready-to-use RFP language, total cost of ownership (TCO) templates that fold in energy and lifecycle disposal costs, and a supplier negotiation checklist focused on warranty, SLA, and future compatibility clauses.
-
Deployment and migration blueprints: Step-by-step approaches for mass rollouts, staged migrations from TDM to SIP, hybrid on-prem/cloud operational models, and a plug-and-play reference architecture for edge-enabled UC stacks.
-
Risk and resilience checklist: Guidance on supply-chain contingencies, spare-parts strategy, firmware lifecycle management, and incident response planning for large distributed deployments.
-
ROI and use-case models: Sector-tailored (enterprise, SMB, public sector) ROI calculators and scenario analyses to prioritize refresh waves and justify capex versus opex decisions.
Competitive landscape — who matters and why
The market displays moderate concentration, with the top three players capturing a majority share and the top five commanding a dominant position. This concentration dynamic favors established vendors with broad channel ecosystems and enterprise services, but it also creates openings for niche suppliers that excel in interoperability, cost-efficiency, or vertical specialization.
-
Cisco Systems, Inc. — Market leader with enterprise-grade offerings (e.g., AI-enhanced desk phones supporting hybrid deployments). Cisco’s strength lies in deep integration with carrier-class platforms and a broad installed base within large corporations. Its sustainability messaging and PhoneOS support across cloud and on-prem platforms make it a default incumbency choice for many Fortune-level customers.
-
Yealink — Aggressive portfolio refreshes targeting scale and feature parity. Yealink’s extended SIP/VoIP lineup and integration with leading collaboration platforms make it a go-to for organizations seeking a balance of functionality and value.
-
HP Poly — Differentiates through audio innovation and noise-cancellation technologies, with a clear focus on contact centers and dense office environments where audio quality directly affects productivity.
-
Grandstream — Plays to volume deployment and cost-efficiency, with ongoing firmware and energy-optimization efforts that reduce operational consumption — an increasingly important procurement criterion.
-
Mitel, Avaya, Alcatel‑Lucent Enterprise, Snom, Fanvil — Each brings specific strengths: hybrid deployment support, security-focused interoperability, high-audio-fidelity for regulated industries, or cost-sensitive device portfolios for SMBs. These suppliers often serve as important alternatives for verticalized procurement strategies.
Recent vendor moves that reshape procurement calculus
-
New product introductions with embedded AI audio and hot-desking features indicate a rapid feature convergence between high-end desk phones and UC clients. Expect buyers to demand firmware roadmaps and upgrade guarantees for AI-enabled capabilities introduced in 2025–2026.
-
Energy-saving firmware updates and long-range Wi‑Fi/DECT options have shifted the selection criteria from pure device cost to lifecycle energy consumption and wireless enablement. Vendors posting demonstrable energy reductions will gain procurement preference where sustainability and operating expense reductions are executive priorities.
-
Catalog refreshes focused on platform interoperability (Teams/Zoom and SIP) emphasize the need for interoperability testing and certification language in procurement contracts to avoid integration latency or administrative overhead.
Regulatory and infrastructure developments shaping strategy
-
Carrier network modernization: Accelerated retirement of copper networks is compressing migration timelines. Enterprises must map device refresh schedules to carrier migration plans to minimize service disruption and avoid double-spend on transitional infrastructure.
-
Energy and grid constraints: Large-scale data center construction and related grid demands have implications for hosting and edge models. Organizations should include energy cost projections and grid-availability risk in decisions about centralized versus edge-hosted voice platforms.
-
Geo-economic and trade shifts: Tariffs, equipment restrictions, and sovereignty requirements are materially increasing procurement complexity. Strategic sourcing now requires multi-jurisdictional compliance checks, alternative supplier qualification, and contingency inventory planning.
-
Data sovereignty: Continued pressure for localized compute and storage is pushing more UC workloads closer to the edge. This affects handset selection (local survivability features) and service architecture (local SBCs, edge compute nodes).
Actionable recommendations for 2026
-
Adopt a phased, risk-weighted refresh approach. Prioritize endpoints in regulatory-exposed sites and high-utilization contact centers for early replacement; defer low-utilization rollouts to align with carrier migration windows.
-
Shift procurement evaluation from capex-only to lifecycle cost metrics. Tender responses should be scored on energy consumption profiles, firmware upgrade policies, and end-of-life recycling/sustainability commitments.
-
Negotiate portability and interoperability clauses. Require vendors to commit to protocol openness, certified integrations with your UC platforms, and extended security patch support to minimize vendor lock-in risks.
-
Embed contingency inventory and retrofit plans into contracts to account for supply-chain variability and geopolitical risk. Specify accelerated provisioning SLAs for locations deemed mission-critical.
-
Incorporate edge-readiness into architecture decisions. Where data sovereignty or latency are binding constraints, design for SBCs and survivable gateways at the edge and procure devices with proven local survivability modes.
-
Leverage vendor diversity strategically. Where concentration risk is acceptable, consolidate for volume and managed services; where sovereignty or vertical specialization matters, segment purchasing to include niche suppliers.
Where the full report adds value (and why this summary is purposefully high-level)
This briefing provides the strategic contours and operational imperatives you need to set 2026 priorities. The full PW Consulting Worldwide Enterprise IP Phones Market report, however, contains the granular decision-enabling components we intentionally omit here: the detailed regional and application-level splits, model-level revenue trajectories, per-vendor feature scoring matrices, and downloadable RFP/TCO templates. Those items are the outcome of primary vendor interviews, procurement-scenario simulations, and rigorous sensitivity testing — and they are provided in the full report for clients making contractual or capital-allocation commitments.
Final word — positioning for resilience and value in 2026
For enterprise leaders, 2026 is a year to convert macro pressure into tactical advantage. The market’s steady growth trajectory underscores persistent demand for purpose-built endpoints, but success will hinge on how organizations integrate regulatory watchfulness, energy and data-sovereignty constraints, and vendor resilience into their procurement and deployment playbooks. PW Consulting’s report is designed to be both a map and a manual: mapping the market’s direction and providing the operational instruments to execute with confidence.
For access to the full dataset, vendor matrices, and procurement toolkits, visit the PW Consulting report center or contact our advisory team to schedule a briefing tailored to your organization’s objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Enterprise IP Phones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com