

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
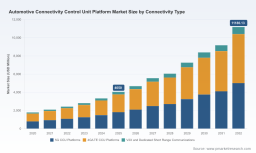
PW Consulting: Worldwide Automotive Connectivity Control Unit (CCU) Platform Market Set to Surge to USD 11,186.13 Million by 2032 on a 15.62% CAGR

Worldwide Automotive Connectivity Control Unit (CCU) Platform Market — Strategic Preview for 2026 Decision-Makers
PW Consulting today releases a strategic preview of our forthcoming Worldwide Automotive Connectivity Control Unit Platform Market report. As vehicle architectures pivot toward centralized compute, software-defined functions and multi-modal connectivity, CCU platforms have become a mission-critical node for monetization, safety and fleet operations. Our research projects a robust medium-term expansion — underpinned by a compounded annual growth rate (CAGR) of 15.62% — that turns connectivity hardware decisions made in 2026 into value-creation or value-eroding choices across 2026–2032.
Worldwide Synthetic Lace Front Wigs Market
Why this report matters for 2026
-
Timing: 2026 is the inflection year when early production programs incorporating 5G, satellite-assisted telemetry and consolidated central compute move from pilot to scale. OEMs and Tier-1 suppliers deciding platform architectures this year will lock in technology, supply chain and partner obligations that influence product roadmaps for the next decade.
Worldwide MySQL Training Service Market -
Scale: Our topline market model shows a multi-billion-dollar market expanding substantially through the forecast period, driven by rapid adoption of high-bandwidth telematics, OTA orchestration, and new vehicle-to-cloud business models.
Worldwide Lithium Battery Anode Materials Market -
Concentration and competitive dynamics: The market is partially concentrated among a small set of established Tier-1s and technology players. This creates both consolidation risk and partnership opportunity — a critical input for M&A and procurement strategy.
Report utility — what executives and strategy teams will get
-
Board-grade market sizing and forecast: A rigorous base-year assessment and detailed scenario projections through 2032 that quantify upside under accelerated 5G/NTN adoption and downside under semiconductor constraints.
-
Decision-ready segmentation and architecture analysis: Comparative evaluations of centralized versus zonal approaches, dedicated CCUs versus integrated domain controllers, and the trade-offs in cost, weight, cybersecurity surface, and upgradeability.
-
Supply chain stress tests: Vendor concentration mapping, single-source risk flags, and mitigation playbooks that translate semiconductor shortage or supplier disruption into quantified operational risk metrics.
-
Vendor benchmarking and engagement frameworks: A performance matrix that rates functional capability (e.g., multi-modal connectivity, OTA maturity, edge compute capacity), commercial posture, and integration complexity — enabling rapid shortlisting for design-in and partnership pilots.
-
Commercial models and revenue levers: Paths to capture subscription, data monetization and fleet management revenue, and the implications of software lifecycle economics (e.g., OTA cadence, security updates) on TCO and residual value.
-
Regulatory & standards playbook: Mapping of emerging global standards (digital key, V2X) and a compliance roadmap to minimize time-to-market friction across major jurisdictions.
-
M&A and investment signals: Identification of strategic gaps where bolt-on acquisitions or minority investments unlock capabilities (satellite comms, cybersecurity, OTA cloud orchestration, edge AI) more quickly than in-house builds.
Competitive landscape — what the major players are positioning
-
Robert Bosch GmbH: Continuing to position CCUs as a central connectivity hub, Bosch emphasizes hardware robustness and integration with vehicle-to-cloud services — attractive for OEMs prioritizing deep systems integration and proven automotive-grade supply chains.
-
Continental AG: Focused on telematics control units that align with software-defined vehicle architectures, Continental’s offerings are tailored for OEMs seeking modularity and lifecycle OTA governance.
-
HARMAN International: Notably active on the multimodal front, HARMAN couples telematics units with infotainment ecosystems and has accelerated satellite-native connectivity capabilities through recent partnerships.
-
Aptiv PLC: Aptiv’s emphasis is on high-speed electrical architectures and holistic vehicle compute platforms, which suit programs aiming to minimize wiring complexity while maximizing data throughput.
-
Denso Corporation: Denso continues to be a key player for communications devices and telematics modules, leveraging longstanding OEM relationships in Asia and beyond.
-
LG Electronics: Recent product unveilings highlight LG’s push into 5G telematics with AI-enabled features — positioning for premium segments and next-gen connected services.
-
Visteon Corporation: Visteon’s cockpit and connectivity domain controllers appeal to OEMs pursuing zonal or centralized cockpits that integrate CCU functions for seamless user experiences.
-
AutoCore (China): Emerging platform specialist offering integrated CCU/ZCU solutions and software stacks — a candidate for partnerships or supply diversification on programs prioritizing local sourcing or cost leadership.
Our qualitative and quantitative benchmarking highlights that while legacy Tier-1s bring automotive-grade reliability and deep OEM relationships, newer entrants and semiconductor-aligned players are rapidly closing capability gaps — especially in areas like satellite-native telematics, secure enclave architectures, and integrated modem-software stacks.
Recent market signals that must inform 2026 choices
-
Standards and industry coordination: Initiatives such as the Car Connectivity Consortium’s recent assemblies are accelerating harmonized approaches to digital keys, V2X and fleet management — reducing fragmentation risk but also compressing windows for standards-driven product updates.
-
Technology inflection: The industry shift toward “One Board / One Chip” central compute architectures materially changes CCU design trade-offs — shrinking size and weight but increasing integration complexity and thermal management requirements.
-
Supply-side fragility: Semiconductor interruptions in late 2025 exposed fragilities that continue to affect choice of silicon partners, dual-sourcing strategies and inventory policies. Our supply-chain modules quantify the cost of single-source dependencies and scenario-test buffer strategies.
-
Multi-modal connectivity: The emergence of satellite-enabled telematics and native NTN support elevates resilience and reach for fleet and remote operations — with new partnerships forming between wireless chipset vendors, platform integrators, and telematics specialists.
Implications by stakeholder — practical guidance for the 2026 playbook
-
OEMs and system architects: Prioritize platform decisions that preserve headroom for OTA-driven feature enrichment and ensure modularity to accommodate semiconductor substitution. Evaluate centralized compute not as a cost-saver alone but as a strategic anchor for lifecycle monetization.
-
Tier-1 suppliers: Balance long-term R&D investment in software and cloud orchestration with selective partnerships for radio and satellite front-ends. Use the report’s vendor matrix to structure win-win roadmaps with lead OEM customers.
-
Telecom and cloud providers: Position offerings around managed connectivity bundles, edge-cloud orchestration and security subscriptions rather than raw connectivity, as OEMs seek simplified integration and predictable TCO.
-
Investors and corporate development: Use our M&A heatmaps to identify targets that complement existing stacks — especially those that accelerate access to satellite, secure trust anchors, or OTA platforms without protracted integration timelines.
How to operationalize the insights in 90–180 days
-
Day 0–30: Run a rapid “architecture safety audit” using our checklist to flag single-source risks, thermal constraints and OTA readiness for active programs.
-
Day 30–90: Shortlist a small set of CCU platform partners using our benchmarking matrix and initiate integration pilots that exercise OTA flows, satellite fallbacks and cybersecurity incident response.
-
Day 90–180: Finalize sourcing and partnership contracts with staged delivery milestones tied to interoperability tests, semiconductor resilience clauses and clear IP governance for data monetization.
What we intentionally withhold in this preview
Consistent with the report’s role as a boardroom-grade commercial instrument, this preview intentionally avoids granular disclosure of segment-level revenue splits, regional allocation percentages, and confidential vendor share estimates. Those high-resolution data and the underlying modelling assumptions are core deliverables of the full report and are provided to clients and subscribers to preserve commercial integrity and enable defensible negotiations.
Closing — the strategic value for 2026
Decisions made in 2026 on CCU platforms will have cascading effects across product cost, cybersecurity posture, customer experience and recurring revenue potential. PW Consulting’s report synthesizes market sizing, competitive strategy, supply-chain contingencies and practical execution roadmaps to turn that complexity into executable strategy. With a market trajectory growing at a 15.62% CAGR and clear consolidation pressure among leading suppliers, the choice is not whether to act — it is how to act with precision.
For an executive summary, vendor scorecards and access to the full report and modelling workbooks, visit our Worldwide Automotive Connectivity Control Unit Platform Market page or contact PW Consulting’s Automotive Practice to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Connectivity Control Unit Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com