

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Diclofenac Transdermal Patches Market Poised to Expand at a 6.5% CAGR Through 2032

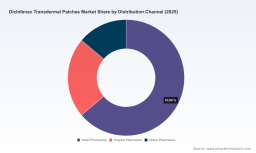
Worldwide Diclofenac Transdermal Patches Market: Strategic Imperatives for 2026
Executive summary
As healthcare systems accelerate shifts toward non-opioid pain management and payers sharpen reimbursement criteria, diclofenac transdermal patches have entered a new phase of strategic relevance. PW Consulting’s latest market study positions the worldwide diclofenac transdermal patches market at USD 648.55 Million in 2025, having grown from a mid-single‑hundred million base in 2020. Under a 6.5% compound annual growth rate (CAGR), the market is projected to approach roughly USD 1.01 Billion by 2032. This trajectory reflects a steady, durable expansion driven by clinical preference for topical NSAIDs, regulatory convergence on combination‑product quality, and new commercial pathways such as authorized generics and payer-led non‑opioid programs.
Translational Chip Testing and Sorting Machine Market
Why this report matters for 2026 decision-makers
- Actionable foresight: The study translates macro momentum into decision-ready scenarios for 2026—detailing where to prioritize manufacturing scale, commercial investment, and regulatory preparation.
- Market structure insights: While the category remains competitive, concentration metrics indicate meaningful scale benefits—top-three incumbent positions account for under half the market while the top five approach two-thirds—creating both competitive pressure and acquisition opportunities for mid‑sized players.
- Risk‑aware growth planning: The report integrates regulation, reimbursement, and safety risk layers (including the implications of boxed warnings and combination‑product oversight) into go‑to‑market models so executives can size opportunity against foreseeable constraints.
Core market dynamics shaping 2026 strategies
Four converging forces will define priorities for the coming year.
Worldwide Hydro Stoves Market
- Payer and clinical preference shifts: Public and private payers in several markets are actively emphasizing non‑opioid pain pathways in outpatient and post‑operative care. Inclusion in payer policies and favorable reimbursement criteria are increasingly decisive for adoption in ambulatory settings.
- Regulatory intensity for combination products: Transdermal diclofenac systems are regulated as combination products in several major jurisdictions, requiring stringent compliance with cGMP and device‑quality expectations. This raises the bar for manufacturing and quality assurance investments.
- Product differentiation via formulation and delivery: Hydrogel systems enabling extended (e.g., 12‑hour) relief, patch size and reservoir design, and variations in diclofenac salt forms create meaningful clinical and commercial differentiation points that affect prescribing and patient adherence.
- Commercial mechanics—brand, authorized generics, and access programs: Brand‑originator programs (including copay and direct patient assistance) coexist alongside authorized generics, creating a two‑front commercial playbook for price competitiveness and brand protection.
Strategic implications and recommended actions for 2026
- Prioritize payer engagement and evidence generation: Secure formulary placement through targeted real‑world evidence (RWE) and health economic dossiers that demonstrate topical NSAIDs’ benefits in reducing opioid exposure and improving recovery metrics.
- Invest in manufacturing and quality infrastructure: Given combination‑product regulation and the premium on consistent delivery performance, scale up cGMP‑aligned production, supplier qualification, and device testing to reduce regulatory and supply risk.
- Pursue flexible commercialization models: Evaluate authorized generic strategies, co‑promotion and licensing deals, and patient assistance programs as mechanisms to protect share while participating in price‑sensitive channels.
- Differentiate clinically and commercially: Leverage unique delivery technologies (e.g., hydrogel patches providing extended relief) and adherence‑focused support to command premium positioning versus commodity patches.
- Scan for value‑accretive M&A and manufacturing partnerships: Moderate top‑end concentration creates buy‑and‑build opportunities—target bolt‑on assets that add formulation expertise, geographic reach, or contract‑manufacturing capacity.
Competitive landscape — who matters and why
The player set comprises brand originators, global generics houses, specialist manufacturers, and integrated local producers. A succinct assessment of leading strategic positions follows:
Worldwide Anti Mould Paints Market
- IBSA Institut Biochimique SA (IBSA Pharma Inc.): The originator position remains strategically valuable because it anchors clinical recognition and payer discussions. IBSA’s branded topical system leverages hydrogel technology, extended relief claims, and proactive patient access programs—factors that sustain premium positioning even as generic alternatives proliferate. Recent updates to prescribing information and inclusion in payer policies underscore an active lifecycle management approach.
- Teva Pharmaceutical Industries Ltd.: As a major generics player, Teva’s presence with an authorized generic equivalent provides immediate scale and channel penetration. Large‑scale generics capability can rapidly commoditize pricing, making Teva a key competitor for volume‑oriented channels.
- Yaral Pharma (IBSA affiliate): Positioning as an authorized generic from the originator group enables a two‑tier commercial strategy: retain premium brand positioning while capturing price‑sensitive segments through an identical, lower‑cost alternative.
- Contract and specialist manufacturers (e.g., Teikoku Seiyaku, Sparsha Pharma, Gangwal Healthcare): Their cGMP transdermal capabilities are strategic enablers for sponsors seeking rapid scale or geographic diversification. Outsourcing to experienced patch manufacturers minimizes time‑to‑market and capital expenditure but requires careful supplier qualification to meet combination‑product expectations.
- Regional formulary players (selected local healthcare companies): Companies marketing diethylamine and sodium salt forms bring localized access and familiarity with national prescribing patterns—useful acquisition targets for players seeking market entry or broader product portfolios.
Regulatory and safety considerations
Executives must treat regulatory and safety developments as strategic variables rather than compliance checkboxes. Diclofenac topical systems carry class‑level cardiovascular and gastrointestinal safety considerations and peri‑operative contraindications that influence labeling, patient selection, and payer policy language. Notably, regulatory updates to prescribing information and payer policy inclusions over the last 18 months signal ongoing scrutiny; forward plans should include robust pharmacovigilance, targeted post‑marketing studies, and label management strategies aligned with global regulators’ combination‑product expectations.
What PW Consulting’s report delivers to operational teams
The report is structured to move executives from insight to execution. Highlights include:
- Financial models: rolling forecasts from 2026 through 2032 with scenario toggles for pricing, uptake, and reimbursement shocks calibrated to a 6.5% base CAGR and built off a 2025 market benchmark.
- Competitive playbooks: granular profiles of originators, generics, and specialist manufacturers with assessed strategic levers and likely near‑term moves.
- Go‑to‑market tools: payer engagement templates, launch sequencing plans, and contracting strategies for both branded and authorized generic approaches.
- Manufacturing and supply‑chain maps: capacity assessments, CMO shortlists, and risk mitigation checklists tailored to combination‑product production.
- Regulatory and safety matrix: jurisdictional requirements, label‑change risk assessments, and recommended post‑launch evidence strategies.
- M&A and partnership screening: diligence frameworks and candidate shortlists aligned to specific corporate objectives (scale, portfolio diversification, or capability acquisition).
To preserve competitive value for subscribing clients, the report intentionally withholds raw breakdowns of certain sub‑segment revenue shares and regional splits in this public summary. These detailed tables and interactive dashboards are accessible in the full report package.
Immediate actions recommended for 2026 planning cycles
- Embed payer evidence generation into 2026 budgets—allocate resources for targeted RWE and health economic modeling that aligns with non‑opioid performance metrics.
- Qualify at least two cGMP transdermal manufacturers for commercial supply to mitigate regulatory and capacity risk.
- Run rapid commercial scenarios evaluating authorized‑generic launch versus co‑promotion with brand originators to select the most value‑accretive pathway.
- Establish a safety‑communications and label‑management task force to proactively address regulatory updates and payer policy shifts.
- Scan and prioritize acquisition or partnership targets that fill key capability gaps—formulation science, device engineering, or regional distribution.
Concluding viewpoint
Diclofenac transdermal patches occupy a strategic intersection of clinical utility, payer interest, and manufacturing complexity. The category’s steady compound growth—anchored by a 6.5% CAGR to a near‑billion‑dollar opportunity by 2032—rewards players that combine rigorous regulatory compliance, clinical differentiation, and flexible commercial models. For 2026 planning, the signal is clear: investment in manufacturing quality, payer evidence, and differentiated delivery technology will determine which organizations capture sustainable share. PW Consulting’s report converts these high‑level signals into executable programs for teams ready to move from assessment to action.
About PW Consulting
PW Consulting is a specialty strategy advisor to healthcare executives, combining market analytics, regulatory insight, and commercial execution frameworks. This study leverages an historical data series (2020–2025), a 2025 base year, and forward projections covering 2026–2032. For access to the full dataset, segmented tables, interactive models, and bespoke advisory engagement, please consult the complete Worldwide Diclofenac Transdermal Patches Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Diclofenac Transdermal Patches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com