

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Synchronous Buck Converter Market to Rise from USD 4,625.5 Million in Base Year 2025 to USD 7,211.62 Million by 2032 at a 6.55% CAGR (2026–2032); Asia Pacific Leads with USD 2,156.73M

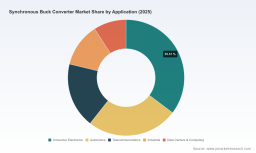
Worldwide Synchronous Buck Converter Market: Strategic Outlook and Tactical Playbook for 2026
Executive summary
The Worldwide Synchronous Buck Converter Market is entering a phase of steady expansion and structural change that will shape corporate decisions in 2026 and beyond. According to PW Consulting’s latest report (base year 2025; historical window 2020–2025; forecast period 2026–2032), the market has grown from roughly 3.38 billion USD (2020) to about 4.63 billion USD in 2025, and is projected to approach 7.21 billion USD by 2032, representing a compounded annual growth rate (CAGR) of approximately 6.55% across the forecast window. The first forecast year, 2026, marks a continuation of growth (with an expected market size near 4.89 billion USD) and sets the stage for inflection points driven by wide-bandgap adoption, modularization in data-center power, and electrification in transportation.
Worldwide Proactive Notification Software Market
Why this matters for 2026 decision-makers
-
Timing matters: 2026 will be the first full planning cycle where executives can act on near-term forecasts that incorporate recent changes in supply-chain dynamics, lead-time normalization, and accelerating GaN/SiC deployments. Early movers who align product roadmaps, procurement, and go‑to‑market (GTM) plans to these shifts stand to capture disproportionate share gains.
Worldwide Healthcare Inventory Management Market -
Margin leverage through technology: Efficiency gains from wide-bandgap semiconductors and integration strategies are creating opportunities to reduce BOM cost, shrink system size, and raise power density. These are not incremental engineering tweaks — they affect product architecture choices, supplier selection, and serviceable addressable markets.
Worldwide AI in IoT Market -
Concentration and partner dynamics: The market exhibits moderate concentration (CR3 ≈ 38.5%, CR5 ≈ 52.1%), which means vendor decisions (both for sourcing and strategic partnerships) will materially influence timelines for qualification, design wins, and pricing dynamics in 2026.
-
Risk vs. reward in verticals: Growth trajectories vary by end-application and operating-voltage strategies. For procurement, R&D and corporate strategy teams, the immediate priority in 2026 is to map internal roadmaps to supplier capabilities and to design flexible architectures that tolerate second-source substitution.
What PW Consulting’s report delivers to executives and practitioners
This release is intentionally operational. Beyond headline forecasts and market sizing, the report provides a toolkit for action that supports board-level and product-team decision-making in 2026:
-
Forward-looking market model: A transparent model that spans 2026–2032 with scenario toggles (base, conservative, and accelerated) to stress-test revenue, unit, and component assumptions against adoption curves for GaN/SiC and multi-phase topologies.
-
Vendor intelligence and sourcing playbook: Detailed vendor profiles, gap analyses, and qualifying checklists tailored to common procurement constraints (thermal envelope, VIN range, EMI, and packaging). Profiles include product positioning, system-level trade-offs, and relative strength mapping for leading suppliers.
-
Technology roadmaps and switch-cost analysis: Comparative analysis of silicon MOSFETs, GaN, and SiC for typical buck topologies, including switching-frequency impacts on passive counts, thermal management trade-offs, and expected efficiency deltas that matter for system-level TCO.
-
Design‑win playbook: Practical guidance on reducing qualification cycles, accelerating reference-design uptake, and leveraging evaluation platforms to compress time‑to‑market for high-power-density solutions.
-
Regulatory and supply-chain risk matrix: Actionable mitigation strategies against export controls, geo-political disruption, and critical‑materials scarcity, aligned to sourcing scenarios and multi-year procurement commitments.
-
M&A and partnership screening: A prioritized list of strategic tuck‑ins and technology partners keyed to capability gaps (GaN integration, driver ICs, packaging, and reference‑design ecosystems) and backed by valuation heuristics informed by market concentration dynamics.
Competitive landscape — who matters and why
The report assesses incumbent suppliers and emergent specialists with a focus on capability, roadmap clarity, and ecosystem leverage. A non‑exhaustive synthesis of core players highlights the tactical choices firms need to make in 2026:
-
Texas Instruments — Broad portfolio depth and reference‑design breadth make TI the default partner for companies prioritizing design velocity and proven integration. Recent launches in high-voltage and GaN‑compatible modules underscore a push towards high power density reference platforms that accelerate OEM adoption.
-
STMicroelectronics — Strength lies in monolithic solutions with automotive-grade qualification. ST’s route to market is particularly compelling for manufacturers needing AEC‑Q100 qualified parts for harsh environments and for EV gate/traction auxiliaries.
-
Infineon Technologies — Infineon’s emphasis on thermal performance and system-level efficiency addresses the twin pressures of higher power density and stringent thermal design in computing and industrial systems.
-
Analog Devices — Multi‑phase controllers and high-density regulator ecosystems align Analog Devices well with data-center and HPC power architects pursuing scalable, synchronized voltage regulation.
-
ON Semiconductor, ROHM, Microchip, Renesas, Diodes Inc. — These vendors fill crucial niches across consumer, embedded, and automotive markets. Notably, recent product introductions (e.g., low-IQ, I²C-enabled buck converters and integrated-FET series) shift the balance toward compact, low‑standby-loss designs favored in portable and edge systems.
-
Efficient Power Conversion (EPC) — As a GaN-focused specialist, EPC’s evaluation boards and reference designs compress prototyping cycles for high‑power USB-PD and other point-of-load use cases; their ecosystem work materially reduces integration risk for OEMs pursuing GaN adoption.
Recent product and ecosystem developments (what to track in 2026)
-
Low‑IQ, smart-interface converters (e.g., I²C-enabled devices) are enabling system-level power management strategies that reduce idle losses — a differentiator for battery-powered and low‑power edge equipment.
-
GaN-based evaluation platforms and high‑VIN/high‑current GaN solutions are shortening design cycles for high power‑density applications such as USB‑PD and point‑of‑load regulation in servers.
-
Reference designs from both incumbents and specialists are becoming strategic assets. Manufacturers that leverage these ecosystems can reduce qualification time and secure early design wins in 2026 product cycles.
Technology and supply-chain dynamics shaping 2026 decisions
Three interlinked dynamics will drive procurement, R&D, and partnership priorities next year:
-
Wide‑bandgap adoption: Measurable efficiency gains (typically low‑single-digit percentage points at system level) and higher switching frequencies are enabling smaller passives and higher power density. Choosing when and where to adopt GaN/SiC will be a central trade‑off between BOM volatility and long‑term system competitiveness.
-
Geopolitical and onshoring pressures: Export controls and reshoring initiatives are affecting supplier maps and contractual terms. Manufacturers with global supply footprints must build contingency into 2026 sourcing arrangements and prioritize dual‑sourcing strategies for key wide‑bandgap components.
-
Normalized lead times: Lead times have improved markedly from their 2022 peak; this easing allows design teams to move from speculative buffer stock to leaner inventory strategies — but only if they can secure predictable supply from qualified second sources.
Scenario implications and tactical recommendations for 2026
-
For product leaders: Adopt a staged GaN integration roadmap tied to specific thermal and efficiency KPIs. Use evaluation‑board proof points to accelerate internal buy‑in and allocate NPI budget to packaging and EMI mitigation early in the design cycle.
-
For procurement and supply-chain heads: Negotiate conditional multi‑year volume commitments with clauses that account for lead‑time variability and export control risks. Design qualification pathways that permit rapid cross‑qualification of functionally equivalent parts from at least two vendors.
-
For corporate strategy and M&A teams: Prioritize tuck‑ins that accelerate GaN/SiC integration, packaging expertise, or reference‑design ecosystems. Pay attention to targets that provide near-term synergies in data‑center and automotive power modules.
-
For investors and market analysts: Monitor adoption velocity in high-growth subsegments where modularization and efficiency offer structural margin expansion opportunities. Leading indicators include reference‑design throughput, design‑win announcements, and ecosystem demos at trade events.
How to use this report — and where to find the hidden detail
PW Consulting’s report is designed as both an executive briefing and an operational playbook. It combines a defensible top‑down market model (with a 6.55% CAGR baseline), scenario analysis, supplier deep dives, and tactical checklists that teams can integrate into 2026 plans within weeks.
Consistent with our “trailer” approach to industry intelligence, this article highlights strategic findings and actionable directions while intentionally withholding the granular segmentation tables and application‑level revenue breakdowns that subscribers use for detailed planning. Those breakdowns — including voltage- and application-level forecasts, region-level scenarios, and supplier-specific revenue shares — are available in the full report and the interactive data workbook on our site.
Next steps
For executives preparing 2026 roadmaps: schedule a briefing with PW Consulting to map the report’s scenarios to your product pipeline and supplier base. For engineering teams: use the report’s vendor‑evaluation templates to accelerate qualification of wide‑bandgap and integrated‑FET solutions. For investors: request the full dataset to model M&A and valuation scenarios that reflect shifting concentration dynamics.
Detailed segmentation, downloadable models, and vendor scorecards are hosted on our report landing page — contact PW Consulting for access and to arrange a tailored workshop that translates insights into prioritized actions for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Synchronous Buck Converter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com