

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Worldwide Infrastructure-as-a-Service Market to Expand at a 21.04% CAGR Through 2032

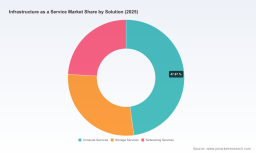
Worldwide Infrastructure as a Service Market — Strategic Outlook for 2026 Decision-Makers
Executive summary: why this matters for 2026
As enterprises finalize 2026 budgets and multi-year cloud roadmaps, Infrastructure as a Service (IaaS) is no longer a peripheral operational choice — it is a core strategic lever. Our new Worldwide IaaS Market report synthesizes market-scale forecasting, vendor-level competitive mapping, regulatory and energy-cost scenario analysis, and pragmatic buyer playbooks to guide decisions that will shape cost structures, time-to-market, and risk exposure through 2032. The purpose of this executive note is to highlight the report’s strategic value for corporate and public-sector leaders while intentionally omitting the granular segment tables and region/application splits that are available in the full report on our site.
Worldwide Golf Software Market
Market trajectory at a glance
The IaaS market has moved from early rapid adoption to mature, hyperscale-driven expansion. Our historical base (2020–2025) shows a compound acceleration from a global market of approximately USD 64.3 billion in 2020 to USD 248.4 billion in 2025. Looking forward, we model continued high growth with a compounded annual growth rate (CAGR) of 21.04% over the 2026–2032 forecast horizon, driving the market to an estimated USD 944.6 billion by 2032. The 2026 inflection point — projected at roughly USD 290.9 billion — is particularly important for procurement cycles and capital planning: organizations that align sourcing, governance, and architecture decisions with this inflection will capture disproportionate operational and competitive advantages.
Worldwide Electronic Trading Platform Market
Key dynamics shaping 2026 decisions
- AI workload specialization and capex-to-opex trade-offs: Demand for AI-optimized infrastructure is a critical growth vector. Independent forecasts project tens of billions of dollars in end-user spending on AI-optimized IaaS in 2026, with more than half supporting inference workloads. Buyers must translate AI performance requirements into specific instance and networking commitments, balancing on-demand elasticity with reserved capacity economics.
- Energy cost volatility and data center economics: Rising electricity demand at hyperscale is changing TCO math. Published projections show U.S. data center electricity consumption expanding substantially by the later part of the decade, and regionally concentrated grid impacts have already added billions to regional electricity costs. These dynamics make energy-aware placement, renewable contracting, and power-efficiency attributes material factors in vendor selection and long-term sourcing agreements.
- Regulatory friction and data residency: The regulatory backdrop has tightened: rules like the EU Data Act and the NIS2 Directive increase contractual obligations, portability expectations, and cybersecurity responsibilities for IaaS providers and their enterprise customers. Data sovereignty laws across jurisdictions continue to affect where and how enterprises host regulated workloads; these constraints should be embedded in 2026 migration and cloud native architectures.
- Concentration and competitive pressure: Market concentration remains meaningful at the global level. The leading cloud vendors collectively account for the majority of enterprise infrastructure spending, prompting both consolidation strategies and differentiated plays from regional or vertical-focused providers. Procurement teams must weigh the benefits of hyperscale economies against concentration risks and vendor-specific interoperability constraints.
Competitive landscape — what buyers need to know
The competitive field remains anchored by a set of global hyperscalers that dominate enterprise spend and innovation, complemented by enterprise-focused, regional, and developer-centric providers. Recent market recognitions and analyses underscore the current pecking order while also signaling where displacement is possible.
Worldwide HTAP-Enabling In-Memory Computing Technologies Market
- Hyperscalers (AWS, Microsoft Azure, Google Cloud): These providers lead on breadth of compute, storage, networking offerings, global footprint, and partner ecosystems. Independent user-feedback-based awards continue to recognize their strengths in performance, scalability, security, and cost optimization. For 2026 sourcing strategies, expect these vendors to compete on differentiated AI infrastructure, specialized networking services, and deeper enterprise systems integration.
- Enterprise-specialists (Oracle, IBM): Firms with legacy enterprise relationships and database-optimized infrastructure emphasize performance for mission-critical workloads and provide options such as bare-metal compute and tightly coupled storage/networking. They are attractive where workload performance and compliance carry a premium.
- Regional and developer-first players (Alibaba Cloud, Tencent Cloud, OVHcloud, DigitalOcean, Rackspace): Regional providers and developer-focused platforms remain important for geography- and developer-centric strategies. They offer differentiated propositions around data sovereignty, cost predictability, and customer support models tailored to SMBs and specific verticals.
Strategic takeaway: shortlists for 2026 should be constructed by overlaying performance, regional compliance posture, energy footprint, and AI roadmap fit — not by price alone. Our report includes vendor scorecards and battlecards that operationalize these decision criteria for RFPs and Proof-of-Concepts.
What the full report delivers (highly pragmatic content)
- Market sizing and forecasts (2020–2032) with scenario variations and sensitivity to energy and AI adoption assumptions.
- Vendor benchmarking: product capability matrices, TCO templates, go-to-market tactics, and negotiated contract levers.
- Regulatory and compliance playbook: clauses and contract language aligned to the EU Data Act, NIS2, and major data residency regimes.
- Energy and sustainability modelling: location-based electricity scenarios, renewable procurement pathways, and PUE-driven cost differentials.
- Buyer-focused tools: RFP templates, migration sequencing roadmaps, scorecards for hybrid and multi-cloud designs, and AI-workload procurement checklists.
- M&A and partnership guidance: criteria for acquiring cloud-enabled startups, assessing managed-service partners, and structuring reseller alliances.
Note: this summary is intentionally a trailer. Detailed segment tables (regional, solution, vertical splits) and complete vendor financials are available only in the full report and are withheld here to preserve the report’s utility as a primary source for decision-makers.
Strategic implications and recommended actions for 2026
- Adopt a workload-centric sourcing strategy: Classify workloads by performance, security, and sovereignty needs. Route AI inference and training to providers or configurations that demonstrably meet latency, networking, and GPU availability requirements — and document outcomes in procurement scorecards.
- Price energy risk into TCO: Run at least two electricity-cost scenarios (baseline and stress) when comparing regional deployments and include renewable energy contracts as negotiable supplier terms. Factor in grid-impact surcharges where applicable.
- Embed regulatory triggers in contracts: Update standard supplier agreements to include clauses for portability, data access rights, and cybersecurity incident reporting consistent with recent EU directives. Make remediation SLAs and audit rights procurement prerequisites for regulated workloads.
- Design for multivendor resiliency: For critical services, prioritize architectures that reduce lock-in through standard APIs, data export paths, and cross-cloud networking strategies. Use managed services only where the operational uplift outweighs portability risk.
- Negotiate outcome-based pricing for AI workloads: Move from raw capacity pricing to outcome or performance-based arrangements (e.g., per-inference or per-training-hour delivered SLAs) to align vendor incentives with business value.
How to convert this intelligence into board-ready actions
- Create a 90-day procurement playbook using our RFP and scorecard templates to reset vendor terms and capture pricing concessions.
- Run a 12–18 month hybrid migration plan that prioritizes cost, regulatory compliance, and AI performance criteria; short-list vendors for PoCs aligned to this plan.
- Task the CISO with a compliance roadmap tied to NIS2 and the EU Data Act milestones; use our audit checklist to validate vendor commitments.
- Align capital planning with forecasted IaaS market growth and energy scenarios — treat cloud spend as a strategic investment subject to internal chargeback and FinOps discipline.
Closing — next step
For executives and procurement leaders preparing 2026 decisions, the full Worldwide IaaS Market report from PW Consulting provides the quantitative foundation, vendor intelligence, and executable playbooks necessary to convert market growth into advantage. We have intentionally kept this briefing high-level and withheld the full regional, solution, and vertical split tables to ensure the report remains the definitive source for transaction-level decisions. Access the full report and supporting tools on the PW Consulting insights page to download detailed tables, vendor scorecards, and TCO models.
For detailed analysis of this topic, please visit the official page: Worldwide Infrastructure as a Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com