

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Enterprise IP Phones Market Poised for 4.82% CAGR Through 2032

Worldwide Enterprise IP Phones Market 2026: Strategic Imperatives for Procurement, Deployment, and Vendor Strategy
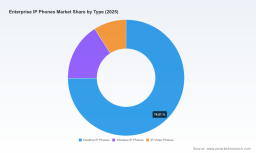
As organizations plan communications investments for 2026, the enterprise IP phones market sits at the intersection of legacy migration, sustainability mandates, and distributed work models. PW Consulting’s newest market research — covering historical performance (2020–2025) and a forward-looking forecast (2026–2032) — projects the global enterprise IP phones market to grow from USD 3,230.2 Million in 2025 to USD 4,491.1 Million by 2032, representing a compound annual growth rate (CAGR) of 4.82% over the forecast horizon. This report is designed to convert market-level insight into immediate, risk-adjusted actions for procurement teams, IT leaders, and corporate strategists in 2026.
Household Copper Wire Market
Why this report matters for 2026 decision-makers
-
Timing investments against infrastructure transitions: Regulatory moves and carrier network upgrades are accelerating decisions. The FCC’s rules accelerating legacy copper retirements (March 2026) mean enterprises must coordinate device refreshes with carrier transition timelines to avoid stranded assets and service disruptions.
Worldwide Excavator Multi-Processors Market -
Managing TCO under constrained energy and construction dynamics: Large-scale data center and network expansion is reshaping where voice platforms run. With significant data center construction and grid-access pressures in North America and beyond, procurement strategies must now embed energy, colocation, and edge costs into device lifecycle models.
Medical Atomization Disinfection Machine Market -
Balancing cloud migration, sovereignty, and on-prem risk: Growing data-sovereignty and privacy mandates are prompting hybrid architecture decisions. The right blend of on-premises survivability and cloud-hosted UC services optimizes compliance and latency without sacrificing cost-efficiency.
What’s in the PW Consulting report (practical, executable content)
-
Market sizing and trend intelligence: A validated historical series (2020–2025) and a granular forecast through 2032 that quantify market expansion drivers and cyclical risks at the global level.
-
Vendor benchmarking framework: A comparative scorecard that assesses product breadth, enterprise feature parity (QoS, PoE profiles, handset security), cloud readiness, and sustainability credentials across established and emerging vendors.
-
Procurement playbook: Ready-to-use RFP language, total cost of ownership (TCO) templates that fold in energy and lifecycle disposal costs, and a supplier negotiation checklist focused on warranty, SLA, and future compatibility clauses.
-
Deployment and migration blueprints: Step-by-step approaches for mass rollouts, staged migrations from TDM to SIP, hybrid on-prem/cloud operational models, and a plug-and-play reference architecture for edge-enabled UC stacks.
-
Risk and resilience checklist: Guidance on supply-chain contingencies, spare-parts strategy, firmware lifecycle management, and incident response planning for large distributed deployments.
-
ROI and use-case models: Sector-tailored (enterprise, SMB, public sector) ROI calculators and scenario analyses to prioritize refresh waves and justify capex versus opex decisions.
Competitive landscape — who matters and why
The market displays moderate concentration, with the top three players capturing a majority share and the top five commanding a dominant position. This concentration dynamic favors established vendors with broad channel ecosystems and enterprise services, but it also creates openings for niche suppliers that excel in interoperability, cost-efficiency, or vertical specialization.
-
Cisco Systems, Inc. — Market leader with enterprise-grade offerings (e.g., AI-enhanced desk phones supporting hybrid deployments). Cisco’s strength lies in deep integration with carrier-class platforms and a broad installed base within large corporations. Its sustainability messaging and PhoneOS support across cloud and on-prem platforms make it a default incumbency choice for many Fortune-level customers.
-
Yealink — Aggressive portfolio refreshes targeting scale and feature parity. Yealink’s extended SIP/VoIP lineup and integration with leading collaboration platforms make it a go-to for organizations seeking a balance of functionality and value.
-
HP Poly — Differentiates through audio innovation and noise-cancellation technologies, with a clear focus on contact centers and dense office environments where audio quality directly affects productivity.
-
Grandstream — Plays to volume deployment and cost-efficiency, with ongoing firmware and energy-optimization efforts that reduce operational consumption — an increasingly important procurement criterion.
-
Mitel, Avaya, Alcatel‑Lucent Enterprise, Snom, Fanvil — Each brings specific strengths: hybrid deployment support, security-focused interoperability, high-audio-fidelity for regulated industries, or cost-sensitive device portfolios for SMBs. These suppliers often serve as important alternatives for verticalized procurement strategies.
Recent vendor moves that reshape procurement calculus
-
New product introductions with embedded AI audio and hot-desking features indicate a rapid feature convergence between high-end desk phones and UC clients. Expect buyers to demand firmware roadmaps and upgrade guarantees for AI-enabled capabilities introduced in 2025–2026.
-
Energy-saving firmware updates and long-range Wi‑Fi/DECT options have shifted the selection criteria from pure device cost to lifecycle energy consumption and wireless enablement. Vendors posting demonstrable energy reductions will gain procurement preference where sustainability and operating expense reductions are executive priorities.
-
Catalog refreshes focused on platform interoperability (Teams/Zoom and SIP) emphasize the need for interoperability testing and certification language in procurement contracts to avoid integration latency or administrative overhead.
Regulatory and infrastructure developments shaping strategy
-
Carrier network modernization: Accelerated retirement of copper networks is compressing migration timelines. Enterprises must map device refresh schedules to carrier migration plans to minimize service disruption and avoid double-spend on transitional infrastructure.
-
Energy and grid constraints: Large-scale data center construction and related grid demands have implications for hosting and edge models. Organizations should include energy cost projections and grid-availability risk in decisions about centralized versus edge-hosted voice platforms.
-
Geo-economic and trade shifts: Tariffs, equipment restrictions, and sovereignty requirements are materially increasing procurement complexity. Strategic sourcing now requires multi-jurisdictional compliance checks, alternative supplier qualification, and contingency inventory planning.
-
Data sovereignty: Continued pressure for localized compute and storage is pushing more UC workloads closer to the edge. This affects handset selection (local survivability features) and service architecture (local SBCs, edge compute nodes).
Actionable recommendations for 2026
-
Adopt a phased, risk-weighted refresh approach. Prioritize endpoints in regulatory-exposed sites and high-utilization contact centers for early replacement; defer low-utilization rollouts to align with carrier migration windows.
-
Shift procurement evaluation from capex-only to lifecycle cost metrics. Tender responses should be scored on energy consumption profiles, firmware upgrade policies, and end-of-life recycling/sustainability commitments.
-
Negotiate portability and interoperability clauses. Require vendors to commit to protocol openness, certified integrations with your UC platforms, and extended security patch support to minimize vendor lock-in risks.
-
Embed contingency inventory and retrofit plans into contracts to account for supply-chain variability and geopolitical risk. Specify accelerated provisioning SLAs for locations deemed mission-critical.
-
Incorporate edge-readiness into architecture decisions. Where data sovereignty or latency are binding constraints, design for SBCs and survivable gateways at the edge and procure devices with proven local survivability modes.
-
Leverage vendor diversity strategically. Where concentration risk is acceptable, consolidate for volume and managed services; where sovereignty or vertical specialization matters, segment purchasing to include niche suppliers.
Where the full report adds value (and why this summary is purposefully high-level)
This briefing provides the strategic contours and operational imperatives you need to set 2026 priorities. The full PW Consulting Worldwide Enterprise IP Phones Market report, however, contains the granular decision-enabling components we intentionally omit here: the detailed regional and application-level splits, model-level revenue trajectories, per-vendor feature scoring matrices, and downloadable RFP/TCO templates. Those items are the outcome of primary vendor interviews, procurement-scenario simulations, and rigorous sensitivity testing — and they are provided in the full report for clients making contractual or capital-allocation commitments.
Final word — positioning for resilience and value in 2026
For enterprise leaders, 2026 is a year to convert macro pressure into tactical advantage. The market’s steady growth trajectory underscores persistent demand for purpose-built endpoints, but success will hinge on how organizations integrate regulatory watchfulness, energy and data-sovereignty constraints, and vendor resilience into their procurement and deployment playbooks. PW Consulting’s report is designed to be both a map and a manual: mapping the market’s direction and providing the operational instruments to execute with confidence.
For access to the full dataset, vendor matrices, and procurement toolkits, visit the PW Consulting report center or contact our advisory team to schedule a briefing tailored to your organization’s objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Enterprise IP Phones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com