

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Worldwide Naval Vessel MRO Market to Reach USD 89,260 Million by 2032

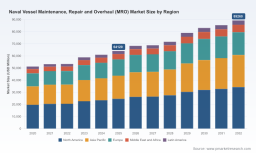
Worldwide Naval Vessel Maintenance, Repair and Overhaul (MRO) Market: Strategic Imperatives for 2026 Decisions
PW Consulting’s newest Worldwide Naval Vessel MRO Market study synthesizes five years of historical performance and a forward-looking forecast to 2032, delivering a rigorous, decision-grade resource for defense planners, shipyard executives, OEMs, and private equity investors preparing for 2026. The market reached approximately USD 64,120 Million in 2025 and is projected to expand to roughly USD 68,315 Million in 2026, with a modeled trajectory that reaches near USD 89,260 Million by 2032 — a 4.84% compound annual growth rate across the 2026–2032 forecast window. This release explains why 2026 is a turning point for strategic investments and operational choices in naval sustainment, and which levers will determine who captures the long-term value.
Worldwide Industrial Arc Furnaces Market
Why 2026 is a Pivotal Year
-
Geopolitics and the shifting maintenance footprint: Recent awards and partnerships, particularly in the Indo‑Pacific, have accelerated allied MRO capacity outside traditional Western hubs. Several South Korean yards have secured high-profile U.S. Navy logistics vessel contracts, underscoring a more distributed approach to fleet sustainment that will affect basing, supply chains, and contingency planning in 2026.
Turntable Slip Rings Market -
Regulatory guardrails that reshape choices: Statutory constraints such as U.S. domestic repair requirements for homeported Navy vessels continue to create a bifurcated market for domestic vs. allied MRO activity. At the same time, defense budget allocation patterns indicate a heavy emphasis on propulsion and dry‑dock workstreams — engine and dry‑dock activities now exceed 55% of reported maintenance spending in several analyses — focusing attention on specialized capability nodes.
Worldwide Impairment Goggles Market -
Cost drivers and operational risk: Raw material and labor dynamics are increasing unit costs for shipyards and sustainment providers. For example, naval‑grade steel prices in Northeast Asia rose to roughly USD 1.81/kg in early 2026, while U.S. shipyard labor income levels remain high and workforce shortages persist, intensifying upward pressure on MRO margins and creating a premium for productivity improvements.
What the Report Delivers — Practical, Executable Intelligence (keeps the granular splits secure)
-
Robust market sizing and trend analysis: A verified historical dataset covering 2020–2025 and a transparent forecasting engine for 2026–2032 that isolates demand drivers by vessel lifecycle stage, service type, and macroeconomic scenarios. The headline market totals and CAGR are published to guide portfolio sizing; granular segment tables and regional detail are included in the full report.
-
Actionable decision frameworks: Bid/no‑bid thresholds for large‑scale depot contracts, investment case templates for greenfield/expansion capex, and contract structuring checklists to minimize revenue volatility from lifecycle peaks.
-
Supply‑chain stress tests and scenario planning: Quantified scenarios modeling commodity spikes, labor constraints, and base‑relocation events, each mapped to P&L impacts and capex timing recommendations.
-
Competitive playbooks and M&A scouting: Empirically grounded profiles of incumbent and emerging MRO players, capability gap maps, and an M&A prioritization matrix that balances strategic fit, regulatory exposure, and integration risk.
-
Operational modernization roadmaps: Step‑by‑step guidance on digital MRO adoption, remote diagnostics, predictive maintenance deployment, and workforce reskilling to lift throughput while protecting quality and compliance.
Competitive Landscape — Who Matters and Why
The global MRO ecosystem remains concentrated around diversified prime integrators and specialty engineering houses. Market concentration metrics show that the top three players hold a meaningful share of industry revenues and that the top five firms capture a clear majority of identifiable market turnover — a structure that favors scale, integrated logistics, and strategic relationships with navies and defense ministries.
-
Huntington Ingalls Industries (Newport News, VA): A dominant US‑flag platform for high‑complexity sustainment — notably nuclear carrier refueling and submarine overhauls — HII’s recent supply‑chain and capacity expansions are explicitly geared to cement lead positions in long‑cycle naval programmes.
-
General Dynamics (Reston, VA): Through its NASSCO and Electric Boat units, General Dynamics provides a geographically diversified sustainment footprint across auxiliary and submarine fleets. Its portfolio emphasizes depot capabilities and multi‑port support lanes.
-
BAE Systems and Babcock (UK): These firms combine dry‑dock heft with systems‑level upgrade and combat‑system sustainment, serving both domestic fleets and export customers via through‑life support contracts.
-
Naval Group, Fincantieri, Navantia, and ThyssenKrupp: European primes that integrate design, newbuild, and refit expertise — their through‑life support offers remain significant for allied and export customers seeking one‑stop sustainment partners.
-
OEM and systems specialists (Rolls‑Royce, Thales, Kongsberg, Lockheed Martin): These companies increasingly capture higher‑margin MRO work around propulsion, sensors, combat systems, and prime electronics through long‑term support contracts and spare‑parts agreements.
-
Regional and niche players (Austal, HD Hyundai, Larsen & Toubro, Damen): These yards compete on rapid turnaround, specialized hull materials (e.g., aluminium), and regional proximity — factors that matter for littoral fleets and logistics ship sustainment.
Recent developments underscore competitive dynamics that will shape 2026 strategic choices: HD Hyundai’s contract wins for logistics‑class vessel overhauls and the entry of Korean yards into U.S. Navy logistics work signal a more competitive global market for auxiliary sustainment; Huntington Ingalls’ acquisitions to strengthen submarine MRO supply chains indicate continued consolidation at the high‑complexity end of the market.
Operational Levers for 2026 Decision‑Making
-
Prioritize capability adjacency over scale alone: Investment in propulsion overhaul capabilities, dry‑dock availability, and nuclear/complex systems know‑how yields premium revenue access. For firms without those capabilities, partnerships or minority stakes in specialists provide faster access than full greenfield builds.
-
Design contracts around predictability: Shift fixed‑price elements to indexed or milestone‑based structures that account for material price swings and labor availability. Hedging strategies for naval‑grade steel and long‑lead components materially reduce margin erosion.
-
Localize selectively to manage regulatory exposure: Understand where domestic repair statutes or basing patterns create protected workstreams versus where allied ports are viable for auxiliary classes. For U.S. Navy homeported assets, domestic compliance remains non‑negotiable; allied hubs can serve logistics and ancillary flows.
-
Invest in digital MRO and workforce productivity: With labor representing a substantial share of ship costs and with skills shortages persistent, adoption of predictive maintenance, augmented reality for diagnostics, and modular tasking models delivers outsized returns on throughput.
-
Adopt a portfolio approach to risk: Balance legacy, high‑complexity work (steady, long‑duration margins) with faster‑turnaround, lower‑duration contracts that smooth revenue and utilize spare capacity between major availabilities.
Implications for Capital Allocation and M&A in 2026
Capital discipline will separate winners. The market’s structural growth (mid‑single digit CAGR across the forecast window) justifies selective capacity expansion, but investments must be prioritized where barriers to entry are highest — nuclear/complex propulsion, integrated combat systems MRO, and strategic dry‑dock assets. M&A targets that offer regulatory advantage, unique technical capabilities, or a foothold in allied basing networks should command premium valuations. Our report provides a prioritized watch list and valuation bands calibrated to 2026 contracting cycles and policy timelines.
How PW Consulting Can Help
-
Customized scenario modeling calibrated to your asset base and contract profile (including commodity and labor stress tests).
-
Bid/no‑bid decision support and contract optimization templates tailored to naval sustainment procurement rules and local content constraints.
-
M&A diligence playbooks and integration roadmaps for acquiring technical specialists or expanding regional repair networks.
Next Steps — Secure the Full Intelligence Package
This bulletin outlines the strategic contours and executive implications of our full Worldwide Naval Vessel MRO Market study. The comprehensive report contains the granular segmentation tables, regional breakdowns, and supplier‑level financial models that underpin the actionable recommendations summarized here. For a copy of the complete report, the M&A watch list, and a tailored briefing on what the 2026 contracting environment means for your organization, please visit PW Consulting’s report page or contact our naval sustainment practice. The full dataset and scenario models are available to subscribers and clients who require decision‑grade detail.
For detailed analysis of this topic, please visit the official page: Worldwide Naval Vessel Maintenance, Repair and Overhaul (MRO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com