

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide In‑Car Infotainment Market Set to Expand at a 10.21% CAGR Through 2032, New Report Finds

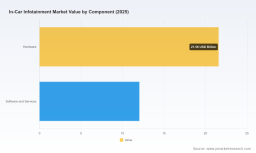
Worldwide In‑Car Infotainment Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
PW Consulting’s new market study on the Worldwide In‑Car Infotainment Market sets the strategic frame for decisions that will define supplier positions, OEM roadmaps, and investor value creation through the rest of this decade. The in‑car infotainment market has accelerated from an early‑decade base to exceed USD 33.6 billion in our 2025 base year and is projected to roughly double by the end of the 2026–2032 forecast window, tracking a compound annual growth rate of approximately 10.21%. That momentum — underpinned by rapid software migration, 5G-enabled experiences, and growing services monetization — creates both urgent opportunities and material risks for market participants planning 2026 investments.
Worldwide Subscription Analytics Software Market
Why 2026 is the strategic inflection point
-
Technology convergence is changing the value equation. The shift to software‑defined vehicle (SDV) architectures, combined with the mainstreaming of Android Automotive and partnerships between chipset and cloud providers, is compressing time‑to‑market for advanced cockpit capabilities. Recent industry moves — including expanded Qualcomm–Google collaboration and OEM supply agreements announced in early 2026 — make platform selection and long‑term supplier commitments high‑stakes decisions this year.
Worldwide 5-Fluorouracil Market -
Regulatory and privacy dynamics are tightening monetization levers. In 2026, new enforcement actions and state‑level privacy rules are reshaping how vehicle data can be collected, shared, and commercialized. Suppliers and OEMs can no longer assume consumer data will remain a free, unrestricted source of value; consent architectures and transparent data governance must be operationalized before new subscription models are launched.
Worldwide Gas Gravitometers Market -
Cost and supply considerations are crystallizing hardware‑software trade‑offs. The industry is balancing the incremental value of 5G and AI features against module, TCU and roadside infrastructure costs. Hardware choices made in 2026 will lock in cost bases and upgrade paths for multiple model cycles — influencing margins and upgrade economics through 2032.
Market dynamics shaping strategic choices
-
Software first, hardware second: Infotainment is migrating from a hardware‑driven product to a software and services platform. Feature differentiation increasingly comes from user experience, AI services, cloud connectivity and OTA update capabilities rather than raw display or audio specs. This accelerates the importance of middleware, lifecycle support, and recurring revenue models.
-
Connectivity and edge compute: 5G and edge services enable new media, safety, and location experiences — but they also introduce new distribution costs. The emergence of retrofitable AI extension platforms and long‑term chipset supply agreements reported in early 2026 demonstrates how the ecosystem is moving to decouple new capabilities from wholesale hardware redesigns.
-
Regulatory and privacy pressure: In 2026 regulators have intensified scrutiny of vehicle data use. Enforcement actions and new consent requirements mean commercial pilots and subscription rollouts must embed privacy‑by‑design and auditable consent flows. Failure to do so risks not just fines, but loss of consumer trust and blocked business models.
-
Consolidation and collaboration: The competitive landscape shows both vertical integration by large Tier‑1s and strategic alliances among chipset vendors, cloud providers and OEMs. This hybrid model strengthens incumbents with platform capabilities while creating white‑space for specialized suppliers that can demonstrate unique services or integration speed.
Competitive landscape — who matters and why
The market is populated by a mix of global Tier‑1s, OEM captive suppliers, consumer electronics entrants, and specialized aftermarket players. Critical firms to watch include established infotainment and cockpit platform providers, audio and head‑unit specialists, and those advancing SDV enablement:
-
Harman International (Samsung) — premium connected infotainment systems, digital cockpit platforms and Android Automotive solutions embedded in many global OEM programs.
-
Robert Bosch GmbH — integrated infotainment and AI cockpit solutions with a growing focus on retrofitable software extensions demonstrated at CES 2026.
-
Continental AG — smart vehicle architectures and biometric features that bridge infotainment with ADAS and domain control strategies.
-
Denso Corporation — deep OEM relationships, telematics expertise, and user‑experience focused solutions aligned with major manufacturing programs.
-
Panasonic (Automotive Systems), Pioneer, Visteon, Aptiv, Alpine/ALPS ALPINE, JVCKENWOOD (Clarion), LG Vehicle Component Solutions, Mitsubishi Electric, Garmin, Hyundai Mobis and FORVIA (Faurecia) — each plays distinct roles across head units, displays, HMI, platform software and integration services.
These companies are simultaneously competitors and partners. Strategic alliances — for example, OEMs locking in chipset roadmaps with large silicon vendors or partnering with cloud/OS providers — will determine who captures platform economics versus who earns integration premiums.
Recent developments with immediate strategic implications
-
Bosch’s January 2026 announcement of an AI extension platform illustrates a practical pathway to retrofit AI capabilities into existing cockpits without full hardware replacement — an attractive option for OEMs seeking feature acceleration while deferring capital‑intensive redesigns.
-
Qualcomm’s expanded collaboration with Google and the Volkswagen Group’s supply intent for Snapdragon Digital Chassis solutions signal that long‑term chipset‑to‑software alliances are central to SDV success. Firms must evaluate supplier roadmaps, update cadences and service layers when negotiating 2026 supply contracts.
-
Toyota’s integration of carrier 5G connectivity in refreshed models shows how OEMs are embedding operator relationships into product offers, a trend that will shape financing and subscription bundles.
-
Regulatory moves — including recent FTC action and accelerated state privacy rules — require companies to reconcile product roadmaps with consent mechanics, data localization and audit trails; these requirements influence not just compliance costs but the feasibility of certain data‑driven services.
What the PW Consulting report delivers (practical, decision‑ready contents)
-
Forward‑looking market model with annualized revenue forecasts across 2026–2032, stress‑test scenarios for alternate technology and regulatory outcomes, and sensitivity analyses tied to hardware cost trajectories and subscription uptake.
-
Strategic supplier heatmaps and capability matrices that map technology ownership, service readiness, and integration risk — enabling procurement teams to prioritize partners by program risk and margin impact.
-
Commercial playbooks for monetization, including subscription rollout sequencing, bundling strategies with connectivity providers, and privacy‑aligned consent frameworks that meet emergent regulatory expectations.
-
Technology roadmaps and scenario planning for 5G, edge compute, AI‑enhanced UX, and OTA architectures — calibrated with component cost inputs and infrastructure considerations to quantify TCO and upgrade economics.
-
M&A and partnership target shortlists based on capability gaps, go‑to‑market acceleration potential, and platform fit — accompanied by valuation sensitivities and integration playbooks.
Actionable recommendations for leaders planning 2026 investments
-
Prioritize platform modularity and OTA lifecycle management. Whether you are an OEM or Tier‑1 integrator, designing for continuous software delivery and decoupled hardware refresh cycles preserves optionality and reduces stranded investment risk.
-
Embed privacy and consent into product architecture today. New enforcement trends mean that subscription and data monetization pilots must include auditable consent flows and data minimization by default — retrofitting these mechanisms later is costly and brand‑damaging.
-
Structure supplier agreements for shared roadmap visibility. Long‑term chipset and cloud relationships are now strategic assets; contracts should include update cadences, security SLAs and co‑development clauses to avoid platform lock‑in or capability gaps.
-
Run parallel hardware‑light and hardware‑heavy scenarios. Bosch’s AI extension approach and similar retrofit strategies offer a lower‑capex path to deliver advanced features; concurrently maintain options for integrated hardware redesigns where OEM differentiation justifies the spend.
-
Quantify infrastructure and lifecycle costs for connectivity. Decision models must include 5G module pricing, TCU economics and potential roadside unit investments when evaluating total cost of ownership and service margins.
How PW Consulting’s insights convert to board‑room decisions
This report is designed to convert market intelligence into executable plans: it aligns financial forecasts with procurement choices, maps competitive moves to partnership opportunities, and ties regulatory scenarios to product and legal risk. For boards and C‑suites preparing budgets and strategic plans in 2026, our analysis clarifies where to allocate incremental capital, which partnerships accelerate time‑to‑market, and how to defensibly price subscription services within tightening privacy regimes.
Next steps
The preview above highlights high‑level conclusions and actionable recommendations drawn from PW Consulting’s full Worldwide In‑Car Infotainment Market report. To preserve the utility of our proprietary segment models and supplier scorecards, we intentionally limit publication of granular splits in this release. The full report includes detailed regional and component-level modeling, supplier concentration analysis, and playbooks tailored to OEMs, Tier‑1s, aftermarket players and financial sponsors.
For access to the comprehensive dataset, scenario models, and executive briefing packages that support 2026 decision cycles, please visit PW Consulting’s report page or contact our research team to schedule a tailored executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide In-Car Infotainment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com