

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: IT & Electronics
PW Consulting: IC Substrate Market Hits $10B in 2025, Projected 6.63% CAGR Through 2032
By pmarketresearch, 2026-09-15
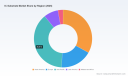
Strategic Horizons in the IC Substrate Market: A 2026 Executive Brief
The integrated circuit (IC) substrate market stands at a critical inflection point as 2026 unfolds. Driven by the insatiable demand for artificial intelligence (AI) computational power, the proliferation of high-performance computing (HPC), and the electrification of automotive platforms, the industry is experiencing a structural shift in both volume and value. For executive leadership and strategic planners, understanding the trajectory of this market is not merely an academic exercise but a prerequisite for capital allocation, supply chain resilience, and long-term competitive positioning.
PW Consulting's latest market research report, "IC-Substrate Market 2026-2032," offers a comprehensive analytical framework designed to navigate this complex landscape. This article serves as a strategic preview of the report's findings, highlighting the macro-economic trends, competitive dynamics, and operational imperatives that will define the industry over the next seven years. While we outline the broad strokes of the market evolution here, the full intelligence required for precise decision-making lies within the detailed data tables, segment-specific forecasts, and proprietary competitive matrices available in the complete study.
Market Trajectory and Growth Dynamics
The historical resilience of the IC substrate sector provides a strong foundation for future growth projections. Drawing on historical data spanning 2020 through 2025, the market has demonstrated a consistent upward trajectory despite global supply chain disruptions and geopolitical headwinds. The consolidated revenue figures for the recent past reflect steady expansion, culminating in a base year valuation for 2025 that underscores the sector's maturity and integral role in the electronics ecosystem.
Looking forward, the forecast period from 2026 to 2032 indicates a sustained growth momentum. The analysis projects a compound annual growth rate (CAGR) of 6.63 percent USD over this horizon. This growth is not uniform; it is heavily skewed by technological advancements and specific application drivers. The market size is expected to expand significantly by the end of the forecast period, reaching new valuation highs in 2032. Such growth rates suggest that IC substrates will remain a critical bottleneck and opportunity zone for downstream electronics manufacturers.
Technology Segments and Application Drivers
The market is segmented by technology type and end-use application, each presenting distinct risk and reward profiles. In terms of substrate types, the landscape is dominated by advanced packaging solutions required for high-density interconnects. Key categories include Flip-Chip Ball Grid Array (FC-BGA), Flip-Chip Chip Scale Package (FC-CSP), and other specialized substrate types. The shift toward higher performance computing necessitates substrates that can handle greater power densities and signal speeds, favoring advanced variants within these categories.
On the application side, the demand signal is led by the Mobile and Consumer electronics sector, which continues to drive volume. However, the quality and value growth is increasingly derived from the Automotive and Transportation sector, as well as the IT and Telecom industry. The emergence of AI servers, autonomous driving systems, and advanced telecommunications infrastructure is reshaping the demand mix, placing premium substrates at the center of supply chain strategy. Our report dissects these segments to reveal where margin expansion is most viable, though specific volume splits and regional contributions are detailed exclusively in the full dataset to maintain competitive confidentiality.
Competitive Landscape and Strategic Consolidation
The IC substrate market is characterized by a moderate to high level of concentration, with top players commanding a significant share of global revenue. Our analysis indicates a CR3 of approximately 54 percent and a CR5 of 60 percent, highlighting the dominance of entrenched incumbents who possess the technical capability and capital depth to invest in next-generation manufacturing. This concentration suggests that barriers to entry remain high, particularly for technologies involving Advanced Build-up Film (ABF) and glass-core substrates.
Several key companies define the current competitive arena. Firms such as Ibiden Co., Ltd., Unimicron Technology Corp., and AT&S Austria Technologie & Systemtechnik AG are at the forefront of innovation, particularly in high-performance applications. These players are not merely competing on price but are engaging in a race for technological superiority and capacity leadership. Regional players in Japan, Taiwan, South Korea, and Austria are expanding their footprints, often supported by government incentives aimed at securing semiconductor supply chains.
Samsung Electro-Mechanics and LG Innotek represent significant competitive forces from South Korea, leveraging vertical integration and strong domestic demand. Meanwhile, companies like Kinsus Interconnect Technology Corp., Shinko Electric Industries Co., Ltd., and Nan Ya PCB Corporation are positioning themselves to capture specific niches within the AI and server packaging value chain. Kyocera Corporation also remains a notable entity, focusing on specialized laminate technologies. The interplay between these entities involves capacity expansions, pricing strategies, and technological partnerships that our report analyzes in depth.
Operational Dynamics: Capacity, Materials, and Regulation
The operational environment for IC substrate manufacturers in 2026 is defined by a tension between surging demand and supply chain constraints. A primary theme in our research is the massive capital expenditure programs undertaken by leading firms. For instance, recent announcements highlight capital investments exceeding hundreds of billions of yen and trillion-won ranges dedicated to expanding high-performance IC package substrate capacity. These investments are targeted specifically at plants capable of serving AI server demands, with mass production timelines ramping up from fiscal 2027 onwards.
Technology advancement is another critical vector. The industry is moving beyond traditional organic substrates toward glass-core and multifunctional core technologies. Recent developments indicate that some leaders have advanced glass-core substrate technology from R&D to industrial deployment, targeting AI, HPC, and even photonics applications. This technological leap is essential for overcoming signal loss and thermal challenges in next-generation packages.
However, capacity expansion is complicated by raw material volatilities. The market faces persistent shortages in critical inputs such as fiberglass and base resins. Supply chain intelligence indicates that key material suppliers have adjusted pricing significantly, with some substrate film prices increasing by over 30 percent due to base resin supply constraints. This inflationary pressure on raw materials is forcing manufacturers to reconsider pricing strategies. In response, leading substrate providers have begun raising prices for premium ABF substrates to offset costs and manage capacity constraints, signaling a shift in the cost structure for downstream customers.
Regulatory support remains a potent accelerant for market growth in key regions. Government initiatives aimed at bolstering domestic semiconductor manufacturing are providing substantial financial backing. For example, funding mechanisms totaling hundreds of millions of USD have enabled specific capacity projects in North America, targeting significant panel production volumes by late 2027. Similarly, European initiatives have awarded substantial grants for plant expansions in Austria, adding tens of thousands of FC-BGA panels to monthly production capacity starting in 2027. These geopolitical interventions are reshaping the global supply map, reducing reliance on single-region sourcing and encouraging localized production hubs.
Strategic Imperatives for 2026 Decision Makers
For industry participants, the insights contained in this study translate into several actionable strategic imperatives. First, supply chain diversification is no longer optional. With material shortages and geopolitical risks influencing the flow of critical substrates, organizations must develop multi-source strategies. Second, technology roadmapping must align with the shift toward glass-core and high-density interconnect solutions to avoid obsolescence in AI and HPC segments.
Third, capacity planning requires a nuanced understanding of lead times and allocation risks. As key players prioritize high-margin AI server contracts, availability for other segments may become constrained, necessitating earlier locking-in of volumes. Finally, pricing negotiations must account for the structural increase in raw material costs and the premium nature of advanced substrate technologies.
The detailed segmentation data, company profiles, and granular forecast models within our full report provide the specific intelligence needed to validate these strategies. Access to the complete analysis allows clients to benchmark their internal projections against market-wide data, identify underserved niches, and anticipate the moves of key competitors with greater precision.
Conclusion
The IC-Substrate Market from 2026 to 2032 presents a landscape of robust growth tempered by complex operational challenges. The convergence of AI demand, technological innovation in substrate materials, and strategic government intervention creates a dynamic environment where informed decision-making is a key differentiator. The macro trends point to a market expanding significantly in value, driven by high-performance applications that demand superior interconnect solutions.
IC Substrate Market
PW Consulting's comprehensive study offers the depth and breadth required to navigate this terrain. By leveraging the detailed forecasts, competitive profiles, and risk assessments outlined in the full report, stakeholders can secure a decisive advantage in procurement, investment, and strategic planning. We invite industry leaders to access the complete research document to unlock the full spectrum of data and insights necessary for thriving in this evolving market.
IC-Substrate Market
For detailed analysis of this topic, please visit the official page: IC-Substrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: GaN on Diamond Market Hits $33M in 2025, Projects 17.0% CAGR to 2032
By pmarketresearch, 2026-09-15
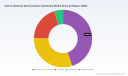
Precision Cooling, Strategic Cooling: Why GaN on Diamond Semiconductor Substrates Demand Your 2026 Attention
The Silent Inflection Point in High-Power Electronics
The semiconductor industry has long treated thermal management as a constraint to be engineered around, but a structural shift is underway. Gallium nitride on diamond substrates represent a material alliance that redefines what is physically possible in high-power, high-frequency electronics. At the device level, the underlying semiconductor continues to deliver superior electron mobility and switching performance, while the diamond substrate introduces thermal conductivity that conventional silicon carbide or aluminum nitride platforms simply cannot match. This convergence is no longer confined to laboratory demonstrations or defense prototypes. It is entering a phase where capital allocation, supply chain design, and product roadmaps must account for it as a mainstream strategic variable. Our latest market research on GaN on Diamond Semiconductor Substrates is built for decision makers who need to understand not just where the market is heading, but what it means for sourcing strategies, competitive positioning, and technology bets in 2026 and beyond.
The strategic importance of this substrate category lies in its ability to unlock higher power density without sacrificing reliability. Systems that once required aggressive external cooling, large thermal spreaders, or operational compromises are now being re-evaluated under a new thermal envelope. Radar architectures, satellite communications payloads, and broadband RF amplifiers are among the first to benefit, but the ripple effects extend into any design where heat flux has become the limiting factor. As device architects push toward higher frequency, smaller form factors, and more demanding duty cycles, the choice of substrate is no longer a cost detail. It is a performance multiplier that can determine whether a product vision is achievable at all.
This analysis is intended to give executives, product leaders, and technology strategists a grounded view of that inflection point. It synthesizes historical trajectory, forward-looking growth dynamics, competitive behavior, and the operational friction that shapes commercialization. The goal is to provide enough analytical rigor to support serious planning, while deliberately leaving the granular breakdowns for the full report, where the type-specific, application-specific, and regional intelligence is structured for direct use in investment cases, sourcing decisions, and go-to-market timing.
From Niche Capability to Commercial Infrastructure
The market for GaN on Diamond Semiconductor Substrates has moved through a recognizable evolution over the past several years. Early activity was defined by material science validation, limited wafer availability, and a narrow set of high-value applications willing to absorb premium costs. That period established proof of concept and created the first credible supply relationships. What followed has been a transition from experimental adoption to more deliberate commercial scaling, where demand signals are increasingly tied to real product requirements rather than research curiosity alone.
Over the historical window from 2020 through 2025, revenue growth has reflected this maturation pattern, with the market expanding from a relatively modest base in 2020 to a materially larger footprint by the end of the current base year. That progression is not merely a story of rising unit demand; it signals growing confidence among downstream buyers and a broader acceptance that diamond-enabled thermal performance can justify the economics in the right contexts. The trajectory into the forecast period through 2032 suggests that this is not a short-lived hype cycle. Instead, the market appears positioned to sustain a compound annual growth rate of approximately 17.0 percent, implying a path toward nearly one hundred million USD in revenue by the close of the forecast window.
For strategists, the most important implication is not the headline number itself, but the shape of the growth curve. A sustained double-digit CAGR across a multi-year horizon typically indicates that adoption is being pulled by application requirements and that the enabling ecosystem—material supply, device integration, and system-level validation—is expanding in parallel. This is the kind of market dynamic where timing matters. Companies that wait until the category is fully commoditized may find themselves competing in a crowded late-entry environment. Companies that engage too early, without a clear value proposition or supply assurance, risk absorbing costs that the broader market is not yet prepared to support. The current window offers a distinct advantage to those who can align technical readiness with disciplined commercial logic.
The Commercial Core: Where Value Is Actually Created
A market of this nature only becomes strategically useful when it is understood at the level of type, application, and regional behavior. That is where the broad narrative separates from the decisions that actually move budgets and engineering plans. In the full study, these dimensions are developed in detail so that leaders can distinguish between segments that are genuinely scaling and those that remain aspirational or constrained. For now, the executive-level picture is clear enough to frame the opportunity without giving away the operational architecture that makes the research actionable.
On the material side, the substrate landscape is anchored by a meaningful divide between single crystal diamond and polycrystalline diamond. That distinction is not a minor specification detail; it shapes thermal performance, device integration complexity, yield economics, and the set of applications where the solution is genuinely defensible. Different end use cases tolerate different trade-offs between performance and cost, and knowing which substrate form factor aligns with which market need is essential for pricing strategy, roadmap planning, and investor storytelling. The broader market structure reflects a clear performance-intensive core, with the dominant material category capturing a substantial share of current revenue while the secondary category serves more cost-sensitive or application-flexible roles.
On the application side, the demand engine is concentrated in segments where power density, thermal resistance, and frequency performance are non-negotiable. RF power amplifiers stand out as a leading driver, reflecting the ongoing push for higher output, better efficiency, and more compact designs in advanced communications and electronic warfare systems. Microwave and millimetre wave circuits represent another substantial pillar, given their importance to high-bandwidth links, sensing systems, and next-generation communication architectures. Radar sensing equipment adds a further layer of demand tied to defense, aerospace, and industrial detection requirements, while additional emerging uses continue to broaden the addressable space. In the complete analysis, these application dynamics are unpacked so that buyers can see not just where revenue originates today, but which application clusters are most likely to become the primary growth engines over the forecast horizon.
Regionally, the market is far from uniform. Some geographies command disproportionate share based on underlying industry structure, defense procurement patterns, satellite infrastructure development, and the presence of advanced semiconductor manufacturing and integration ecosystems. Other regions reflect smaller but strategically meaningful entry points, where demand may be less mature today but where supply chain localization, government support, or regional technology initiatives could reshape participation over time. The complete study preserves these regional distinctions in a form that supports scenario planning, supplier evaluation, and footprint decisions without reducing the market to a simplistic one-size-fits-all narrative.
Competitive Architecture: Who Shapes the Market and How
The GaN on Diamond Semiconductor Substrates market is not a fragmented commodity landscape. It is a space where a relatively concentrated group of specialized players exerts significant influence over technology direction, supply availability, and customer confidence. The overall market concentration reflects that reality, with a modest group of leading participants commanding a meaningful share of activity. That concentration matters because it signals where buyer leverage sits, where supplier dependency may emerge, and where partnerships or vertical integration strategies could alter bargaining power over the next several years.
Element Six continues to occupy a foundational role in synthetic diamond substrates, particularly where extreme thermal performance is required for RF, power, and defense electronics. Its technology relevance extends beyond material supply, touching the credibility and performance baseline of the entire category. Akash Systems has been advancing GaN-on-diamond in the context of satellite communications, where thermal and efficiency constraints are especially acute and where the value of effective cooling can directly influence payload architecture. Qorvo, Inc. is positioned where GaN-on-diamond transistors and power amplifiers intersect with RF and satellite applications, giving it a device-level perspective that bridges substrate capability and system performance.
RFHIC Corporation adds a notable regional and application-specific strength, particularly in radar, microwave, and satellite-related uses where wafer and epi-level capability can shape downstream competitiveness. Coherent Corp. is relevant for its push to scale GaN-on-diamond wafers for broader commercial RF applications, which speaks to an important industry goal: moving performance-leading materials into markets that can absorb volume if the economics improve. Blue Wave Semiconductor rounds out the competitive picture with a focus on high-power RF and defense electronics, reinforcing the recurring theme that defense and high-performance communications remain central demand anchors for this substrate class.
Recent activity among these players makes the strategic stakes even clearer. In March 2025, Element Six introduced a new ultra-high-purity single-crystal diamond wafer optimized for RF and power device applications, underscoring the continued focus on material quality as a differentiator. In April 2025, Cree Inc. completed the acquisition of a diamond synthesis startup, a move that points toward greater vertical integration and an effort to strengthen control over key steps in the GaN-on-diamond product chain. In May 2025, Akash Systems secured CHIPS Act funding to advance diamond-cooling satellite technology, highlighting how public investment can accelerate development in strategically prioritized segments. In August 2025, a consortium of Japanese firms launched a regional diamond synthesis facility with the stated aim of improving supply chain resilience for GaN-on-diamond substrates, reflecting a broader push to reduce dependency risk in critical material flows. And in November 2024, Qorvo unveiled a GaN-on-diamond power amplifier for satellite communications designed to reduce thermal resistance, illustrating how product-level innovation continues to validate the material strategy in real deployments.
Together, these developments show a market that is not standing still. Participants are pursuing advancement through material improvement, acquisition, funding, regional capacity expansion, and product-level demonstrations. For customers and competitors alike, the implication is that the landscape will likely remain dynamic, with differentiation arising from purity, thermal performance, supply assurance, integration capability, and alignment with the highest-value applications.
Forces Shaping the Road Ahead: Friction, Policy, and Supply Realities
No strategic assessment of this market would be complete without acknowledging the forces that temper enthusiasm with operational realism. GaN on Diamond Semiconductor Substrates face several bottlenecks that influence both timing and economics. Supply chain bottlenecks in diamond wafer production and high production costs remain central constraints, limiting how quickly commercial scaling can proceed across broader applications. The cost associated with CVD diamond wafer fabrication and bonding processes adds further expense, which means that adoption is, at present, concentrated where the thermal and performance payoff is large enough to justify premium pricing. Limited global diamond wafer production capacity reinforces this dynamic by creating supply constraints that can slow ramp-up, particularly if demand accelerates faster than manufacturing can accommodate.
Geopolitical and policy factors are equally important. Supply disruptions tied to broader conflict-related logistics challenges have contributed to regional imbalances in substrate availability, reminding participants that material access is not purely a technical problem. At the same time, U.S. defense-related contracting activity continues to promote GaN-on-diamond integration in defense and hypersonic applications that impose demanding thermal and power density requirements. This type of demand does not merely add volume; it shapes product specifications, drives qualification priorities, and can pull the entire ecosystem toward higher performance benchmarks.
These dynamics create both opportunity and caution. For suppliers, the challenge is to expand capacity and reduce cost without compromising the material quality that makes the category compelling in the first place. For buyers, the challenge is to secure access to qualified substrates while avoiding over-reliance on narrow supply channels. For investors and strategists, the challenge is to separate durable structural growth from near-term optimism that may be vulnerable to cost, capacity, or geopolitical friction. The complete research study is designed to address these tensions head-on, offering the kind of operational context needed to evaluate entry timing, partnership strategy, and risk exposure with greater confidence.
What This Research Delivers for 2026 Planning
Strategic decisions in fast-moving technology markets are often made under incomplete information. The value of a strong industry study is not simply to confirm what leaders already suspect, but to equip them with structure, evidence, and scenario-ready intelligence that can be used in budgeting, sourcing, product planning, and competitive response. This GaN on Diamond Semiconductor Substrates market report is built around that practical purpose.
At the executive level, the study provides a clear view of historical performance and forward-looking growth dynamics, enabling leaders to assess whether the market is large enough, fast enough, and application-backed enough to justify dedicated attention in 2026 planning cycles. At the operating level, it goes further into the segmentation logic that matters for real decisions: type-wise distinctions, application-wise demand patterns, and regional participation. These breakdowns are essential for understanding where margin profiles may differ, where competition is more intense, and where strategic entry or partnership can be timed for maximum advantage.
The report also addresses the competitive field in a way that supports benchmarking and positioning. Rather than presenting company names as a static list, it frames them within the logic of what each participant is trying to achieve, how they are competing on material quality, device integration, and application fit, and what recent developments suggest about the direction of travel. That approach helps readers evaluate supplier partnerships, assess threat vectors, and anticipate where consolidation, capacity expansion, or targeted funding may alter market balance.
Equally important, the study integrates the operational and external forces that shape execution risk. Supply constraints, cost structures, geopolitical disruption, and defense-driven requirements are treated not as side notes, but as factors that affect viability, timing, and the realistic pace of commercialization. That context is especially valuable for organizations evaluating whether to adopt, invest, qualify, or partner, because the difference between a promising technology and a defensible business case often lies in those practical details.
Readers looking for the full strategic picture will find detailed segmentation values, market size trajectories, competitive profiles, and scenario-ready context in the complete report. Those details are intentionally not enumerated here, because the study is designed to function as a decision tool rather than a summary that can be fully consumed at a glance. The most useful reading of this category is one that connects the broad growth narrative with the granular intelligence required to act on it.
Worldwide Synthetic Single Crystal Diamond Market
The Strategic Takeaway
GaN on Diamond Semiconductor Substrates are transitioning from a high-performance exception to a strategically relevant platform for a defined set of demanding applications. That transition matters because thermal constraints are becoming more expensive to ignore and because the competitive landscape is evolving quickly through material innovation, funding, acquisition, regional capacity building, and product-level validation. The market's growth trajectory indicates that serious interest is warranted, but the real value lies in understanding the structure beneath the growth curve: which types lead, which applications drive demand, which regions matter most, and how supply and policy forces shape execution risk. For organizations planning in 2026, the question is no longer whether the category deserves attention. The question is whether they will engage with enough foresight to shape their own position rather than react to it later. The full research study is prepared to help answer that question with the precision that high-stakes semiconductor strategy requires.
GaN on Diamond Semiconductor Substrates Market
For detailed analysis of this topic, please visit the official page: GaN on Diamond Semiconductor Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DNS Security Software Market to Hit $310M by 2032 at 8.9% CAGR
By pmarketresearch, 2026-09-15
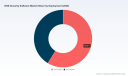
Navigating the DNS Security Revolution: Strategic Intelligence for the 2026 Enterprise Landscape
The digital perimeter has dissolved. In an era where hybrid workforces, cloud-native architectures, and interconnected critical infrastructure define operational reality, the Domain Name System (DNS) has evolved from a simple directory service into a primary battlefield for cyber adversaries. As organizations confront increasingly sophisticated threats that exploit DNS for data exfiltration, command-and-control communication, and distributed denial-of-service campaigns, the imperative for robust DNS security software has never been more acute. This strategic briefing introduces our latest comprehensive market research on the DNS Security Software sector, a publication engineered specifically to equip executive leadership, security architects, and investment strategists with the foresight required to navigate 2026 and beyond.
Our analytical framework draws upon a multi-year trajectory of observable market expansion. Between 2020 and 2025, the global DNS security software market demonstrated consistent upward momentum, reflecting the accelerated digital transformation initiatives and the escalating frequency of DNS-layer attacks across all sectors. By the close of 2025, the market had reached a mature inflection point, with total revenues positioning the industry for a structured, high-growth forecast period spanning 2026 through 2032. Market modeling indicates a compound annual growth rate of approximately 8.9 percent across this horizon, driven by the convergence of regulatory mandates, cloud migration imperatives, and the integration of artificial intelligence into threat detection workflows. This trajectory is not merely a statistical projection; it represents a structural realignment in how enterprises deploy, fund, and operationalize domain-layer security controls.
For decision-makers evaluating technology portfolios in 2026, this research functions as a strategic compass. It dissects the forces shaping procurement priorities, identifies the architectural paradigms gaining traction, and contextualizes the competitive maneuvers that will define market leadership in the coming years. The following sections outline the scope of the publication and the operational intelligence it delivers to stakeholders seeking to align security investments with organizational resilience objectives.
The Strategic Imperative: Why DNS Security Demands Executive Attention in 2026
DNS remains the foundational protocol that enables network communication, yet it has historically been treated as a utility rather than a security control. That paradigm is rapidly eroding. Adversaries now weaponize DNS to bypass traditional perimeter defenses, leveraging encrypted tunnels, fast-flux techniques, and domain generation algorithms to maintain persistent access while evading signature-based detection. The growing reliance on cloud-hosted workloads and distributed endpoints further amplifies the attack surface, making DNS-layer visibility and policy enforcement a non-negotiable component of modern security architectures.
Simultaneously, the regulatory environment is tightening around DNS infrastructure. Procurement guidelines now increasingly require encrypted DNS protocols for federal and critical infrastructure engagements, signaling a shift from voluntary adoption to compliance-driven deployment. In parallel, cybersecurity agencies and international policy frameworks are emphasizing the need for AI-enabled DNS analytics to counter adaptive threat behaviors. Organizations operating across North America, Europe, and Asia Pacific are responding by retooling their security stacks, prioritizing solutions that can provide real-time threat intelligence, automated remediation, and unified visibility across hybrid environments. These shifts create both urgency and opportunity for enterprises willing to invest in forward-looking DNS security capabilities.
Market Architecture and Momentum: A High-Level View of the 2026–2032 Outlook
Our research models the DNS security software market as a dynamic ecosystem shaped by deployment preferences, organizational scale, and industry-specific risk profiles. Over the forecast period, cloud-based delivery models are positioned to dominate adoption curves, reflecting the broader industry migration toward scalable, subscription-driven security services. At the same time, on-premises deployments continue to hold strategic relevance for organizations with stringent data sovereignty requirements or legacy infrastructure dependencies. The interplay between these deployment pathways will influence vendor positioning, service design, and integration strategies throughout the forecast window.
Adoption patterns also diverge across organization size and vertical exposure. Large enterprises are expected to drive a substantial portion of total spending, reflecting their complex infrastructure footprints, compliance obligations, and higher tolerance for integrated security platforms. Small and medium-sized enterprises, meanwhile, are accelerating their investment cycles as managed service providers and simplified cloud offerings lower the barrier to entry. In terms of vertical exposure, sectors that handle sensitive data or operate mission-critical network environments—such as financial services, healthcare, and government—are likely to sustain elevated investment levels, reinforced by sector-specific threat landscapes and regulatory expectations. The full report unpacks these structural drivers in greater detail, offering qualitative and quantitative analysis that maps adoption trajectories to operational outcomes.
Inside the Report: Actionable Intelligence for Technology, Procurement, and Investment Decisions
This market research publication is designed to move beyond high-level market sizing and deliver practical decision support. The report is structured to provide clear visibility into the forces shaping vendor selection, architecture planning, and long-term budget allocation. Key components include:
DNS Security Software Market
- Market Sizing and Forecast Modeling – A multi-year revenue trajectory analysis covering historical performance and projected growth through 2032, contextualized by macroeconomic indicators, threat trends, and adoption drivers.
- Deployment and Operational Patterns – An assessment of cloud-based versus on-premises adoption dynamics, including the operational implications of hybrid DNS architectures, integration requirements, and total cost of ownership considerations.
- Organizational and Vertical Demand Profiles – An examination of how spending behavior differs across enterprise scale and industry context, helping readers benchmark internal priorities against broader market demand signals.
- Competitive Positioning and Product Differentiation – A detailed review of leading vendors, their strategic capabilities, and the evolving product features that are reshaping buyer expectations in the DNS security category.
- Regulatory and Policy Impact Analysis – A synthesis of recent mandates and guidelines influencing DNS procurement, encryption requirements, and AI-enabled security expectations, with implications for compliance-driven buying cycles.
- Deployment Readiness and Implementation Considerations – Practical guidance on evaluating solution fit, integration complexity, visibility requirements, and remediation workflows for real-world enterprise environments.
By aligning these analytical dimensions, the report enables technology leaders to assess capability gaps, procurement teams to structure evaluation criteria, and investors to understand where durable competitive advantages are likely to emerge.
Competitive Dynamics: The Vendors Reshaping DNS Security Strategy
The market landscape is defined by a concentrated group of established vendors, each pursuing distinct strategic angles within the DNS security category. Market concentration metrics suggest a competitive arena where the top tier collectively commands a meaningful share of overall revenue, while the remaining addressable space continues to invite differentiation through innovation, partnerships, and domain-specific solutions.
Cisco Systems anchors its offering in cloud-delivered DNS-layer security integrated with threat intelligence capabilities, positioning its platform as a proactive defense mechanism that blocks malicious activity before a connection is established. Infoblox emphasizes protective DNS and threat defense designed to safeguard core DNS infrastructure from hijacking attempts, cache poisoning, and denial-of-service disruptions. Cloudflare has expanded its footprint through DNS firewall functionality and resolver services that incorporate built-in DDoS mitigation, DNSSEC support, and malware blocking for both enterprise and consumer environments. Akamai Technologies continues to leverage its edge network strength with DDoS-resilient DNS delivery and posture management capabilities for hybrid cloud security. F5 Networks, Verisign, and Neustar contribute additional depth to the competitive field, offering advanced DNS security, load balancing, authoritative DNS services, and threat intelligence features tailored to enterprise and critical infrastructure use cases.
Competitive differentiation is increasingly shaped by agility, visibility, and ecosystem alignment. A recent product development from Akamai illustrates this trajectory: the introduction of DNS Posture Management, an agentless solution designed to deliver unified multicloud visibility over DNS assets with real-time monitoring and remediation capabilities. Alongside such product movements, partnership activity is also reshaping go-to-market dynamics. In a notable collaboration, IGIT partnered with NS1 and Cisco to accelerate agile DNS security application deployments focused on the EMEA region. These developments highlight how vendors are expanding beyond baseline DNS protection to deliver broader operational resilience, cross-cloud oversight, and regionally targeted implementation strategies.
Regulatory Currents and Industry Shifts Redefining the DNS Security Agenda
Beyond competitive activity, the DNS security market is being reshaped by policy evolution and operational standards that influence how organizations validate and procure security capabilities. Recent regulatory and guidance developments are pushing enterprises toward more resilient, encrypted, and intelligence-driven DNS practices. The U.S. Executive Order requiring support for encrypted DNS protocols as a procurement condition for federal agency DNS resolvers has established a compliance precedent that reverberates beyond the public sector, encouraging vendors and enterprise buyers to prioritize encrypted transport and stronger integrity controls.
Domain Name System Tools Market
At the same time, cybersecurity guidance bodies are increasingly emphasizing AI-enabled DNS solutions as a response to attackers targeting critical infrastructure through DNS-based vectors. This shift reinforces the expectation that next-generation DNS security will combine protocol-level safeguards with behavioral analytics and automated response mechanisms. In parallel, national cybersecurity strategies in markets such as Japan are driving broader adoption of AI-enabled threat detection within DNS protection solutions, signaling a global trend toward smarter, more adaptive defense architectures. These policy directions are not abstract mandates; they actively shape procurement criteria, vendor evaluations, and long-term technology roadmaps.
What 2026 Decision-Makers Should Prioritize
For organizations planning security investments in 2026, the market signals point toward a few strategic priorities. First, DNS security should no longer be treated as an ancillary network function; it must be integrated into the broader security architecture as a control point for threat prevention, visibility, and compliance assurance. Second, enterprises should evaluate solutions based on their ability to operate across hybrid environments, provide encrypted DNS support, and integrate with existing orchestration, logging, and response workflows. Third, buyers should scrutinize vendor roadmaps for evidence of AI-enabled analytics, multicloud DNS posture visibility, and partnerships that accelerate deployment in targeted regions or verticals.
Procurement teams will also benefit from understanding how market demand varies across organization size and industry exposure, enabling them to calibrate solution scope, service levels, and total cost expectations. For investors and analysts, the concentration dynamics and recent product and partnership movements offer useful indicators of where consolidation, differentiation, and channel expansion are most likely to occur.
Conclusion: Toward a More Resilient DNS Security Posture
The DNS Security Software market is entering a phase defined by higher adoption expectations, stronger regulatory alignment, and accelerating technical differentiation. Our latest market research provides the structured intelligence required to interpret these changes and translate them into actionable enterprise strategy. By examining the market’s growth trajectory, deployment patterns, competitive movements, and policy-driven demand shifts, the report equips leaders with the perspective needed to make informed decisions in 2026 and throughout the forecast period.
To access the full analysis, including detailed market sizing, forecast breakdowns, competitive assessments, and implementation insights, readers are encouraged to explore the complete report on the PW Consulting research portal. The full publication expands on every dimension discussed here and provides the deeper intelligence necessary for precise strategic planning.
For detailed analysis of this topic, please visit the official page: DNS Security Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Data Diode Market Hits $215.75M in 2025, Projects 7.15% CAGR to $349.05M by 2032
By pmarketresearch, 2026-09-15
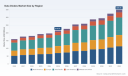
Navigating the Data Diode Market: Strategic Intelligence for the 2026 Enterprise Landscape
In an era where cyber threats increasingly target operational continuity and classified information flows, the Data Diodes Market has emerged as a critical infrastructure layer for organizations demanding uncompromising network isolation. As we move through 2026, enterprises across government, energy, and industrial sectors face mounting pressure to secure unidirectional data pathways without sacrificing real-time visibility or compliance readiness. The latest research from PW Consulting delivers a comprehensive, forward-looking analysis of this rapidly maturing market, equipping leadership teams with the analytical rigor needed to navigate technology selection, vendor evaluation, and long-term capital allocation.
This market intelligence report spans historical performance from 2020 through 2025 and extends its forecasting horizon to 2032, providing a complete view of the trajectory that has shaped today’s competitive environment. The global market, valued at approximately 215.75 million USD in 2025, is projected to reach 349.05 million USD by the close of the forecast period, reflecting a compound annual growth rate of 7.15%. These figures represent more than headline valuation; they map the steady structural expansion of hardware-enforced security architectures driven by regulatory mandates, critical infrastructure modernization, and the growing impossibility of relying on software-only isolation in high-assurance environments. Decision-makers who understand the underlying velocity of this growth can better anticipate procurement windows, align internal security roadmaps, and position their organizations ahead of supply chain bottlenecks.
Why This Research Matters for 2026 Decision-Making
Enterprise security leaders no longer operate in a landscape where data diode adoption is a niche consideration. The convergence of operational technology exposure, cross-domain data sharing requirements, and classified information handling protocols has transformed unidirectional gateways into foundational components of zero-trust and network segmentation strategies. Yet the market remains fragmented across product architectures, certification standards, and deployment contexts. Without a structured view of how these variables interact, procurement teams risk investing in solutions misaligned with operational realities or regulatory expectations.
The value of this report lies in its translational approach. Rather than presenting isolated metrics, the analysis connects market sizing trends to real procurement drivers, competitive positioning, and the evolving technical requirements that define successful deployments. Organizations preparing budgets for fiscal 2027, evaluating vendor shortlists, or designing secure OT/IT integration architectures will find actionable frameworks that reduce evaluation time and sharpen investment criteria. The research is structured to support multiple functions: cybersecurity architecture teams can reference product classification and certification pathways; operations leaders can assess deployment complexity and integration demands; and procurement executives can use the competitive landscape analysis to benchmark pricing rationales, service expectations, and long-term vendor viability.
Market Structure and Thematic Drivers
The market’s expansion has been shaped by a clear shift from legacy manual transport procedures toward automated, hardware-enforced one-way transfer. Organizations that previously relied on physical media movement or logistically heavy retrieval processes have documented annual costs ranging from 2,100 to 10,000 USD per workflow, alongside significant operational drag and human-error exposure. These inefficiencies have accelerated adoption among enterprises seeking repeatable, auditable, and tamper-resistant data flow controls. At the same time, regulatory alignment has become a decisive purchasing factor. Unidirectional gateway architectures are increasingly evaluated against established industrial cybersecurity guidance, including frameworks that emphasize lateral movement prevention in operational technology environments. Certifications issued by national defense and security authorities have also become key differentiators, particularly for organizations managing information at classified or restricted levels.
The report provides a detailed breakdown of how product types, application domains, and regional demand patterns interact to shape total addressable opportunity. While the overall market continues to grow at a steady pace, the underlying composition reveals a landscape where ruggedized and specialized form factors are gaining relevance in harsh-environment deployments, and where high-throughput protocol filtering diodes are redefining performance expectations in defense and critical infrastructure contexts. Rather than presenting static splits, the analysis explains how each segment responds to distinct deployment constraints, certification requirements, and integration pathways, enabling buyers to map their operational profile to the most relevant technology categories.
Competitive Landscape: Leaders Shaping the Unidirectional Security Market
No examination of this market would be complete without a rigorous assessment of the companies defining its direction. The competitive environment is characterized by a mix of specialized security vendors, industrial networking providers, and defense-oriented engineering firms, each pursuing distinct value propositions across certification, throughput, environmental hardening, and integration depth. The research profiles a broad set of market participants, including Owl Cyber Defense, OPSWAT, Fibersystem AB, Patton Electronics, Advenica, BAE Systems, Waterfall Security Solutions, ST Engineering, Nexor, Garland Technology, Valiant Communications, and Everfox.
The competitive analysis goes beyond corporate descriptions to examine how each organization’s offering aligns with market demand signals. In the defense and government segment, vendors with validated protocol filtering capabilities and high-assurance transfer performance have gained renewed attention as cross-domain requirements intensify. In industrial and operational technology environments, the emphasis has shifted toward hardware-enforced isolation combined with software intelligence that can sanitize, replicate, and contextualize data flows without exposing control networks. Ruggedized and TEMPEST-aligned product families continue to serve niche but strategically vital deployments where electromagnetic emission control and extreme environmental tolerance are non-negotiable. Meanwhile, companies focused on standardized DIN-rail form factors and industrial protocol support have expanded the practical usability of data diodes in manufacturing and process automation settings.
Recent corporate activity underscores the pace of differentiation. In early 2026, Owl Cyber Defense received U.S. Government verification for its Talon Torrent as an approved protocol filtering diode capable of reliable one-way transfer up to 100 Gbps, reinforcing the importance of certified performance in high-throughput defense and critical infrastructure applications. That same year, the company introduced a pocket-sized Incident Response Diode designed for forensic evidence collection from compromised endpoints through USB, using hardware-enforced one-way protocol filtering. This product direction illustrates a broader market trend: data diodes are increasingly evaluated not only for bulk data transfer, but also for specialized incident response, evidence preservation, and targeted operational workflows. Shortly thereafter, Owl integrated VTScada SCADA software with its data diode portfolio to enable secure one-way operational data transfer from OT to IT and cloud environments in water and wastewater systems, with initial deployments in Houston and Nashville. These moves demonstrate how vendors are extending the reach of unidirectional security into live operational networks where continuous monitoring and secure telemetry are essential.
Across the broader field, product launches have reflected the market’s diversification. Advenica introduced a data diode engineered specifically for railway trackside applications, compliant with EN railway standards and designed to operate without additional security software, highlighting the demand for deployment simplicity in transportation infrastructure. Patton Electronics expanded its industrial networking portfolio with a DIN-rail FiberPlex FP-DD100 data diode supporting OPC UA and MQTT protocols, reinforcing the importance of protocol readiness in plant and factory environments. Advenica’s product documentation also underscores N3 certification under Swedish Armed Forces standards for information up to TOP SECRET levels, illustrating how national certification frameworks continue to influence procurement decisions in sensitive government and defense contexts. These developments are not isolated highlights; they are indicators of how product strategy, standards alignment, and deployment context are converging across the competitive landscape.
Deployment Dynamics, Regulatory Alignment, and Infrastructure Considerations
One of the most valuable contributions of this research is its treatment of deployment realities. Data diodes are no longer evaluated solely on their ability to enforce one-way flow; buyers now assess integration complexity, environmental suitability, protocol coverage, and the broader security ecosystem in which the device will operate. In industrial monitoring and network segmentation contexts, diode TAPs have become part of the foundational infrastructure for enabling raw data flow without exposing sensitive control planes. In OT/ICS environments, unidirectional gateways are increasingly scrutinized for their ability to align with established cybersecurity guidance and to reduce lateral movement risk across networks of differing trust levels. The report examines these operational dynamics in detail, connecting them to procurement criteria such as certification traceability, maintenance requirements, and long-term interoperability.
The analysis also addresses the role of certification and regulatory alignment as procurement accelerators. Where national defense certifications, Common Criteria evaluations, and industrial cybersecurity frameworks apply, they shape not only product eligibility but also the timeline and confidence with which enterprises can deploy solutions. For organizations operating in multi-jurisdictional environments, understanding which certifications carry weight in which sectors can materially influence vendor selection and deployment sequencing. The report maps these considerations to real purchasing behavior rather than abstract compliance language, helping decision-makers anticipate which validation pathways will matter most for their specific operating environment.
Rectifier Diode Market
How the Report Supports Actionable Strategy
This research is designed for practical use. It provides structured coverage across market sizing, segmentation logic, competitive benchmarking, and deployment context, giving organizations a single reference point for strategy development. Readers will find detailed profiles of market participants, an assessment of recent product launches and partnership activity, and analysis of how certification status and technical architecture influence adoption in different sectors. The report examines market concentration indicators and competitive dispersion to help buyers understand where consolidation pressure exists and where specialized differentiation remains viable. It also outlines the operational and regulatory forces that are likely to shape demand through the end of the forecast period, enabling leadership teams to prepare for supply alignment, capability planning, and procurement timing.
Importantly, the report avoids superficial vendor rankings or static market splits. Instead, it explains how different product categories perform under varying operational constraints, which certification pathways carry the most weight in different sectors, and how integration requirements influence total cost and deployment risk. This approach ensures that the findings can be used not only for immediate purchasing decisions but also for longer-term security architecture planning and portfolio strategy.
Data Diodes Market
Conclusion: Moving From Awareness to Informed Execution
The Data Diodes Market is no longer defined by incremental interest; it is being reshaped by tangible operational needs, certification expectations, and the growing recognition that hardware-enforced unidirectional transfer is essential in environments where software-only isolation is insufficient. With a market trajectory that reflects steady expansion toward a valuation of 349.05 million USD by 2032 and a compound annual growth rate of 7.15%, the sector presents both opportunity and complexity for enterprises seeking to strengthen their security posture. The difference between reactive adoption and strategic execution lies in the quality of market intelligence guiding the decision process.
This PW Consulting report provides that intelligence. It equips cybersecurity leaders, operations executives, and procurement professionals with the context needed to evaluate vendors, align technology choices with operational requirements, and anticipate the regulatory and competitive dynamics that will influence the market through the end of the decade. For organizations preparing to commit resources in 2026 and beyond, the full analysis offers the depth, structure, and strategic framing necessary to turn market momentum into informed action. The complete market intelligence, including detailed segmentation analysis, competitive benchmarking, and forward-looking procurement guidance, is available through the full report.
For detailed analysis of this topic, please visit the official page: Data Diodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Advanced CO2 Sensors Market Hits $690M in 2025, Projected to Reach $1.12B by 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Advanced CO2 Sensors Market: Navigating Growth and Regulation Through 2032
The global transition toward smarter, healthier, and more energy-efficient environments has placed advanced carbon dioxide sensing technology at the center of industrial and commercial strategy. For executives, procurement leaders, and innovation managers, the question is no longer whether to invest in CO2 sensing infrastructure, but how to navigate a rapidly evolving landscape defined by tightening regulations, technological miniaturization, and shifting demand patterns. PW Consulting's latest Advanced CO2 Sensors Market research provides a comprehensive blueprint for understanding these forces, offering decision-makers the granular intelligence required to allocate capital, shape product roadmaps, and secure competitive positioning between 2026 and 2032.
Market Trajectory and Macroeconomic Context
The market for advanced CO2 sensors has demonstrated consistent expansion over the past half-decade, driven by the convergence of environmental awareness, building efficiency mandates, and industrial safety requirements. Historical data from 2020 through 2025 reveals a sector that has successfully navigated supply chain disruptions and component shortages to deliver robust revenue growth. The baseline year of 2025 anchors the market at approximately USD 690.0 million, a substantial increase from the USD 475.8 million recorded in 2020. This upward trajectory reflects not merely cyclical recovery but structural demand shifts that are reshaping procurement priorities across multiple verticals.
Looking forward, our forecast period spanning 2026 through 2032 projects sustained momentum for the industry. By 2026, market revenue is anticipated to cross USD 754.4 million, with growth compounding steadily toward the USD 1.1 billion threshold by 2032. The compound annual growth rate of 7.1 percent during this window underscores the durability of underlying demand drivers, even as macroeconomic headwinds and inflationary pressures continue to influence capital expenditure decisions globally. For enterprises evaluating market entry, capacity expansion, or portfolio diversification, this growth curve provides a critical baseline for scenario planning and investment justification.
Several structural factors underpin this expansion. The acceleration of demand-controlled ventilation (DCV) deployments in both new construction and retrofit projects has generated a reliable pipeline of sensor requirements. Simultaneously, the proliferation of Internet of Things (IoT) architectures and the push toward smart building certifications have elevated CO2 monitoring from a compliance checkbox to a foundational component of operational strategy. Industries ranging from healthcare to automotive and petrochemical processing are recalibrating their air quality standards, recognizing that real-time gas detection capabilities directly influence occupant health, regulatory compliance, and energy expenditure optimization.
Regulatory Tailwinds and Industry Dynamics
Regulatory frameworks are emerging as perhaps the most potent catalyst for market growth, transforming CO2 sensing from an optional enhancement into a compliance necessity in key jurisdictions. The ANSI/ASHRAE Standard 62.1-2022 Addendum d has established stringent requirements for demand-controlled ventilation systems, mandating precise CO2 measurement to achieve energy-efficient building codes. This standard has compelled building owners, HVAC integrators, and sensor manufacturers to align their product specifications with rigorous performance thresholds, creating a measurable uplift in demand for high-accuracy sensing solutions.
Beyond North American standards, the European Union's Energy Performance of Buildings Directive has set a trajectory toward zero-emission standards for new buildings by 2030. This directive not only imposes emission targets but also drives demand for advanced CO2 sensors integrated into DCV systems, as building operators seek to demonstrate compliance while minimizing energy consumption. The intersection of these regulatory mandates with certification frameworks such as RESET Grade B and the WELL Building Standard v2 has further broadened the addressable market, requiring sensor technologies that can satisfy overlapping compliance criteria without compromising deployment economics.
Advanced CO2 Sensors Market
These regulatory dynamics interact with technological advancement in ways that reshape competitive battles. Manufacturers are now evaluated not only on measurement accuracy but also on form factor, power consumption, integration compatibility, and certification readiness. The pressure to meet multiple standards simultaneously has accelerated innovation cycles and compressed development timelines, placing a premium on research and development agility. Companies that fail to align their sensor portfolios with evolving regulatory expectations risk marginalization, while those that proactively embed compliance into their product architecture are positioned to capture disproportionate market share.
Survey of the Competitive Landscape
The advanced CO2 sensors market is characterized by a concentrated competitive structure, with the top three players accounting for approximately 55 percent of market revenue and the top five controlling an estimated 68 percent. This concentration reflects the technical barriers to entry, the capital intensity of optical sensing research, and the long qualification cycles associated with building automation and industrial applications. Nevertheless, the market remains dynamic, with established players and emerging innovators competing on dimensions beyond raw market share, including technological differentiation, regional footprint, and ecosystem integration capabilities.
Senseair, headquartered in Sweden, has built its reputation on ultra-compact NDIR CO2 sensors designed for demand-controlled ventilation and indoor air quality monitoring. The S12 series exemplifies the company's focus on size reduction and surface-mount device integration, enabling OEMs to embed sensing capabilities in space-constrained smart building environments. In January 2026, Senseair launched a new iteration of the S12 sensor, achieving a 75 percent size reduction relative to predecessors while maintaining SMD solderability. The product is positioned as compliant with ASHRAE 62.1-2022 Addendum d, RESET Grade B, and WELL Building Standard v2 standards, and mass production is slated for 2026 following sample distribution.
Sensirion AG, based in Switzerland, has differentiated itself through high-accuracy photoacoustic NDIR CO2 sensors, most notably the SCD4x series and the recently announced SCD43. The SCD43, launched in February 2025 as a drop-in upgrade for the SCD4x platform, delivers best-in-class accuracy of ±(30 ppm + 3% m.v.) and targets compliance with ASHRAE 62.1 Draft Addendum d. By offering summer 2025 availability, Sensirion has signaled its intent to capture demand from building standards compliance and compact environmental monitoring applications. The photoacoustic approach allows for competitive performance in form factors that would be challenging for traditional NDIR implementations, broadening the application envelope for precision sensing.
Gas Sensing Solutions, operating from the United Kingdom, has focused on the CozIR series of solid-state NDIR CO2 sensors optimized for ultra-low power consumption. These devices are particularly relevant for IoT deployments and battery-powered applications where energy efficiency dictates operational viability. The integration of environmental sensing capabilities within a single package positions the CozIR series as a versatile solution for remote monitoring scenarios, where maintenance logistics and power constraints are paramount considerations.
Vaisala Oyj, a Finnish manufacturer, leverages advanced optical technology to produce NDIR CO2 sensors tailored for precision building management, industrial environments, and data-center applications. The emphasis on stability and reliability under demanding conditions has made Vaisala a preferred choice for mission-critical deployments where sensor drift or failure carries significant operational consequences. Amphenol Advanced Sensors, based in the United States, complements this landscape by supplying compact and low-power CO2 sensors for HVAC, IoT, and environmental monitoring applications, with a particular focus on miniaturization without sacrificing measurement accuracy.
Air Quality Sensor Market
The competitive field also includes integrators and diversified technology conglomerates. Siemens AG, headquartered in Germany, embeds NDIR CO2 sensor modules directly into building management systems, offering portfolios that address HVAC and air quality control requirements within broader automation architectures. Honeywell International Inc., also US-based, provides both chemical and infrared CO2 sensors targeted at safety, indoor air quality, and industrial applications, with low-power draw options that align with energy-conscious deployment strategies. These diversified players illustrate how CO2 sensing is increasingly being absorbed into larger ecosystem plays, where value is created through system-level integration rather than sensor component sales alone.
Segmentation Insights and Structural Demand Drivers
The market structure reveals distinct demand clusters that inform go-to-market strategies for manufacturers and procurement decisions for end users. In terms of technology type, NDIR CO2 sensors dominate the revenue landscape, reflecting the industry's preference for optical-based measurement techniques that offer long-term stability, minimal drift, and compatibility with continuous monitoring applications. Chemical CO2 sensors occupy a meaningful secondary position, serving applications where cost profile, power constraints, or specific environmental characteristics favor alternative sensing mechanisms. The coexistence of these technology pathways highlights the absence of a one-size-fits-all solution and the importance of matching sensor architecture to application requirements.
Application segmentation further illuminates where value is being created. Building automation represents the largest demand pool, aligning with the regulatory and certification dynamics discussed earlier. The integration of CO2 sensing into HVAC control loops, occupancy-based ventilation strategies, and indoor air quality dashboards has become a standard expectation rather than a premium feature. Healthcare applications constitute the second major pillar, driven by infection control protocols, operating room environmental management, and patient comfort standards that demand reliable gas monitoring. Industrial applications follow closely, encompassing process monitoring, safety systems, and environmental compliance in manufacturing and processing facilities.
The automotive and petrochemical segments, while smaller in aggregate revenue terms, represent high-growth niches where sensor requirements are shaped by distinct constraints. Automotive applications demand robustness, fast response times, and integration with cabin air quality management systems, while petrochemical deployments prioritize accuracy under challenging atmospheric conditions and compliance with safety regulations. The geographic distribution of demand mirrors these application dynamics, with developed markets in North America and Europe maintaining the largest shares due to regulatory maturity and building stock renovation cycles, while Asia Pacific and other emerging regions are expanding as construction activity intensifies and standards adoption accelerates.
It is critical for stakeholders to recognize that these segmentation patterns are not static. As new building standards take effect, as IoT deployment models mature, and as manufacturing automation deepens, the relative weight of each application segment will shift. Our research provides the framework for anticipating these shifts, identifying leading indicators of demand migration, and recalibrating product and sales strategies before competitors react.
Report Scope and Actionable Intelligence
PW Consulting's Advanced CO2 Sensors Market research is designed to equip decision-makers with more than macro-level trends. The full report delivers a multi-dimensional analysis that bridges strategic vision with operational execution, structured around the following core components:
- Historical and Forecast Revenue Analysis: A detailed chronological breakdown spanning 2020 through 2032, enabling readers to validate growth assumptions, identify inflection points, and benchmark internal performance against market trajectories.
- Technology-Type Deep Dive: Comprehensive profiling of NDIR and chemical sensor categories, including performance characteristics, cost structures, integration considerations, and suitability profiles for specific application environments. This section equips R&D and product management teams with the technical context needed to prioritize development investments.
- Application-Specific Demand Mapping: Granular examination of building automation, healthcare, industrial, automotive, and petrochemical use cases, with attention to deployment drivers, specification requirements, purchase decision workflows, and pricing dynamics. Procurement leaders and sales strategists will find actionable guidance for segment-specific positioning.
- Regional Market Intelligence: Analysis of demand distribution and growth prospects across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The report examines regulatory adoption timelines, construction activity indicators, and competitive intensity in each region, enabling geographic resource allocation decisions.
- Corporate Profiles and Strategic Positioning: Detailed assessments of leading manufacturers, covering headquarters, product portfolios, technological differentiators, recent launches, and strategic implications. Profiles include Senseair, Sensirion AG, Gas Sensing Solutions, Vaisala Oyj, Amphenol Advanced Sensors, Siemens AG, and Honeywell International Inc., with attention to how each competitor is navigating the current landscape.
- Recent Developments Tracker: A chronologically organized record of product launches, regulatory updates, and strategic moves. Notable entries include Senseair's January 2026 S12 sensor launch and Sensirion's February 2025 SCD43 announcement, contextualized within the broader compliance and standards environment.
- Competitive Concentration and Market Structure Analysis: Evaluation of market concentration metrics, barriers to entry, consolidation risks, and partnership opportunities. This section supports M&A screening, competitive benchmarking, and strategic positioning exercises.
- Executive Summary and Strategic Recommendations: A synthesized overview tailored for C-suite audiences, translating analytical findings into prioritized action items for investment, innovation, partnership, and market entry decisions.
Each section is structured to facilitate rapid extraction of relevant insights while providing sufficient depth for thorough strategic analysis. Decision-makers are encouraged to consult the full report for the complete dataset, including segmentation splits, regional breakdowns, and detailed revenue figures that inform precise planning assumptions.
Strategic Recommendations for 2026 and Beyond
The intersection of regulatory momentum, technological innovation, and market growth creates a window of strategic opportunity that demands decisive action. For manufacturers and technology providers, the imperative is to accelerate development cycles while ensuring that sensor architectures are validated against the most demanding current standards, including ASHRAE 62.1-2022 Addendum d and relevant certification frameworks. Product roadmaps that prioritize miniaturization, low power consumption, and integration readiness will resonate with the IoT-driven deployment models that are expanding addressable use cases. Investment in photoacoustic and advanced NDIR technologies should be viewed not as optional enhancement but as foundational capability required to defend market position.
For end-user organizations and integrators, the priority lies in aligning procurement strategies with the trajectory of regulatory tightening and building certification requirements. Specifications should be updated to reflect the accuracy thresholds and compliance attributes demanded by emerging standards, and vendor evaluation criteria should incorporate long-term drift performance, certification documentation, and ecosystem compatibility alongside initial cost considerations. Procurement processes that favor lowest upfront price may inadvertently increase lifecycle costs through calibration frequency, premature replacement, or non-compliance penalties.
For investors and market entrants, the concentration structure of the industry signals both barriers and opportunities. Incumbents benefit from established qualification relationships and technical reputation, but the pace of innovation and the breadth of new application domains create openings for differentiated offerings. Targeting underpenetrated verticals, developing region-specific compliance packages, or pursuing strategic partnerships with building automation platforms can provide pathways to growth even in a concentrated market environment.
Conclusion: Securing Competitive Advantage Through Intelligence
The Advanced CO2 Sensors Market is entering a phase where regulatory discipline, technological capability, and demand expansion converge to reward organizations that invest in structured, data-backed strategic decision-making. The historical growth record, the projected 7.1 percent CAGR through 2032, and the active regulatory landscape collectively affirm that CO2 sensing is a strategic technology rather than a discretionary purchase. Yet the complexity of segmentation, the intensity of competition, and the velocity of standard evolution demand more than high-level awareness. They require detailed intelligence that informs specific investments, product specifications, geographic prioritization, and partnership choices.
PW Consulting's full market research report delivers the depth required to navigate this environment with confidence. By accessing the complete analysis, stakeholders will gain the segmentation data, regional breakdowns, revenue trajectories, and competitive profiles necessary to transform market awareness into actionable strategy. We invite executives, product leaders, and investment professionals to engage with the full report, exploring the comprehensive dataset and analytical frameworks that underpin the insights presented here. The path from regulatory pressure to commercial advantage runs through informed decision-making, and the intelligence contained in this research is structured to empower that journey.
For detailed analysis of this topic, please visit the official page: Advanced CO2 Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Power Cords Market to Hit $6,680M by 2032, Driven by 6.2% CAGR
By pmarketresearch, 2026-09-15
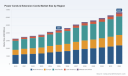
Strategic Intelligence in the Power Cords and Extension Cords Market: Navigating the 2026–2032 Forecast
As global electrification accelerates, infrastructure upgrades multiply, and connected devices proliferate across every sector, the power distribution ecosystem has become a focal point for strategic procurement, manufacturing planning, and competitive positioning. The Power Cords & Extension Cords Market is no longer a commoditized afterthought; it is a dynamic, regulation-sensitive, and geographically divergent segment where supply chain resilience, material economics, and compliance agility dictate margins. PW Consulting’s latest market research delivers a comprehensive, data-anchored view of this landscape, calibrated specifically to inform enterprise decisions across the 2026–2032 horizon.
This article serves as a strategic preview of the full report. It frames the macroeconomic trajectory, outlines the analytical architecture of the study, highlights the competitive dynamics shaping the sector, and embeds the latest regulatory and raw material developments that are already influencing sourcing strategies and product roadmaps. The objective is to demonstrate the report’s decision-ready rigor while preserving the granular breakdowns, scenario modeling, and proprietary benchmarking that reside in the complete publication.
Appliance Power Cord Market
Market Trajectory and the 2026–2032 Growth Arc
The historical baseline tells a clear story of steady, compounding expansion. From 2020 through 2025, the global market scaled from approximately 3.26 billion USD to an estimated 4.40 billion USD, reflecting resilient end-user demand, sustained construction and renovation activity, and the ongoing electrification of both consumer and commercial environments. That momentum carries decisively into the forecast window: the market is projected to reach roughly 4.63 billion USD in 2026 and continue its upward path toward approximately 6.68 billion USD by 2032.
Central to this trajectory is a sustained compound annual growth rate of 6.2 percent across the forecast period. While the headline figure signals healthy expansion, the real strategic value lies in what drives it. Growth is not uniformly distributed; it is being shaped by diverging regional development cycles, application-specific procurement patterns, and a structural split between indoor deployment, outdoor resilience requirements, and heavy-duty industrial specifications. Enterprises that treat the market as a single block risk misallocating capacity, mispricing SKUs, or overlooking compliance-driven substitution trends. The full report disentangles these layers, offering a calibrated view of where volume concentrates, where margin profiles diverge, and where short-cycle demand spikes are most likely to emerge.
For CFOs and supply chain leaders, the forecast is not merely a planning number; it is a stress test for inventory architecture, vendor diversification, and capital allocation. For product managers, it frames which performance tiers and certification pathways will command premium positioning. For competitive intelligence teams, it establishes the baseline against which market share shifts, pricing pressure, and regional entry timing can be measured.
Report Architecture: From Macro Signals to Operational Playbooks
The study is engineered to move beyond descriptive sizing and into actionable strategy. It combines rigorous historical reconstruction with forward-looking scenario analysis, giving leadership teams a multi-dimensional lens on demand, supply, and regulatory risk. The report’s structure is designed for direct integration into corporate planning cycles, with sections that translate market intelligence into procurement calendars, product portfolio decisions, and geographic expansion logic.
Readers can expect detailed segmentation mapping that clarifies how volume and value split across deployment environments and end-use contexts, without reducing the market to a single average. The analysis distinguishes between indoor configurations that dominate routine consumer and commercial setups, outdoor-rated solutions that must satisfy weather, abrasion, and UV resilience requirements, and heavy-duty variants engineered for sustained industrial loads and harsher operating conditions. Each category carries distinct material specifications, testing regimes, and price elasticity characteristics, and the report maps these differences to sourcing implications and commercial positioning.
Equally critical is the regional lens. Demand is shaped by local construction rhythms, retrofit cycles, data center build-outs, healthcare facility upgrades, and the pace of electrification in both developed and emerging markets. The publication provides a structured geographic framework that helps executives prioritize distribution partnerships, assess tariff and logistics exposure, and anticipate where certification requirements will create barriers or opportunities. Rather than presenting static share snapshots, the report contextualizes regional behavior within infrastructure spending patterns, import/export flows, and local compliance timelines.
The report also embeds procurement-relevant indicators, including material price trajectories, lead-time sensitivity, and the operational impact of standards revisions. By linking market size dynamics to the cost and compliance variables that actually move margins, the study enables scenario planning that is grounded in operational reality rather than theoretical growth curves.
Competitive Landscape: Coexistence of Scale Players and Niche Specialists
The competitive structure of the power cords and extension cords market reflects a deliberate division of labor between broad-line manufacturers and application-focused specialists. The full report profiles a cross-section of companies that illustrate how different strategic postures coexist within the same industry, each capturing value through distinct combinations of geographic reach, certification depth, and product engineering.
Southwire Company LLC, headquartered in Carrollton, GA, exemplifies the integrated producer that anchors its offerings in building wire, cable, and extension cords for utility, industrial, and commercial applications. Its position underscores the importance of vertical cohesion between core wire infrastructure and downstream power delivery products. Volex plc, based in Basingstoke, Hampshire, operates as a global integrated manufacturer of power cords, plugs, connectors, and custom wiring harnesses, serving consumer, industrial, and data center uses. Its profile highlights the strategic premium associated with custom configuration capabilities and multi-market qualification portfolios.
In residential and commercial electricals, Havells Ltd and Goldmedal Electricals demonstrate how regional manufacturing strength and broad distribution networks can secure enduring share in home electricals, flexible cables, switches, and power accessories. Their presence reinforces the reality that volume-driven segments reward brand trust, retail access, and consistent compliance execution as much as technical differentiation. At the same time, specialized manufacturers such as Ningbo Biaoda Electric Co., Ltd., YFC-Boneagle Electric Co., Ltd., Kord King, Electri-Cord Manufacturing, Jiaxing Hongzhou Cable Co., Ltd., Webber Electronics, Inc., Z-Tronix Inc., and Quail Electronics, Inc. illustrate the depth of capability available for hospital-grade, medical, dental, industrial, OEM, and international configuration requirements. These players often compete on certification breadth, custom cord-set engineering, and the ability to serve demanding end-use standards rather than on undifferentiated volume alone.
Strategically, the market structure matters because it shapes sourcing flexibility. Buyers can calibrate their supplier base between scale reliability and specialized compliance, while manufacturers must decide whether to compete on breadth, on certified performance in high-stakes applications, or on speed and configuration agility. The full report examines these positioning choices in greater depth, mapping how company footprints align with the segmentation and regional dynamics that drive demand.
Power Cords & Extension Cords Market
Regulatory and Material Dynamics Reshaping Sourcing Calculus
The market’s forward path is increasingly conditioned by the interplay of standards evolution and raw material economics. Two dynamics deserve particular attention because they directly influence product design, qualification timelines, and cost structures.
On the regulatory side, the July 30, 2025 revision of UL 817 introduced new requirements for Heater-Use Power-Supply Cords, with the broader standard for Cord Sets and Power-Supply Cords having been updated on the same date. For manufacturers and specifiers, this is not a procedural footnote; it is a product definition event. Heater-related applications impose distinct thermal, loading, and safety expectations, and revisions of this nature typically trigger requalification cycles, documentation updates, and in some cases material or construction adjustments. Companies that anticipate the operational implications of UL 817 changes can shorten time-to-compliance and reduce the risk of specification rejections, while those that treat standards revision as a back-office task may face delayed launches and eroded quoting accuracy.
On the cost side, polymer pricing remains a central variable in cord and cable economics. As of April 2026, PVC pricing diverged meaningfully by geography: China PVC prices reached approximately 735.45 USD per metric ton, while U.S. PVC prices stood at about 822.45 USD per metric ton. That gap is strategically significant for any organization balancing offshore sourcing, domestic production, inventory timing, and pass-through pricing. Material volatility of this nature influences not only direct cost of goods, but also the relative attractiveness of different product tiers, the feasibility of long-term supply agreements, and the negotiation leverage between buyers and suppliers. It also interacts with certification requirements, since material substitution in response to cost pressure must still satisfy performance and safety expectations.
Together, these forces define a market environment where compliance agility and input-cost intelligence are competitive differentiators. The full report integrates these developments into the broader dynamics section, linking standards and materials to segmentation behavior, regional cost structures, and the strategic options available to both producers and procurement organizations.
Why the 2026 Decision Window Demands This Level of Intelligence
Entering 2026, enterprises face a convergence of planning imperatives that makes high-resolution market intelligence essential. Demand is expanding at a durable pace, but the composition of that demand varies by environment, application, and region. Standards are being refined in ways that affect product eligibility and qualification lead times. Material pricing is diverging across geographies, altering the economics of sourcing models that may have appeared balanced on paper. In this context, decisions made on the basis of coarse market narratives are increasingly likely to produce suboptimal capacity allocation, misaligned SKU emphasis, or unanticipated compliance exposure.
The strategic value of this study lies in its ability to convert these moving parts into a coherent decision framework. It helps leadership teams answer practical questions: where should inventory and production emphasis be placed to match the most resilient demand pools; which product categories carry the strongest combination of volume and margin durability; how should supplier portfolios be structured to absorb material volatility and certification cycles; and where do regional dynamics create entry timing advantages or risks. By anchoring these questions in a 2026–2032 horizon, the report enables plans that are forward-compatible rather than reactive.
For organizations that compete on reliability, certified performance, or configuration agility, the publication also serves as a benchmarking foundation. Understanding how market size, segmentation behavior, and competitive positioning interlock makes it possible to calibrate go-to-market priorities, refine pricing strategy, and anticipate where differentiation will command premium attention in specification processes.
What the Complete Study Unlocks
This preview has outlined the structural logic of the market, the trajectory implied by the historical and forecast data, the competitive architecture that defines how value is captured, and the regulatory and material variables that are already reshaping operational calculus. The full report extends well beyond this frame. It delivers the detailed segmentation analysis, regional demand context, company profiling depth, standards impact assessment, and material-cost sensitivity perspective needed to translate macro direction into executable plans.
Because the study is designed to support real-world decision cycles, the complete version includes the granular breakdowns, scenario considerations, and benchmarking references that leadership teams require when setting procurement calendars, prioritizing product development, evaluating distribution geography, and stress-testing sourcing strategies against regulatory and input-cost shifts. These elements are intentionally developed in full within the publication so that readers can apply them directly to internal planning without having to reconstruct the underlying logic.
For executives, analysts, and operations leaders who need to align strategy with the realities of a growing but increasingly complex market, the complete research offers the evidentiary base and structural clarity required to move from awareness to action. To access the full segmentation detail, competitive profiles, regional context, and compliance and materials analysis, and to integrate the complete forecast with your internal planning models, visit the source page for the Power Cords & Extension Cords Market research and obtain the full report.
For detailed analysis of this topic, please visit the official page: Power Cords & Extension Cords Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Employee Scheduling Software Market Hits $225M in 2025, Poised for 11.2% CAGR Through 2032
By pmarketresearch, 2026-09-15
Navigating the Future of Workforce Optimization
The landscape of employee scheduling software is undergoing a seismic shift, driven by the convergence of artificial intelligence, stringent compliance mandates, and the enduring need for operational resilience. As organizations transition from reactive staffing models to proactive workforce orchestration, the strategic importance of dedicated scheduling technology has never been more pronounced. In response to accelerating market velocity, PW Consulting is pleased to unveil its latest research publication: the Employee Scheduling Software Market analysis, covering the trajectory from 2020 through 2032. This report serves as a definitive guide for executives, HR leaders, and investment strategists seeking to align their technology roadmaps with the next cycle of enterprise growth.
Drawing on a rigorous historical baseline and a forward-looking forecast horizon, this study offers a 360-degree view of the ecosystem. From technological bifurcation to competitive intensity, the following pages dissect the forces reshaping how organizations plan shifts, manage labor costs, and ensure regulatory adherence. The insights herein are curated to empower data-driven decisions that balance cost efficiency with employee experience in an increasingly fluid work environment.
Market Overview and Strategic Trajectory
The global employee scheduling software market has demonstrated remarkable durability and expansion over the past half-decade. Historical data from 2020 to 2025 illustrates a clear and sustained upward trajectory, reflecting the market’s critical role in modern workforce management. As organizations adapt to hybrid work models, fluctuating demand patterns, and evolving labor expectations, the foundational value of scheduling technology has expanded well beyond simple shift assignment. This growth phase has been characterized by a fundamental shift in operational philosophy. Where scheduling was once treated as an administrative task embedded within broader HR systems, it has emerged as a strategic lever capable of unlocking significant productivity, cost, and compliance advantages.
Nurse Scheduling Software Market
Looking ahead, the forecast period from 2026 to 2032 signals continued robust expansion. The market is projected to follow a sustained compound annual growth rate of 11.2 percent, a figure that underscores the accelerating adoption of dedicated workforce orchestration platforms across diverse operational environments. This growth trajectory is not merely a reflection of digital transformation trends; it is a direct response to the operational complexities that modern enterprises face daily. Organizations that recognize scheduling software as a core component of their workforce strategy, rather than a peripheral utility, are consistently better positioned to navigate labor volatility, optimize coverage, and maintain service continuity under unpredictable conditions.
From a macro perspective, the market has progressed from 148.5 million USD in 2020 to a baseline of 225.0 million USD in 2025. The momentum carries forward, with the market projected to reach 250.71 million USD in 2026 and accelerate toward 367.0 million USD by 2032. These figures represent more than operational scale; they signal a structural transformation in how enterprises allocate labor, respond to demand fluctuations, and manage the human capital dimension of service delivery. This steady expansion reflects deepening enterprise reliance on intelligent workforce tools, as well as the maturation of deployment models, vendor ecosystems, and compliance frameworks that together define the modern scheduling landscape.
Technology Architecture and Deployment Evolution
The evolution of deployment models has fundamentally shaped how organizations interact with employee scheduling software. Cloud-based solutions now command the largest share of the technology landscape, reflecting a decisive industry pivot toward scalable, accessible, and continuously updated platforms. Organizations are increasingly drawn to cloud architectures for their ability to streamline implementation, reduce infrastructure overhead, and support distributed workforce operations across multiple sites and time zones. At the same time, on-premises environments continue to serve a meaningful segment of the market, particularly where data sovereignty, legacy system integration, and highly controlled operational environments remain critical considerations. Beyond these core deployment paths, a broader category of solutions reflects the ongoing diversification of the market, as vendors expand the scope of offerings to include integrated time tracking, mobile self-service, and complementary workforce management capabilities.
Alongside deployment evolution, the functional architecture of scheduling platforms is growing more sophisticated. Modern systems are increasingly expected to support real-time coverage adjustments, AI-driven demand forecasting, automated compliance checks, and seamless linkage with payroll and core human capital management processes. This functional convergence is narrowing the gap between scheduling and broader workforce strategy, enabling organizations to treat employee scheduling not as a standalone administrative task, but as a central point of operational control. As a result, procurement and IT leaders are evaluating platforms through a more holistic lens, weighing long-term interoperability, extensibility, and integration potential alongside immediate scheduling performance.
Industry Applications and Operational Impact
The practical value of employee scheduling software is most visible in its application across different organizational scales. Small businesses rely on scheduling technology to bring structure to limited administrative capacity, allowing lean teams to manage shifts, reduce forgotten coverage gaps, and maintain operational consistency without expanding overhead. Mid-size enterprises, often operating across multiple locations or service lines, use scheduling software to introduce visibility, standardize processes, and support growth without proportionally increasing managerial load. Large enterprises apply these tools to coordinate complex labor pools, optimize costly overtime exposure, and align staffing decisions with sophisticated demand forecasts and cross-functional operational priorities.
What unites these diverse application environments is the growing recognition that scheduling performance directly affects labor economics and service quality. Improved scheduling alignment is consistently associated with stronger shift coverage, lower overtime exposure, and more effective alignment between labor supply and operational demand. In fast-paced, shift-based environments, this can translate into measurable reductions in unnecessary labor spend while improving reliability for both employees and customers. At the same time, mobile-first access and employee self-service capabilities empower individuals to participate more actively in schedule management, which can strengthen engagement and reduce administrative friction.
Employee Scheduling Software Market
The operational upside extends to compliance as well. Automated enforcement of meal breaks, rest periods, overtime boundaries, and union or state-specific rules helps organizations reduce legal exposure and operational risk. With labor regulations continuing to evolve, platforms that embed policy guidance and compliance monitoring are increasingly viewed as strategic safeguards rather than optional add-ons. In this context, the scheduling software decision is becoming inseparable from enterprise risk management and operational continuity planning.
Regulatory Landscape and Operational Dynamics
Regulatory pressure remains one of the most powerful external forces shaping the employee scheduling software market. As labor rules, scheduling transparency requirements, and compliance expectations continue to shift across regions and industries, organizations face rising complexity in maintaining adherence without sacrificing operational flexibility. The industry response has been to move compliance from manual oversight to engineered automation. Platforms are increasingly designed to translate regulatory requirements into built-in controls, alerting mechanisms, and policy enforcement logic that reduce the burden on HR, payroll, and operations teams.
Data privacy considerations are equally integral to this dynamic. Enterprise-grade cloud scheduling platforms continue to align with established security and privacy standards, ensuring that workforce data is handled with the rigor required for regulated environments and cross-border operations. For organizations operating in Europe or other privacy-sensitive markets, these safeguards are not optional enhancements but baseline expectations that influence procurement decisions and long-term vendor trust.
Beyond formal regulation, broader operational dynamics are influencing market direction. The integration of workforce expertise, policy guidance, and documentation support into platform ecosystems reflects a maturing market in which vendors are expected to help customers navigate change rather than simply provide tools. This shift is especially relevant in environments where labor laws, union rules, and state-specific mandates create recurring compliance uncertainty. Organizations that select platforms with strong compliance orientation are often better equipped to absorb regulatory change without operational disruption.
Competitive Landscape and Strategic Positioning
The competitive field in employee scheduling software is characterized by a mix of established workforce management incumbents, specialized scheduling vendors, and broader HCM platforms extending into scheduling functionality. Market concentration remains relatively distributed, with the top three players holding approximately 24.6 percent and the top five reaching about 26.2 percent of the overall market, indicating substantial room for differentiation and continued competitive churn. This fragmentation is a strategic advantage for buyers, as it supports a wide spectrum of solution philosophies ranging from enterprise-scale workforce orchestration to industry-specific scheduling tools and SMB-focused mobile platforms.
Leading participants illustrate the diversity of approaches shaping the market. ADP delivers a comprehensive workforce management platform that integrates employee scheduling, time tracking, shift optimization, and compliance support for hourly and frontline workers. UKG brings enterprise-grade scheduling strength through platforms such as UKG Pro and Kronos Workforce Central, with AI forecasting, real-time coverage planning, labor cost optimization, and multi-site shift management at the core of its value proposition. Ceridian Dayforce offers a unified platform connecting scheduling, shift assignment, workforce analytics, and automated compliance for global enterprises. Rippling positions scheduling within an integrated HR and workforce management suite, linking AI demand forecasting and shift planning with payroll and organizational growth.
Specialized players further broaden the competitive canvas. Deputy focuses on shift-based industries with scheduling, time tracking, AI labor forecasting, mobile access, and compliance automation. Connecteam emphasizes app-based scheduling, shift swapping, time tracking, and team communication for small and medium businesses. Homebase combines scheduling and payroll with shift templates, mobile clock-in, labor cost tracking, and compliance alerts. Paychex Flex targets mid-market organizations with scheduling, time and attendance, and integrated payroll. Paycor contributes intelligent HCM capabilities with scheduling, labor cost visibility dashboards, and integrated shift management. When I Work centers on employee self-scheduling, shift management, and real-time reporting. Workday extends advanced scheduling, demand forecasting, and compliance-driven workforce planning within a large enterprise HCM context. TCP Software, through Humanity Schedule and TimeClock Plus, provides dynamic scheduling with automated forecasting, mobile management, and labor optimization. Shiftboard serves mission-critical industries with fatigue management, contingent labor tools, and labor cost reduction features.
Recent industry activity reinforces the pace of innovation. In March 2026, UKG launched 15 Workforce Management APIs designed to support seamless integration with employee scheduling and time-tracking platforms. Initiatives like this highlight a broader market trend in which interoperability is increasingly treated as a competitive differentiator, enabling organizations to build more connected workforce ecosystems rather than isolated point solutions.
Report Scope and Decision-Ready Intelligence
The Employee Scheduling Software Market report is designed as a practical decision-support instrument rather than a high-level survey. It frames the market through a structured methodology that combines historical analysis with forward-looking forecasting, enabling leadership teams to ground strategic choices in evidence rather than assumption. The report traces market evolution across the 2020 to 2025 historical period and extends into a detailed 2026 to 2032 forecast window, providing continuity between past performance and future opportunity.
Beyond macro market sizing and growth outlook, the study examines how technology type, deployment model, application environment, and regional dynamics collectively shape purchasing behavior and solution effectiveness. It provides a structured competitive assessment of major vendors, profiling their capabilities, positioning, and recent strategic moves. This allows readers to compare market participants not only by scale, but by functional emphasis, integration maturity, and target customer fit.
The report also explores the operational and regulatory context that influences adoption. By integrating insight on labor cost impact, compliance automation, data privacy requirements, and integration trends, it equips stakeholders with a multi-layered view of the forces that affect implementation success and long-term platform value. For procurement teams, this means clearer evaluation criteria. For strategy leaders, it means a stronger basis for portfolio planning and vendor selection. For investors and analysts, it means a more precise understanding of where growth is concentrating and why.
Crucially, the full dataset, detailed segmentation, and proprietary company assessments are reserved for the complete report. This introduction is intended to establish analytical credibility while preserving the depth of intelligence that readers will need to act with confidence. The full study provides the range, precision, and benchmarking detail required to translate market signals into concrete investment, procurement, and operational decisions.
Conclusion: Strategic Imperatives for the 2026 Horizon
As organizations move deeper into 2026, employee scheduling software is no longer a tactical utility. It has become an essential enabler of labor efficiency, workforce agility, and regulatory resilience. The market’s projected growth path and expanding functional expectations indicate that companies which treat scheduling as a strategic capability will be better positioned to manage cost pressures, improve coverage quality, and adapt to evolving compliance demands.
For leaders evaluating technology investments, the strategic question has shifted from whether to adopt scheduling software to which platform architecture, integration model, and vendor profile best fits the organization’s scale, industry, and risk environment. The answers depend on a clear reading of market structure, vendor differentiation, and operational impact. PW Consulting’s Employee Scheduling Software Market report offers that reading in a form built for executive decision-making. We invite stakeholders to explore the full research for the complete market intelligence, segmentation precision, and competitive analysis needed to navigate the next phase of workforce optimization with confidence.
For detailed analysis of this topic, please visit the official page: Employee Scheduling Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automated Sortation Market Hits $432M in 2025, Projects 3.99% CAGR to 2032
By pmarketresearch, 2026-09-15
Navigating the Automated Sortation System Market: Strategic Intelligence for 2026 Decision-Makers
The global supply chain ecosystem is undergoing a structural transformation driven by e-commerce acceleration, labor constraints, and the imperative for operational precision. At the center of this shift lies the automated sortation system market, a critical enabler of modern distribution, parcel handling, and intralogistics optimization. For executives, investors, and operations leaders evaluating capital allocation or technology roadmaps in 2026, understanding the trajectory, competitive architecture, and regulatory forces shaping this market is no longer optional—it is foundational to resilient growth.
This introduction previews the depth and strategic utility of PW Consulting’s latest market research on automated sortation systems. Rather than offering surface-level market sizing, the report is engineered to translate macroeconomic signals, competitive maneuvers, and regulatory developments into actionable decision frameworks. Below, we outline the analytical scope, the competitive landscape it maps, and the market dynamics that will define procurement, partnership, and expansion strategies throughout the forecast horizon.
Market Trajectory and the Strategic Imperative for 2026
The automated sortation system market has demonstrated steady, compounding growth over the past half-decade, reflecting the broader digitization of logistics and the scaling of fulfillment networks. Historical revenue patterns from 2020 through 2025 reveal a market that has consistently expanded despite macroeconomic volatility, underpinned by sustained investment in warehouse automation and parcel infrastructure. This momentum carries forward into the forecast period, where the market is projected to continue its upward arc through the early 2030s.
For 2026 specifically, the market reaches a meaningful inflection point. The baseline valuation for the year signals a clear step-up from the prior year’s close, reinforcing the notion that sortation automation is transitioning from a discretionary efficiency play to a core operational requirement. Over the full forecast window extending to 2032, the market is expected to expand at a compound annual growth rate of approximately 4 percent, culminating in a substantially larger revenue base by the end of the period. This trajectory is not merely a numerical projection; it reflects the cumulative effect of throughput demands, labor cost pressures, and the integration of intelligent control systems into sortation workflows.
Importantly, the growth pattern is not uniform across all operational contexts. Different sectors and geographies are experiencing divergent adoption velocities based on infrastructure maturity, regulatory environments, and the urgency of fulfillment speed. The report disentangles these variations without reducing them to simplistic rankings, instead providing a layered view of where demand is consolidating, where whitespace exists, and how implementation complexity shapes procurement timelines.
What the Report Delivers: Analytical Depth and Operational Relevance
PW Consulting’s automated sortation system market research is structured to serve multiple stakeholder groups simultaneously—operations directors evaluating capital projects, strategy teams assessing vendor partnerships, and investors mapping sector exposure. The report integrates quantitative market architecture with qualitative competitive and regulatory analysis, ensuring that data points are always anchored to decision context.
Core Analytical Components
- Market sizing and forward projections spanning historical baselines through the full forecast horizon, with revenue expressed in nominal terms to support budgeting and scenario modeling.
- Segmentation analysis across technology types, end-use applications, and regional markets, enabling readers to isolate the subsegments most relevant to their operational footprint or investment thesis.
- Competitive positioning and firm-level profiling that maps the strategic capabilities, product architectures, and geographic reach of leading participants.
- Recent corporate developments including deployments, partnerships, and integration initiatives that signal where the market is heading in practice, not just in theory.
- Regulatory and operational dynamics covering labor impact, data privacy obligations, safety and traceability requirements, and energy efficiency mandates that increasingly shape procurement criteria.
- Concentration metrics that clarify the degree of market consolidation and the strategic implications for incumbents and entrants alike.
Each section is designed to feed directly into business planning. For example, the segmentation views allow procurement teams to benchmark their internal pipeline against broader demand patterns, while the competitive profiles help evaluate whether a shortlisted vendor’s technology portfolio aligns with projected throughput and flexibility requirements. Similarly, the regulatory and operational dynamics section translates external compliance pressures into practical risk-filtering criteria for project scoping.
Automated Sortation System Market
Competitive Landscape: Architects of the Sortation Ecosystem
The automated sortation system market is characterized by a blend of established intralogistics conglomerates, specialized sortation technology providers, and large industrial firms extending into automation platforms. Market concentration metrics indicate a moderately consolidated environment, where a relatively small group of firms commands a substantial share of industry revenue. This structure has meaningful implications for procurement leverage, integration risk, and the pace of innovation diffusion.
Firm Profiles and Strategic Positioning
Several companies define the technological and commercial contours of this market. Daifuku Co., Ltd., headquartered in Osaka, specializes in tilt-tray and linear parcel sortation systems designed for high-volume logistics and distribution centers, making it a reference point for operators prioritizing throughput stability. Vanderlande Industries B.V., based in the Netherlands, offers loop sorters, sliding shoe sorters, and automated parcel sortation solutions optimized for e-commerce fulfillment—an alignment that reflects the ongoing centrality of parcel velocity in consumer logistics. OKURA YUSOKI CO., LTD., from Tokyo, provides automated parcel sortation systems combining linear and shoe sorter technologies tailored to parcel and postal applications, while Murata Machinery, Ltd., also in Kyoto, focuses on cross-belt and linear sortation systems integrated with high-speed sorting platforms for parcel logistics.
Interroll Holding AG, headquartered in Germany, manufactures roller conveyor and modular automated sortation systems for warehouses and distribution hubs, emphasizing modularity and scalability. The KION Group AG, through its Dematic business, delivers shoe sorters and automated warehouse sortation systems as part of broader intralogistics solutions, positioning the brand at the intersection of material handling and software orchestration. TGW Group, based in Austria, provides comprehensive automated sortation and conveyor systems for parcel and general merchandise handling, supporting operators that require end-to-end line design. Honeywell International Inc., from the United States, offers sliding shoe, push-tray, and cross-belt sorters for high-throughput parcel and retail sortation, bringing a broad automation heritage to the sortation tier. BEUMER Group, in Germany, specializes in cross-belt sorters and pouch-based sortation platforms for parcel distribution, while Fives in Intralogistics, headquartered in Paris, supplies automated sortation and material handling solutions for parcel and e-commerce operations.
Worldwide Warehouse Automated Sorting System Market
Additional participants further deepen the competitive field. SSI SCHAEFER AG delivers modular automated sortation systems integrated with storage and warehouse management, reinforcing the trend toward tightly coupled automation stacks. Siemens AG provides software-driven and AI-integrated sortation platforms for smart factory and logistics applications, reflecting the growing weight of control intelligence in system selection. Mitsubishi Electric Corporation, from Tokyo, offers automated sortation systems with high-speed conveyor and sorter technologies, rounding out a competitive set that spans mechanical throughput, software integration, and sector-specific specialization.
Recent Developments Shaping the Field
Competitive positioning is not static; it is being actively reshaped by deployment activity and strategic partnerships. In early 2026, BoxLogix completed the installation of an in-line automated sortation system for a regional healthcare distribution hub, streamlining parcel receiving and routing across multiple hospitals—an example of how sortation automation is extending into regulated, multi-site distribution environments. Earlier, in February 2025, EuroSort announced a non-exclusive partnership with Körber to integrate its sorting systems with Körber’s VarioPick dynamic picking robot, aiming to enhance automated sortation precision and scalability through combined robotic and sorting workflows. In January 2026, CVS Health partnered with Tompkins Robotics and Bastian Solutions to deploy an integrated AS/RS with a tSort robotic sortation system at a fulfillment facility, illustrating how large-scale retail and pharmacy logistics are converging on sortation-plus-storage architectures.
These developments are more than announcements; they are signals of how the market is consolidating around integrated, higher-precision, and sector-aware solutions. The report places such events in context, helping readers distinguish between one-off deployments and structural shifts in how sortation systems are specified, integrated, and scaled.
Market Dynamics and Regulatory Forces redefining Procurement Criteria
Technology capability alone no longer determines sortation system success. A set of operational and regulatory dynamics is increasingly embedded into project requirements, vendor evaluations, and total cost of ownership calculations. Understanding these forces is essential for 2026 planning, because they influence not only what systems are purchased, but how they are integrated, validated, and governed over their operational life.
Labor Economics and Throughput Expectations
Automated sortation systems have driven a meaningful reduction in post-sort labor requirements through robotic and conveyor-based handling in distribution operations. This shift is reshaping facility economics: where labor availability and wage escalation once dominated site planning, throughput reliability and changeover flexibility are now equally central. For decision-makers, the implication is that sortation investments must be evaluated against a broader operational baseline that includes staffing strategy, training burden, and the ability to reallocate human labor to exception handling and value-added tasks.
Regulatory Compliance and Data Governance
The regulatory environment is adding new layers of complexity to sortation system deployment. The EU AI Act entered into force on 1 August 2024 and became fully applicable on 2 August 2026, directly regulating AI components in automated sortation systems. This matters for any operator integrating AI-driven routing, exception detection, or predictive control into sortation workflows, because compliance responsibilities now extend to the intelligence layer as well as the mechanical infrastructure.
At the same time, the integration of IoT-enabled and AI-driven sortation systems in warehouses requires ongoing compliance with GDPR for data security and traceability in parcel logistics. As sortation platforms become more connected and data-rich, information governance is no longer a back-office concern; it is part of the system architecture. In parallel, pharmaceutical and food-grade applications of automated sortation systems demand enhanced traceability and contamination-prevention standards under current industry regulations, raising the bar for materials, cleaning protocols, and validation processes in sensitive supply chains.
Sustainability and Operational Efficiency
Environmental regulations increasingly mandate energy-efficient designs in automated sortation systems to minimize operational waste and carbon footprint. This trend is pushing vendors and operators alike to consider motor efficiency, idle-state management, regenerative capabilities, and overall system utilization patterns. For 2026 procurement teams, energy performance is becoming a competitive differentiator that intersects with operating cost, regulatory readiness, and corporate sustainability commitments.
These dynamics do not operate in isolation. They converge in the evaluation criteria used to select sortation platforms, define integration scopes, and set performance benchmarks. The report maps these converging pressures so that readers can anticipate where compliance effort, integration complexity, and operating cost will matter most in their specific context.
Why 2026 Is a Decision-Critical Year
The automated sortation system market is not simply growing; it is maturing in ways that reward early, informed action. The combination of steady revenue expansion, a concentrated but pluralistic competitive field, and a regulatory landscape that increasingly touches AI, data, safety, and energy means that 2026 decisions will shape operational competitiveness for years to come.
Several themes make this a pivotal moment:
- Demand is broadening beyond traditional parcel hubs into healthcare distribution, regulated food and pharmaceutical flows, and retail fulfillment models that require higher precision and traceability.
- Integration is becoming the real product , with partnerships and multi-vendor architectures reflecting the reality that sortation rarely operates in isolation from picking, storage, and warehouse management systems.
- Compliance is now part of the technical specification , whether the concern is AI governance, data privacy, contamination control, or energy efficiency. Procurement criteria are expanding accordingly.
- Labor displacement benefits are real but context-dependent , requiring operators to plan not just for reduced post-sort headcount, but for the redesign of exception workflows and skill requirements.
In this environment, generic market awareness is insufficient. Decision-makers need segmented insight, vendor capability mapping, and a clear view of how macroeconomic growth translates into practical opportunities and constraints. That is precisely the function of the full report.
How to Use This Research for Strategic Planning
The report is designed to support multiple planning workflows. Operations leaders can use the segmentation views to align internal capital projects with broader demand patterns and to identify subsegments where adoption is accelerating. Strategy and procurement teams can use the competitive profiles and recent developments to benchmark vendor proposals, assess integration risk, and identify partnership opportunities that extend system capability. Investors and market analysts can use the concentration metrics, growth trajectory, and regulatory overlays to frame sector exposure and evaluate the durability of competitive advantages.
Crucially, the report does not stop at high-level numbers. It connects market sizing to the operational realities that determine whether a sortation investment delivers intended returns: throughput stability, changeover flexibility, compliance readiness, integration complexity, and energy performance. By embedding these considerations within the analytical framework, the research helps readers move from market awareness to decision confidence.
Accessing the Full Intelligence
The overview above highlights the structure, scope, and strategic relevance of the research, but the full value lies in the detailed segmentation data, firm-level profiles, regulatory impact analysis, and scenario-ready projections that support precise planning. To explore the complete market architecture, including the subsegment dynamics and competitive detail necessary for 2026 decision-making, readers are encouraged to access the full report through the source webpage.
In a market defined by compounding growth, integration complexity, and rising compliance expectations, the organizations that act with the most complete intelligence will be best positioned to convert sortation investment into durable operational advantage. This report is built to provide that intelligence—precisely, contextually, and with direct relevance to the choices facing leaders in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Automated Sortation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Textile Chemicals Market to Reach $41.34 Billion by 2032 at 4.8% CAGR
By pmarketresearch, 2026-09-15
Navigating the Textile Chemicals Market: Strategic Intelligence for 2026 and Beyond
The global textile chemicals market stands at a critical inflection point. As supply chains recalibrate, regulatory frameworks tighten, and sustainability imperatives reshape procurement priorities, chemical suppliers, formulators, and textile manufacturers must look beyond historical benchmarks to anticipate the forces that will define competitive advantage through 2032. Our newly released Textile Chemicals Market research delivers the analytical architecture required to navigate this complexity with precision.
Built on a rigorous six-year historical foundation spanning 2020 through 2025 and projecting forward across a seven-year forecast horizon, this study translates macro-level trajectory data into actionable decision frameworks. The market reached an estimated USD 30.0 billion in 2025, building on a steady climb from USD 21.5 billion in 2020. Forward projections indicate the sector will expand to USD 31.4 billion in 2026 and continue its ascent toward USD 41.34 billion by 2032, underpinned by a compound annual growth rate of 4.8 percent. These figures are not merely retrospective confirmations; they represent the baseline against which capital allocation, capacity planning, and product portfolio strategy must be calibrated in the current fiscal year.
For executives evaluating market entry, expansion, or repositioning, understanding the velocity and distribution of this growth is indispensable. The report dissects the trajectory across multiple analytical dimensions, enabling leadership teams to isolate high-probability opportunities while mitigating exposure to structural headwinds. This introduction outlines the strategic architecture of the study, the competitive and regulatory forces reshaping the landscape, and the practical intelligence embedded within each chapter.
Strategic Value for 2026 Decision-Making
The 2026 operating environment demands more than aggregated market data. Procurement leaders, R&D directors, and corporate strategists require segmentation that aligns with actual purchasing behavior, formulation economics, and regional supply dynamics. Our research is structured to answer the questions that directly influence quarterly planning and multi-year investment thesis:
- Which product categories are capturing disproportionate value share, and what formulation or performance attributes are driving that preference?
- How are end-use sectors reallocating chemical procurement budgets as apparel demand stabilizes, home textiles evolve, and technical textiles gain industrial traction?
- Where are regional demand centers converging with manufacturing capability, and which logistics or compliance constraints reshape margin profiles?
- What concentration patterns exist among incumbent suppliers, and how does that influence negotiation leverage, supply continuity, and partnership strategy?
The study maps these dimensions without diluting them into superficial aggregates. Instead, it provides a layered view that allows teams to drill from high-level trajectory into category-level dynamics, application-driven procurement patterns, and regional variation in demand intensity. The forecast period through 2032 is particularly valuable for capacity expansion decisions, M&A screening, and long-range product development roadmaps, because it connects near-term momentum with the structural shifts that will compound over the next seven years.
By anchoring 2026 planning in a market that has already demonstrated resilience through post-pandemic normalization and is now encountering a new wave of regulatory and sustainability requirements, organizations can move from reactive adjustments to proactive positioning. The report is designed to be a working document for strategy sessions, not a static reference, with analytical constructs that translate directly into investment memos, procurement guidelines, and commercial planning assumptions.
Competitive Landscape and Key Players
The competitive architecture of the textile chemicals sector reflects a blend of global scale players, regional specialists, and integrated distributors, each pursuing distinct value propositions across the processing chain. Concentration analysis within the study indicates that the top three players command approximately 45 percent of market revenue, while the top five extend that share to roughly 55 percent. This level of consolidation signals meaningful competitive gravity around established formulations, technical service capabilities, and global distribution networks, while still leaving substantial space for regional specialists and niche innovators.
Several organizations define the current competitive frontier. Archroma, headquartered in Switzerland, operates as a global leader in sustainable dyes, colorants, and performance chemicals engineered specifically for dyeing, finishing, and printing applications. Its portfolio orientation toward sustainability-aligned formulations positions it at the intersection of regulatory compliance and premium product strategy. Sarex Chemicals, based in India, specializes in textile auxiliaries and pre-treatment chemicals, alongside solutions for dyeing and finishing processes, reflecting the depth of capability present among regional manufacturers that serve high-volume processing ecosystems. Fineotex Chemical, also India-based, manufactures specialty textile chemicals spanning pre-treatment, dyeing, printing, and finishing across the full value chain, illustrating the vertically broad approach some suppliers adopt to capture share at multiple processing stages.
Azelis, headquartered in Belgium, functions as a distributor and integrated supplier of dyes, bleaching agents, pretreatment chemicals, and finishing solutions, underscoring the continued importance of distribution-centric models that combine technical support with supply reliability. Huntsman Textile Effects, operating from Switzerland and Germany, provides functional dyes, textile finishing chemicals, and performance solutions, aligning its offering with applications that require enhanced fabric functionality and process efficiency. NICCA Chemical, Japan's leading developer and manufacturer of scouring, dyeing, and finishing chemicals, represents the technical precision and process expertise that characterize advanced Asian formulation capability. CHT Group, based in Germany, specializes in textile chemicals, auxiliaries, and dyeing solutions for printing, finishing, and processing, reinforcing Europe's enduring strength in specialty chemical engineering and application know-how.
These companies are not analyzed in isolation. The report places them within a competitive framework that considers portfolio breadth, regional footprint, sustainability alignment, technical service depth, and pricing architecture. By understanding where each player derives advantage, organizations can better anticipate supplier behavior, evaluate partnership candidates, and identify white spaces where new entrants or reformulated offerings could capture meaningful share.
Regulatory Acceleration and Industry Dynamics
No analysis of the textile chemicals market in 2026 is complete without confronting the accelerating pace of regulatory and standards-based change. Compliance is no longer a defensive cost center; it is a determinant of market access, brand partnership eligibility, and downstream customer trust. Recent developments make this reality unmistakable.
The regulatory environment has intensified across multiple fronts. OEKO-TEX STANDARD 100 reduced the Bisphenol A limit from 100 mg/kg to 10 mg/kg effective April 2025, following the WHO classification of BPA as an endocrine disruptor. Subsequent updates as of April 2026 added PFOS-related substances at 1 mg/kg and introduced two new SVHC substances, Decamethyltetrasiloxane and siloxanes, at 1000 mg/kg. In October 2025, OEKO-TEX also added new SVHC substances with 1000 mg/kg limit values for STANDARD 100, while setting the PFOS limit at 25 µg/kg for STANDARD 100 and ORGANIC COTTON. These revisions compress the formulation tolerance window and raise the cost of non-compliance, compelling suppliers and manufacturers to revalidate inputs and adjust recipes.
Textile Chemicals Market
France introduced a parallel constraint through Law 2025-188 and Decree 2025-1376, which prohibit PFAS-containing textiles, clothing, footwear, and waterproofing agents effective January 2026, with limited exemptions for certain recycled or industrial applications. This national measure signals a broader European appetite for targeted chemical restrictions and creates direct implications for finishing agents, waterproofing chemistries, and performance additives used in apparel and home textile applications.
On the standards side, GOTS Version 8.0, released in March 2026, introduces new chemical input approval criteria, enhanced accountability provisions, and mandatory due diligence for organic textile chemicals, effective March 2027. The update mandates toxicity hazard requirements and on-site audits for all textile chemicals used in organic fibre production. For suppliers serving certified organic supply chains, the compliance burden and documentation rigor increase materially, and early alignment becomes a competitive differentiator rather than a last-minute remediation exercise.
The ZDHC Roadmap to Zero Programme also advanced with its 2025 microfibre research and ClearStream wastewater guidelines for textiles and leather, reinforcing zero-discharge targets and pushing the industry toward more rigorous effluent management. These guidelines interact directly with chemical selection, process design, and wastewater treatment strategies, making chemical performance in aqueous systems a strategic consideration rather than a purely technical parameter.
Industry events reflect the same momentum. Techtextil 2026 launched a dedicated Textile Chemicals & Dyes product segment featuring more than 30 exhibitors presenting dyes, auxiliaries, functional finishes, and polymer technologies. Early booking for the segment, announced in February 2026, confirmed participation from major players such as Archroma, CHT, and Rudolf, signaling strong industry appetite for concentrated knowledge exchange. In parallel, the 52nd DyeChem Asia International Expo is scheduled for 3–5 June 2026 in Thailand, positioning itself as Asia's platform for textile chemicals and auxiliaries and underscoring the region's centrality to supply, innovation, and cost dynamics.
Report Scope and Actionable Insights
To translate this landscape into usable intelligence, the report is organized around operational decision points rather than abstract market description. It starts with a comprehensive market sizing and forecast architecture that connects historical performance with forward projections, providing a consistent baseline for scenario planning. From there, the analysis segments the market by type, application, and region, enabling readers to identify where growth is concentrated and where structural constraints may temper expansion.
The type perspective examines categories such as colorants and auxiliaries, coating and sizing agents, finishing agents, and other specialized inputs, clarifying which functional roles are capturing demand and why. The application perspective maps consumption across apparel, home textiles, technical textiles, and other uses, linking chemical demand to end-market behavior, fabric engineering requirements, and processing intensity. The regional perspective evaluates demand distribution and supply interplay across major geographic zones, highlighting where manufacturing concentration, import reliance, regulatory cadence, and logistics economics shape market outcomes.
Beyond segmentation, the study integrates competitive profiling, regulatory mapping, and value chain dynamics into a coherent narrative. Readers gain visibility into concentration patterns, supplier positioning, and the strategic implications of recent standards revisions and trade-show momentum. The report also examines how sustainability requirements, wastewater expectations, and restricted-substance lists are reshaping formulation choices, procurement criteria, and supplier qualification processes. This integrated view is intended to support cross-functional teams—from R&D and procurement to sales and corporate development—in aligning their assumptions and priorities.
Why This Study Matters Now
The textile chemicals market is being reshaped by forces that reward early clarity and penalize delayed response. Regulatory thresholds are tightening, standards bodies are increasing audit and due-diligence requirements, and major trade platforms are consolidating chemical-focused programming, all of which indicate that the information environment is becoming more structured and more consequential. At the same time, the macro trajectory points to sustained expansion, with the market projected to advance from USD 31.4 billion in 2026 to USD 41.34 billion by 2032. Sustained growth in a tightening compliance environment creates a paradox: opportunity expands, but the pathway to capturing it narrows for organizations that lack precise intelligence.
This report is designed to resolve that tension. It provides the segmentation, competitive context, regulatory mapping, and forecast discipline required to make 2026 decisions with confidence and to extend those decisions into a defensible multi-year strategy. For organizations evaluating supplier partnerships, formulating product roadmaps, planning capacity, or screening market-entry opportunities, the study offers a structured foundation for informed action.
Textile Dyes Market
The full analysis, including detailed segmentation breakdowns, competitive profiles, regulatory timelines, and forward-looking scenario constructs, is available through our complete Textile Chemicals Market research. We invite strategy, procurement, and commercial teams to access the full report and use its architecture to sharpen their 2026 planning and position their organizations for the growth trajectory ahead.
For detailed analysis of this topic, please visit the official page: Textile Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polymer Capacitor Market Hits $215M in 2025, Forecasts 8.2% CAGR to 2032
By pmarketresearch, 2026-09-15
Navigating the Polymer Capacitor Market: Strategic Intelligence for 2026 Decision-Makers
Executive Overview
The polymer capacitor industry stands at a critical inflection point as we move further into the mid-2020s. From a base year perspective of 2025, the market has demonstrated remarkable resilience and steady expansion, reaching a valuation of approximately 215.0 million USD. Looking ahead, our comprehensive forecast period spanning 2026 through 2032 projects the sector will continue its upward trajectory, with a compound annual growth rate of 8.2 percent. By the end of the forecast window in 2032, the total market revenue is expected to approach 344.8 million USD. These figures represent more than just numerical progression; they reflect fundamental shifts in how electronic systems are designed, manufactured, and deployed across global value chains.
For strategic leaders operating within electronics manufacturing, procurement, and supply chain management, understanding the polymer capacitor landscape has transitioned from optional due diligence to essential business intelligence. The convergence of electrification trends, miniaturization demands, and reliability requirements across industrial and automotive sectors creates both unprecedented opportunities and complex competitive challenges. This market intelligence publication provides the analytical framework necessary to navigate these dynamics with confidence.
Polymer Capacitor Market
Market Growth Trajectory and Structural Drivers
The historical data from 2020 through 2025 reveals a consistent pattern of expansion that establishes a robust foundation for future growth projections. The 8.2 percent CAGR anticipated across the 2026 to 2032 forecast period indicates sustained momentum rather than temporary surges. Several macro-level forces converge to support this trajectory. Consumer electronics continue to drive significant volume, with the segment maintaining its position as the dominant application category throughout the historical period and into the forecast horizon. The automotive sector, while representing a smaller proportion of total revenue, exhibits distinctive growth characteristics tied directly to electrification initiatives and advanced driver assistance systems.
Within the product architecture landscape, polymer tantalum electrolytic capacitors command substantial market share, reflecting their established role in high-reliability applications. Polymer aluminum electrolytic variants constitute a meaningful secondary segment, while diverse other configurations round out the product ecosystem. This structural composition matters significantly for procurement strategies, as different capacitor families serve distinct performance requirements and face varying supply chain pressures. The market concentration metrics, with the top three players holding approximately 24.6 percent and the top five commanding 26.2 percent, suggest an environment where competitive positioning requires nuanced differentiation rather than pure volume dominance.
Competitive Landscape and Key Player Analysis
The polymer capacitor market features a diverse array of established manufacturers, each pursuing distinct strategic positioning within the value chain. KYOCERA AVX Components Corporation, headquartered in Fountain Inn, South Carolina, maintains a specialized focus on conductive polymer solid electrolytic capacitors, with particular emphasis on TCO and TCQ automotive series alongside high-reliability hermetically sealed polymers and COTS+ military-grade tantalum polymer lines. Panasonic Industry Co., Ltd., based in Kadoma, Osaka, Japan, offers a comprehensive portfolio spanning conductive polymer aluminum electrolytic SP-Cap solutions, tantalum solid POSCAP products, aluminum solid OS-CON capacitors, and hybrid aluminum electrolytic configurations.
Murata Manufacturing Co., Ltd. from Nagaokakyo-shi, Kyoto, concentrates on conductive polymer aluminum electrolytic and solid capacitors tailored for automotive, industrial, and high-reliability applications. Nippon Chemi-Con Corporation in Tokyo brings forward polymer capacitor offerings including PXG high-voltage series, PXL liquid immersion cooling series, and hybrid models. Nichicon Corporation, also headquartered in Kyoto, emphasizes conductive polymer hybrid aluminum electrolytic and solid capacitors engineered for high-temperature operational environments. Rubycon Corporation provides conductive polymer aluminum electrolytic capacitors serving both general and automotive use cases.
Vishay Intertechnology, Inc., operating from Malvern, Pennsylvania, delivers polymer tantalum and aluminum solid electrolytic capacitors across industrial, automotive, and aerospace segments. Lelon Electronics Corp. in Hsinchu, Taiwan, focuses on conductive polymer aluminum electrolytic capacitors. Wurth Elektronik GmbH & Co. KG, based in Waldenburg, Germany, supplies aluminum polymer electrolytic capacitors and radial series. ROHM Co., Ltd. from Kyoto contributes polymer tantalum and aluminum solid electrolytic capacitor solutions with integrated business assets. This competitive ecosystem requires careful monitoring, as each manufacturer pursues distinct product development roadmaps and regional expansion strategies that directly influence supply availability and pricing dynamics.
Recent Developments Shaping Industry Direction
The competitive landscape continues to evolve through targeted product launches and technological advancements that redefine performance benchmarks. In December 2025, Panasonic Industry Co., Ltd. initiated commercial production of 50TQT33M and 63TQT22M conductive polymer tantalum solid capacitors featuring an industry-leading 3 millimeter profile optimized for USB Type-C power delivery applications. This development signals the industry trend toward extreme miniaturization without compromising electrical performance.
During the same period, TAIYO YUDEN Co., Ltd. commercialized its HVX and HTX series conductive polymer hybrid aluminum electrolytic capacitors, engineered with higher rated ripple current capacity and reduced profile dimensions specifically targeting automotive ADAS and power steering applications. Earlier in August 2025, Nichicon Austria unveiled automotive-rated ADN series conductive polymer hybrid aluminum electrolytic capacitors distributed across EMEA channels, while in May 2025, Nichicon Corporation introduced the GXC series highly heat-resistant conductive polymer hybrid aluminum electrolytic capacitors achieving 4000 hours of operational endurance at 135 degrees Celsius. These product releases collectively illustrate the industry's accelerating focus on automotive-grade reliability, thermal resilience, and form factor optimization.
Supply Chain Dynamics and Operational Considerations
Effective strategic planning in the polymer capacitor sector requires acute awareness of operational realities that directly impact procurement timelines and cost structures. As of October 2025, the average capacitor lead time across all technologies stands at 19 weeks, a metric that demands proactive inventory management and supply relationship cultivation. Automotive applications face particularly stringent qualification requirements, with AEC-Q200 certification becoming mandatory for polymer capacitors deployed in electric vehicle power systems. This regulatory framework ensures reliability but introduces additional validation cycles that affect time-to-market for new product introductions.
Industrial-grade polymer products now frequently benchmark against new moisture-resistance testing standards specifying 85 degrees Celsius and 85 percent relative humidity conditions sustained for 1000 hours. These performance thresholds reflect the increasing environmental demands placed on electronic components in diverse deployment scenarios. Material cost pressures have also reshaped pricing landscapes, with capacitor manufacturers implementing price increases on tantalum capacitors effective June 1, 2024, citing rising material costs. Understanding these cost drivers and their downstream implications remains essential for budget forecasting and supplier negotiation strategies.
Strategic Value of Comprehensive Market Research
A thorough market intelligence publication provides more than aggregated data points. It delivers the analytical architecture necessary to make informed decisions about market entry, capacity allocation, partnership development, and competitive positioning. The report under discussion offers detailed segmentation analysis that illuminates growth concentrations across product categories, application verticals, and geographic territories. By examining historical performance patterns alongside forward-looking projections, organizations can identify momentum shifts before they become apparent in broader industry commentary.
The competitive profiling elements enable procurement teams and strategic planners to evaluate supplier capabilities, technology roadmaps, and regional presence with granular precision. When combined with the regulatory and standards analysis, this intelligence supports compliance planning and qualification strategy development. The inclusion of recent product launch tracking and lead time monitoring provides real-time context that static annual reports often miss, allowing decision-makers to adjust sourcing strategies in near-real-time as market conditions evolve.
Organizations that leverage this level of market intelligence position themselves to anticipate rather than react. Whether the objective involves securing reliable supply for automotive programs, identifying high-growth application segments for product development, or understanding competitor movements to refine pricing strategies, the analytical foundation provided by comprehensive research serves as a critical strategic asset.
Conductive Polymer Aluminum Solid Capacitors Market
Conclusion: Positioning for Sustained Growth
The polymer capacitor market presents a compelling growth narrative supported by robust historical performance, favorable demographic and technological tailwinds, and an evolving competitive landscape that rewards differentiation and reliability. With the market projected to approach 344.8 million USD by 2032 and maintain an 8.2 percent compound annual growth rate throughout the forecast period, the sector offers meaningful expansion potential for players who approach it with informed strategic clarity. The convergence of automotive electrification, consumer electronics miniaturization, and industrial reliability demands creates a multi-dimensional growth environment where understanding segment-specific dynamics becomes a decisive competitive advantage.
Access to complete market intelligence, including detailed regional performance metrics, application-specific revenue breakdowns, and granular competitor benchmarking, enables organizations to construct strategies grounded in evidence rather than assumption. The insights embedded in our full publication provide the depth and precision necessary to navigate this dynamic market with confidence. We invite strategic decision-makers and industry leaders to explore the complete research findings, where the full analytical framework, comprehensive data tables, and actionable strategic recommendations await to inform your next phase of growth planning.
For detailed analysis of this topic, please visit the official page: Polymer Capacitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com