

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: IC Substrate Market Hits $10B in 2025, Projected 6.63% CAGR Through 2032

Strategic Horizons in the IC Substrate Market: A 2026 Executive Brief
The integrated circuit (IC) substrate market stands at a critical inflection point as 2026 unfolds. Driven by the insatiable demand for artificial intelligence (AI) computational power, the proliferation of high-performance computing (HPC), and the electrification of automotive platforms, the industry is experiencing a structural shift in both volume and value. For executive leadership and strategic planners, understanding the trajectory of this market is not merely an academic exercise but a prerequisite for capital allocation, supply chain resilience, and long-term competitive positioning.
PW Consulting's latest market research report, "IC-Substrate Market 2026-2032," offers a comprehensive analytical framework designed to navigate this complex landscape. This article serves as a strategic preview of the report's findings, highlighting the macro-economic trends, competitive dynamics, and operational imperatives that will define the industry over the next seven years. While we outline the broad strokes of the market evolution here, the full intelligence required for precise decision-making lies within the detailed data tables, segment-specific forecasts, and proprietary competitive matrices available in the complete study.
Market Trajectory and Growth Dynamics
The historical resilience of the IC substrate sector provides a strong foundation for future growth projections. Drawing on historical data spanning 2020 through 2025, the market has demonstrated a consistent upward trajectory despite global supply chain disruptions and geopolitical headwinds. The consolidated revenue figures for the recent past reflect steady expansion, culminating in a base year valuation for 2025 that underscores the sector's maturity and integral role in the electronics ecosystem.
Looking forward, the forecast period from 2026 to 2032 indicates a sustained growth momentum. The analysis projects a compound annual growth rate (CAGR) of 6.63 percent USD over this horizon. This growth is not uniform; it is heavily skewed by technological advancements and specific application drivers. The market size is expected to expand significantly by the end of the forecast period, reaching new valuation highs in 2032. Such growth rates suggest that IC substrates will remain a critical bottleneck and opportunity zone for downstream electronics manufacturers.
Technology Segments and Application Drivers
The market is segmented by technology type and end-use application, each presenting distinct risk and reward profiles. In terms of substrate types, the landscape is dominated by advanced packaging solutions required for high-density interconnects. Key categories include Flip-Chip Ball Grid Array (FC-BGA), Flip-Chip Chip Scale Package (FC-CSP), and other specialized substrate types. The shift toward higher performance computing necessitates substrates that can handle greater power densities and signal speeds, favoring advanced variants within these categories.
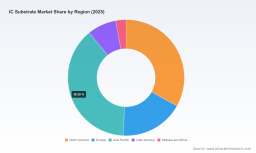
On the application side, the demand signal is led by the Mobile and Consumer electronics sector, which continues to drive volume. However, the quality and value growth is increasingly derived from the Automotive and Transportation sector, as well as the IT and Telecom industry. The emergence of AI servers, autonomous driving systems, and advanced telecommunications infrastructure is reshaping the demand mix, placing premium substrates at the center of supply chain strategy. Our report dissects these segments to reveal where margin expansion is most viable, though specific volume splits and regional contributions are detailed exclusively in the full dataset to maintain competitive confidentiality.
Competitive Landscape and Strategic Consolidation
The IC substrate market is characterized by a moderate to high level of concentration, with top players commanding a significant share of global revenue. Our analysis indicates a CR3 of approximately 54 percent and a CR5 of 60 percent, highlighting the dominance of entrenched incumbents who possess the technical capability and capital depth to invest in next-generation manufacturing. This concentration suggests that barriers to entry remain high, particularly for technologies involving Advanced Build-up Film (ABF) and glass-core substrates.
Several key companies define the current competitive arena. Firms such as Ibiden Co., Ltd., Unimicron Technology Corp., and AT&S Austria Technologie & Systemtechnik AG are at the forefront of innovation, particularly in high-performance applications. These players are not merely competing on price but are engaging in a race for technological superiority and capacity leadership. Regional players in Japan, Taiwan, South Korea, and Austria are expanding their footprints, often supported by government incentives aimed at securing semiconductor supply chains.
Samsung Electro-Mechanics and LG Innotek represent significant competitive forces from South Korea, leveraging vertical integration and strong domestic demand. Meanwhile, companies like Kinsus Interconnect Technology Corp., Shinko Electric Industries Co., Ltd., and Nan Ya PCB Corporation are positioning themselves to capture specific niches within the AI and server packaging value chain. Kyocera Corporation also remains a notable entity, focusing on specialized laminate technologies. The interplay between these entities involves capacity expansions, pricing strategies, and technological partnerships that our report analyzes in depth.
Operational Dynamics: Capacity, Materials, and Regulation
The operational environment for IC substrate manufacturers in 2026 is defined by a tension between surging demand and supply chain constraints. A primary theme in our research is the massive capital expenditure programs undertaken by leading firms. For instance, recent announcements highlight capital investments exceeding hundreds of billions of yen and trillion-won ranges dedicated to expanding high-performance IC package substrate capacity. These investments are targeted specifically at plants capable of serving AI server demands, with mass production timelines ramping up from fiscal 2027 onwards.
Technology advancement is another critical vector. The industry is moving beyond traditional organic substrates toward glass-core and multifunctional core technologies. Recent developments indicate that some leaders have advanced glass-core substrate technology from R&D to industrial deployment, targeting AI, HPC, and even photonics applications. This technological leap is essential for overcoming signal loss and thermal challenges in next-generation packages.
However, capacity expansion is complicated by raw material volatilities. The market faces persistent shortages in critical inputs such as fiberglass and base resins. Supply chain intelligence indicates that key material suppliers have adjusted pricing significantly, with some substrate film prices increasing by over 30 percent due to base resin supply constraints. This inflationary pressure on raw materials is forcing manufacturers to reconsider pricing strategies. In response, leading substrate providers have begun raising prices for premium ABF substrates to offset costs and manage capacity constraints, signaling a shift in the cost structure for downstream customers.
Regulatory support remains a potent accelerant for market growth in key regions. Government initiatives aimed at bolstering domestic semiconductor manufacturing are providing substantial financial backing. For example, funding mechanisms totaling hundreds of millions of USD have enabled specific capacity projects in North America, targeting significant panel production volumes by late 2027. Similarly, European initiatives have awarded substantial grants for plant expansions in Austria, adding tens of thousands of FC-BGA panels to monthly production capacity starting in 2027. These geopolitical interventions are reshaping the global supply map, reducing reliance on single-region sourcing and encouraging localized production hubs.
Strategic Imperatives for 2026 Decision Makers
For industry participants, the insights contained in this study translate into several actionable strategic imperatives. First, supply chain diversification is no longer optional. With material shortages and geopolitical risks influencing the flow of critical substrates, organizations must develop multi-source strategies. Second, technology roadmapping must align with the shift toward glass-core and high-density interconnect solutions to avoid obsolescence in AI and HPC segments.
Third, capacity planning requires a nuanced understanding of lead times and allocation risks. As key players prioritize high-margin AI server contracts, availability for other segments may become constrained, necessitating earlier locking-in of volumes. Finally, pricing negotiations must account for the structural increase in raw material costs and the premium nature of advanced substrate technologies.
The detailed segmentation data, company profiles, and granular forecast models within our full report provide the specific intelligence needed to validate these strategies. Access to the complete analysis allows clients to benchmark their internal projections against market-wide data, identify underserved niches, and anticipate the moves of key competitors with greater precision.
Conclusion
The IC-Substrate Market from 2026 to 2032 presents a landscape of robust growth tempered by complex operational challenges. The convergence of AI demand, technological innovation in substrate materials, and strategic government intervention creates a dynamic environment where informed decision-making is a key differentiator. The macro trends point to a market expanding significantly in value, driven by high-performance applications that demand superior interconnect solutions.
IC Substrate Market
PW Consulting's comprehensive study offers the depth and breadth required to navigate this terrain. By leveraging the detailed forecasts, competitive profiles, and risk assessments outlined in the full report, stakeholders can secure a decisive advantage in procurement, investment, and strategic planning. We invite industry leaders to access the complete research document to unlock the full spectrum of data and insights necessary for thriving in this evolving market.
IC-Substrate Market
For detailed analysis of this topic, please visit the official page: IC-Substrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com