

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Polymer Capacitor Market Hits $215M in 2025, Forecasts 8.2% CAGR to 2032

Navigating the Polymer Capacitor Market: Strategic Intelligence for 2026 Decision-Makers
Executive Overview
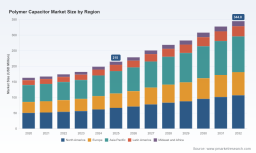
The polymer capacitor industry stands at a critical inflection point as we move further into the mid-2020s. From a base year perspective of 2025, the market has demonstrated remarkable resilience and steady expansion, reaching a valuation of approximately 215.0 million USD. Looking ahead, our comprehensive forecast period spanning 2026 through 2032 projects the sector will continue its upward trajectory, with a compound annual growth rate of 8.2 percent. By the end of the forecast window in 2032, the total market revenue is expected to approach 344.8 million USD. These figures represent more than just numerical progression; they reflect fundamental shifts in how electronic systems are designed, manufactured, and deployed across global value chains.
For strategic leaders operating within electronics manufacturing, procurement, and supply chain management, understanding the polymer capacitor landscape has transitioned from optional due diligence to essential business intelligence. The convergence of electrification trends, miniaturization demands, and reliability requirements across industrial and automotive sectors creates both unprecedented opportunities and complex competitive challenges. This market intelligence publication provides the analytical framework necessary to navigate these dynamics with confidence.
Polymer Capacitor Market
Market Growth Trajectory and Structural Drivers
The historical data from 2020 through 2025 reveals a consistent pattern of expansion that establishes a robust foundation for future growth projections. The 8.2 percent CAGR anticipated across the 2026 to 2032 forecast period indicates sustained momentum rather than temporary surges. Several macro-level forces converge to support this trajectory. Consumer electronics continue to drive significant volume, with the segment maintaining its position as the dominant application category throughout the historical period and into the forecast horizon. The automotive sector, while representing a smaller proportion of total revenue, exhibits distinctive growth characteristics tied directly to electrification initiatives and advanced driver assistance systems.
Within the product architecture landscape, polymer tantalum electrolytic capacitors command substantial market share, reflecting their established role in high-reliability applications. Polymer aluminum electrolytic variants constitute a meaningful secondary segment, while diverse other configurations round out the product ecosystem. This structural composition matters significantly for procurement strategies, as different capacitor families serve distinct performance requirements and face varying supply chain pressures. The market concentration metrics, with the top three players holding approximately 24.6 percent and the top five commanding 26.2 percent, suggest an environment where competitive positioning requires nuanced differentiation rather than pure volume dominance.
Competitive Landscape and Key Player Analysis
The polymer capacitor market features a diverse array of established manufacturers, each pursuing distinct strategic positioning within the value chain. KYOCERA AVX Components Corporation, headquartered in Fountain Inn, South Carolina, maintains a specialized focus on conductive polymer solid electrolytic capacitors, with particular emphasis on TCO and TCQ automotive series alongside high-reliability hermetically sealed polymers and COTS+ military-grade tantalum polymer lines. Panasonic Industry Co., Ltd., based in Kadoma, Osaka, Japan, offers a comprehensive portfolio spanning conductive polymer aluminum electrolytic SP-Cap solutions, tantalum solid POSCAP products, aluminum solid OS-CON capacitors, and hybrid aluminum electrolytic configurations.
Murata Manufacturing Co., Ltd. from Nagaokakyo-shi, Kyoto, concentrates on conductive polymer aluminum electrolytic and solid capacitors tailored for automotive, industrial, and high-reliability applications. Nippon Chemi-Con Corporation in Tokyo brings forward polymer capacitor offerings including PXG high-voltage series, PXL liquid immersion cooling series, and hybrid models. Nichicon Corporation, also headquartered in Kyoto, emphasizes conductive polymer hybrid aluminum electrolytic and solid capacitors engineered for high-temperature operational environments. Rubycon Corporation provides conductive polymer aluminum electrolytic capacitors serving both general and automotive use cases.
Vishay Intertechnology, Inc., operating from Malvern, Pennsylvania, delivers polymer tantalum and aluminum solid electrolytic capacitors across industrial, automotive, and aerospace segments. Lelon Electronics Corp. in Hsinchu, Taiwan, focuses on conductive polymer aluminum electrolytic capacitors. Wurth Elektronik GmbH & Co. KG, based in Waldenburg, Germany, supplies aluminum polymer electrolytic capacitors and radial series. ROHM Co., Ltd. from Kyoto contributes polymer tantalum and aluminum solid electrolytic capacitor solutions with integrated business assets. This competitive ecosystem requires careful monitoring, as each manufacturer pursues distinct product development roadmaps and regional expansion strategies that directly influence supply availability and pricing dynamics.
Recent Developments Shaping Industry Direction
The competitive landscape continues to evolve through targeted product launches and technological advancements that redefine performance benchmarks. In December 2025, Panasonic Industry Co., Ltd. initiated commercial production of 50TQT33M and 63TQT22M conductive polymer tantalum solid capacitors featuring an industry-leading 3 millimeter profile optimized for USB Type-C power delivery applications. This development signals the industry trend toward extreme miniaturization without compromising electrical performance.
During the same period, TAIYO YUDEN Co., Ltd. commercialized its HVX and HTX series conductive polymer hybrid aluminum electrolytic capacitors, engineered with higher rated ripple current capacity and reduced profile dimensions specifically targeting automotive ADAS and power steering applications. Earlier in August 2025, Nichicon Austria unveiled automotive-rated ADN series conductive polymer hybrid aluminum electrolytic capacitors distributed across EMEA channels, while in May 2025, Nichicon Corporation introduced the GXC series highly heat-resistant conductive polymer hybrid aluminum electrolytic capacitors achieving 4000 hours of operational endurance at 135 degrees Celsius. These product releases collectively illustrate the industry's accelerating focus on automotive-grade reliability, thermal resilience, and form factor optimization.
Supply Chain Dynamics and Operational Considerations
Effective strategic planning in the polymer capacitor sector requires acute awareness of operational realities that directly impact procurement timelines and cost structures. As of October 2025, the average capacitor lead time across all technologies stands at 19 weeks, a metric that demands proactive inventory management and supply relationship cultivation. Automotive applications face particularly stringent qualification requirements, with AEC-Q200 certification becoming mandatory for polymer capacitors deployed in electric vehicle power systems. This regulatory framework ensures reliability but introduces additional validation cycles that affect time-to-market for new product introductions.
Industrial-grade polymer products now frequently benchmark against new moisture-resistance testing standards specifying 85 degrees Celsius and 85 percent relative humidity conditions sustained for 1000 hours. These performance thresholds reflect the increasing environmental demands placed on electronic components in diverse deployment scenarios. Material cost pressures have also reshaped pricing landscapes, with capacitor manufacturers implementing price increases on tantalum capacitors effective June 1, 2024, citing rising material costs. Understanding these cost drivers and their downstream implications remains essential for budget forecasting and supplier negotiation strategies.
Strategic Value of Comprehensive Market Research
A thorough market intelligence publication provides more than aggregated data points. It delivers the analytical architecture necessary to make informed decisions about market entry, capacity allocation, partnership development, and competitive positioning. The report under discussion offers detailed segmentation analysis that illuminates growth concentrations across product categories, application verticals, and geographic territories. By examining historical performance patterns alongside forward-looking projections, organizations can identify momentum shifts before they become apparent in broader industry commentary.
The competitive profiling elements enable procurement teams and strategic planners to evaluate supplier capabilities, technology roadmaps, and regional presence with granular precision. When combined with the regulatory and standards analysis, this intelligence supports compliance planning and qualification strategy development. The inclusion of recent product launch tracking and lead time monitoring provides real-time context that static annual reports often miss, allowing decision-makers to adjust sourcing strategies in near-real-time as market conditions evolve.
Organizations that leverage this level of market intelligence position themselves to anticipate rather than react. Whether the objective involves securing reliable supply for automotive programs, identifying high-growth application segments for product development, or understanding competitor movements to refine pricing strategies, the analytical foundation provided by comprehensive research serves as a critical strategic asset.
Conductive Polymer Aluminum Solid Capacitors Market
Conclusion: Positioning for Sustained Growth
The polymer capacitor market presents a compelling growth narrative supported by robust historical performance, favorable demographic and technological tailwinds, and an evolving competitive landscape that rewards differentiation and reliability. With the market projected to approach 344.8 million USD by 2032 and maintain an 8.2 percent compound annual growth rate throughout the forecast period, the sector offers meaningful expansion potential for players who approach it with informed strategic clarity. The convergence of automotive electrification, consumer electronics miniaturization, and industrial reliability demands creates a multi-dimensional growth environment where understanding segment-specific dynamics becomes a decisive competitive advantage.
Access to complete market intelligence, including detailed regional performance metrics, application-specific revenue breakdowns, and granular competitor benchmarking, enables organizations to construct strategies grounded in evidence rather than assumption. The insights embedded in our full publication provide the depth and precision necessary to navigate this dynamic market with confidence. We invite strategic decision-makers and industry leaders to explore the complete research findings, where the full analytical framework, comprehensive data tables, and actionable strategic recommendations await to inform your next phase of growth planning.
For detailed analysis of this topic, please visit the official page: Polymer Capacitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com