

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: DNS Security Software Market to Hit $310M by 2032 at 8.9% CAGR

Navigating the DNS Security Revolution: Strategic Intelligence for the 2026 Enterprise Landscape
The digital perimeter has dissolved. In an era where hybrid workforces, cloud-native architectures, and interconnected critical infrastructure define operational reality, the Domain Name System (DNS) has evolved from a simple directory service into a primary battlefield for cyber adversaries. As organizations confront increasingly sophisticated threats that exploit DNS for data exfiltration, command-and-control communication, and distributed denial-of-service campaigns, the imperative for robust DNS security software has never been more acute. This strategic briefing introduces our latest comprehensive market research on the DNS Security Software sector, a publication engineered specifically to equip executive leadership, security architects, and investment strategists with the foresight required to navigate 2026 and beyond.
Our analytical framework draws upon a multi-year trajectory of observable market expansion. Between 2020 and 2025, the global DNS security software market demonstrated consistent upward momentum, reflecting the accelerated digital transformation initiatives and the escalating frequency of DNS-layer attacks across all sectors. By the close of 2025, the market had reached a mature inflection point, with total revenues positioning the industry for a structured, high-growth forecast period spanning 2026 through 2032. Market modeling indicates a compound annual growth rate of approximately 8.9 percent across this horizon, driven by the convergence of regulatory mandates, cloud migration imperatives, and the integration of artificial intelligence into threat detection workflows. This trajectory is not merely a statistical projection; it represents a structural realignment in how enterprises deploy, fund, and operationalize domain-layer security controls.
For decision-makers evaluating technology portfolios in 2026, this research functions as a strategic compass. It dissects the forces shaping procurement priorities, identifies the architectural paradigms gaining traction, and contextualizes the competitive maneuvers that will define market leadership in the coming years. The following sections outline the scope of the publication and the operational intelligence it delivers to stakeholders seeking to align security investments with organizational resilience objectives.
The Strategic Imperative: Why DNS Security Demands Executive Attention in 2026
DNS remains the foundational protocol that enables network communication, yet it has historically been treated as a utility rather than a security control. That paradigm is rapidly eroding. Adversaries now weaponize DNS to bypass traditional perimeter defenses, leveraging encrypted tunnels, fast-flux techniques, and domain generation algorithms to maintain persistent access while evading signature-based detection. The growing reliance on cloud-hosted workloads and distributed endpoints further amplifies the attack surface, making DNS-layer visibility and policy enforcement a non-negotiable component of modern security architectures.
Simultaneously, the regulatory environment is tightening around DNS infrastructure. Procurement guidelines now increasingly require encrypted DNS protocols for federal and critical infrastructure engagements, signaling a shift from voluntary adoption to compliance-driven deployment. In parallel, cybersecurity agencies and international policy frameworks are emphasizing the need for AI-enabled DNS analytics to counter adaptive threat behaviors. Organizations operating across North America, Europe, and Asia Pacific are responding by retooling their security stacks, prioritizing solutions that can provide real-time threat intelligence, automated remediation, and unified visibility across hybrid environments. These shifts create both urgency and opportunity for enterprises willing to invest in forward-looking DNS security capabilities.
Market Architecture and Momentum: A High-Level View of the 2026–2032 Outlook
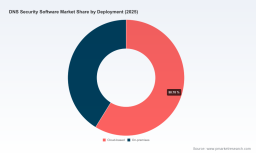
Our research models the DNS security software market as a dynamic ecosystem shaped by deployment preferences, organizational scale, and industry-specific risk profiles. Over the forecast period, cloud-based delivery models are positioned to dominate adoption curves, reflecting the broader industry migration toward scalable, subscription-driven security services. At the same time, on-premises deployments continue to hold strategic relevance for organizations with stringent data sovereignty requirements or legacy infrastructure dependencies. The interplay between these deployment pathways will influence vendor positioning, service design, and integration strategies throughout the forecast window.
Adoption patterns also diverge across organization size and vertical exposure. Large enterprises are expected to drive a substantial portion of total spending, reflecting their complex infrastructure footprints, compliance obligations, and higher tolerance for integrated security platforms. Small and medium-sized enterprises, meanwhile, are accelerating their investment cycles as managed service providers and simplified cloud offerings lower the barrier to entry. In terms of vertical exposure, sectors that handle sensitive data or operate mission-critical network environments—such as financial services, healthcare, and government—are likely to sustain elevated investment levels, reinforced by sector-specific threat landscapes and regulatory expectations. The full report unpacks these structural drivers in greater detail, offering qualitative and quantitative analysis that maps adoption trajectories to operational outcomes.
Inside the Report: Actionable Intelligence for Technology, Procurement, and Investment Decisions
This market research publication is designed to move beyond high-level market sizing and deliver practical decision support. The report is structured to provide clear visibility into the forces shaping vendor selection, architecture planning, and long-term budget allocation. Key components include:
DNS Security Software Market
- Market Sizing and Forecast Modeling – A multi-year revenue trajectory analysis covering historical performance and projected growth through 2032, contextualized by macroeconomic indicators, threat trends, and adoption drivers.
- Deployment and Operational Patterns – An assessment of cloud-based versus on-premises adoption dynamics, including the operational implications of hybrid DNS architectures, integration requirements, and total cost of ownership considerations.
- Organizational and Vertical Demand Profiles – An examination of how spending behavior differs across enterprise scale and industry context, helping readers benchmark internal priorities against broader market demand signals.
- Competitive Positioning and Product Differentiation – A detailed review of leading vendors, their strategic capabilities, and the evolving product features that are reshaping buyer expectations in the DNS security category.
- Regulatory and Policy Impact Analysis – A synthesis of recent mandates and guidelines influencing DNS procurement, encryption requirements, and AI-enabled security expectations, with implications for compliance-driven buying cycles.
- Deployment Readiness and Implementation Considerations – Practical guidance on evaluating solution fit, integration complexity, visibility requirements, and remediation workflows for real-world enterprise environments.
By aligning these analytical dimensions, the report enables technology leaders to assess capability gaps, procurement teams to structure evaluation criteria, and investors to understand where durable competitive advantages are likely to emerge.
Competitive Dynamics: The Vendors Reshaping DNS Security Strategy
The market landscape is defined by a concentrated group of established vendors, each pursuing distinct strategic angles within the DNS security category. Market concentration metrics suggest a competitive arena where the top tier collectively commands a meaningful share of overall revenue, while the remaining addressable space continues to invite differentiation through innovation, partnerships, and domain-specific solutions.
Cisco Systems anchors its offering in cloud-delivered DNS-layer security integrated with threat intelligence capabilities, positioning its platform as a proactive defense mechanism that blocks malicious activity before a connection is established. Infoblox emphasizes protective DNS and threat defense designed to safeguard core DNS infrastructure from hijacking attempts, cache poisoning, and denial-of-service disruptions. Cloudflare has expanded its footprint through DNS firewall functionality and resolver services that incorporate built-in DDoS mitigation, DNSSEC support, and malware blocking for both enterprise and consumer environments. Akamai Technologies continues to leverage its edge network strength with DDoS-resilient DNS delivery and posture management capabilities for hybrid cloud security. F5 Networks, Verisign, and Neustar contribute additional depth to the competitive field, offering advanced DNS security, load balancing, authoritative DNS services, and threat intelligence features tailored to enterprise and critical infrastructure use cases.
Competitive differentiation is increasingly shaped by agility, visibility, and ecosystem alignment. A recent product development from Akamai illustrates this trajectory: the introduction of DNS Posture Management, an agentless solution designed to deliver unified multicloud visibility over DNS assets with real-time monitoring and remediation capabilities. Alongside such product movements, partnership activity is also reshaping go-to-market dynamics. In a notable collaboration, IGIT partnered with NS1 and Cisco to accelerate agile DNS security application deployments focused on the EMEA region. These developments highlight how vendors are expanding beyond baseline DNS protection to deliver broader operational resilience, cross-cloud oversight, and regionally targeted implementation strategies.
Regulatory Currents and Industry Shifts Redefining the DNS Security Agenda
Beyond competitive activity, the DNS security market is being reshaped by policy evolution and operational standards that influence how organizations validate and procure security capabilities. Recent regulatory and guidance developments are pushing enterprises toward more resilient, encrypted, and intelligence-driven DNS practices. The U.S. Executive Order requiring support for encrypted DNS protocols as a procurement condition for federal agency DNS resolvers has established a compliance precedent that reverberates beyond the public sector, encouraging vendors and enterprise buyers to prioritize encrypted transport and stronger integrity controls.
Domain Name System Tools Market
At the same time, cybersecurity guidance bodies are increasingly emphasizing AI-enabled DNS solutions as a response to attackers targeting critical infrastructure through DNS-based vectors. This shift reinforces the expectation that next-generation DNS security will combine protocol-level safeguards with behavioral analytics and automated response mechanisms. In parallel, national cybersecurity strategies in markets such as Japan are driving broader adoption of AI-enabled threat detection within DNS protection solutions, signaling a global trend toward smarter, more adaptive defense architectures. These policy directions are not abstract mandates; they actively shape procurement criteria, vendor evaluations, and long-term technology roadmaps.
What 2026 Decision-Makers Should Prioritize
For organizations planning security investments in 2026, the market signals point toward a few strategic priorities. First, DNS security should no longer be treated as an ancillary network function; it must be integrated into the broader security architecture as a control point for threat prevention, visibility, and compliance assurance. Second, enterprises should evaluate solutions based on their ability to operate across hybrid environments, provide encrypted DNS support, and integrate with existing orchestration, logging, and response workflows. Third, buyers should scrutinize vendor roadmaps for evidence of AI-enabled analytics, multicloud DNS posture visibility, and partnerships that accelerate deployment in targeted regions or verticals.
Procurement teams will also benefit from understanding how market demand varies across organization size and industry exposure, enabling them to calibrate solution scope, service levels, and total cost expectations. For investors and analysts, the concentration dynamics and recent product and partnership movements offer useful indicators of where consolidation, differentiation, and channel expansion are most likely to occur.
Conclusion: Toward a More Resilient DNS Security Posture
The DNS Security Software market is entering a phase defined by higher adoption expectations, stronger regulatory alignment, and accelerating technical differentiation. Our latest market research provides the structured intelligence required to interpret these changes and translate them into actionable enterprise strategy. By examining the market’s growth trajectory, deployment patterns, competitive movements, and policy-driven demand shifts, the report equips leaders with the perspective needed to make informed decisions in 2026 and throughout the forecast period.
To access the full analysis, including detailed market sizing, forecast breakdowns, competitive assessments, and implementation insights, readers are encouraged to explore the complete report on the PW Consulting research portal. The full publication expands on every dimension discussed here and provides the deeper intelligence necessary for precise strategic planning.
For detailed analysis of this topic, please visit the official page: DNS Security Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com