

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Power Cords Market to Hit $6,680M by 2032, Driven by 6.2% CAGR

Strategic Intelligence in the Power Cords and Extension Cords Market: Navigating the 2026–2032 Forecast
As global electrification accelerates, infrastructure upgrades multiply, and connected devices proliferate across every sector, the power distribution ecosystem has become a focal point for strategic procurement, manufacturing planning, and competitive positioning. The Power Cords & Extension Cords Market is no longer a commoditized afterthought; it is a dynamic, regulation-sensitive, and geographically divergent segment where supply chain resilience, material economics, and compliance agility dictate margins. PW Consulting’s latest market research delivers a comprehensive, data-anchored view of this landscape, calibrated specifically to inform enterprise decisions across the 2026–2032 horizon.
This article serves as a strategic preview of the full report. It frames the macroeconomic trajectory, outlines the analytical architecture of the study, highlights the competitive dynamics shaping the sector, and embeds the latest regulatory and raw material developments that are already influencing sourcing strategies and product roadmaps. The objective is to demonstrate the report’s decision-ready rigor while preserving the granular breakdowns, scenario modeling, and proprietary benchmarking that reside in the complete publication.
Appliance Power Cord Market
Market Trajectory and the 2026–2032 Growth Arc
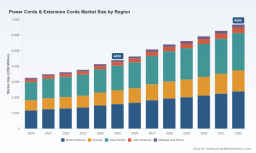
The historical baseline tells a clear story of steady, compounding expansion. From 2020 through 2025, the global market scaled from approximately 3.26 billion USD to an estimated 4.40 billion USD, reflecting resilient end-user demand, sustained construction and renovation activity, and the ongoing electrification of both consumer and commercial environments. That momentum carries decisively into the forecast window: the market is projected to reach roughly 4.63 billion USD in 2026 and continue its upward path toward approximately 6.68 billion USD by 2032.
Central to this trajectory is a sustained compound annual growth rate of 6.2 percent across the forecast period. While the headline figure signals healthy expansion, the real strategic value lies in what drives it. Growth is not uniformly distributed; it is being shaped by diverging regional development cycles, application-specific procurement patterns, and a structural split between indoor deployment, outdoor resilience requirements, and heavy-duty industrial specifications. Enterprises that treat the market as a single block risk misallocating capacity, mispricing SKUs, or overlooking compliance-driven substitution trends. The full report disentangles these layers, offering a calibrated view of where volume concentrates, where margin profiles diverge, and where short-cycle demand spikes are most likely to emerge.
For CFOs and supply chain leaders, the forecast is not merely a planning number; it is a stress test for inventory architecture, vendor diversification, and capital allocation. For product managers, it frames which performance tiers and certification pathways will command premium positioning. For competitive intelligence teams, it establishes the baseline against which market share shifts, pricing pressure, and regional entry timing can be measured.
Report Architecture: From Macro Signals to Operational Playbooks
The study is engineered to move beyond descriptive sizing and into actionable strategy. It combines rigorous historical reconstruction with forward-looking scenario analysis, giving leadership teams a multi-dimensional lens on demand, supply, and regulatory risk. The report’s structure is designed for direct integration into corporate planning cycles, with sections that translate market intelligence into procurement calendars, product portfolio decisions, and geographic expansion logic.
Readers can expect detailed segmentation mapping that clarifies how volume and value split across deployment environments and end-use contexts, without reducing the market to a single average. The analysis distinguishes between indoor configurations that dominate routine consumer and commercial setups, outdoor-rated solutions that must satisfy weather, abrasion, and UV resilience requirements, and heavy-duty variants engineered for sustained industrial loads and harsher operating conditions. Each category carries distinct material specifications, testing regimes, and price elasticity characteristics, and the report maps these differences to sourcing implications and commercial positioning.
Equally critical is the regional lens. Demand is shaped by local construction rhythms, retrofit cycles, data center build-outs, healthcare facility upgrades, and the pace of electrification in both developed and emerging markets. The publication provides a structured geographic framework that helps executives prioritize distribution partnerships, assess tariff and logistics exposure, and anticipate where certification requirements will create barriers or opportunities. Rather than presenting static share snapshots, the report contextualizes regional behavior within infrastructure spending patterns, import/export flows, and local compliance timelines.
The report also embeds procurement-relevant indicators, including material price trajectories, lead-time sensitivity, and the operational impact of standards revisions. By linking market size dynamics to the cost and compliance variables that actually move margins, the study enables scenario planning that is grounded in operational reality rather than theoretical growth curves.
Competitive Landscape: Coexistence of Scale Players and Niche Specialists
The competitive structure of the power cords and extension cords market reflects a deliberate division of labor between broad-line manufacturers and application-focused specialists. The full report profiles a cross-section of companies that illustrate how different strategic postures coexist within the same industry, each capturing value through distinct combinations of geographic reach, certification depth, and product engineering.
Southwire Company LLC, headquartered in Carrollton, GA, exemplifies the integrated producer that anchors its offerings in building wire, cable, and extension cords for utility, industrial, and commercial applications. Its position underscores the importance of vertical cohesion between core wire infrastructure and downstream power delivery products. Volex plc, based in Basingstoke, Hampshire, operates as a global integrated manufacturer of power cords, plugs, connectors, and custom wiring harnesses, serving consumer, industrial, and data center uses. Its profile highlights the strategic premium associated with custom configuration capabilities and multi-market qualification portfolios.
In residential and commercial electricals, Havells Ltd and Goldmedal Electricals demonstrate how regional manufacturing strength and broad distribution networks can secure enduring share in home electricals, flexible cables, switches, and power accessories. Their presence reinforces the reality that volume-driven segments reward brand trust, retail access, and consistent compliance execution as much as technical differentiation. At the same time, specialized manufacturers such as Ningbo Biaoda Electric Co., Ltd., YFC-Boneagle Electric Co., Ltd., Kord King, Electri-Cord Manufacturing, Jiaxing Hongzhou Cable Co., Ltd., Webber Electronics, Inc., Z-Tronix Inc., and Quail Electronics, Inc. illustrate the depth of capability available for hospital-grade, medical, dental, industrial, OEM, and international configuration requirements. These players often compete on certification breadth, custom cord-set engineering, and the ability to serve demanding end-use standards rather than on undifferentiated volume alone.
Strategically, the market structure matters because it shapes sourcing flexibility. Buyers can calibrate their supplier base between scale reliability and specialized compliance, while manufacturers must decide whether to compete on breadth, on certified performance in high-stakes applications, or on speed and configuration agility. The full report examines these positioning choices in greater depth, mapping how company footprints align with the segmentation and regional dynamics that drive demand.
Power Cords & Extension Cords Market
Regulatory and Material Dynamics Reshaping Sourcing Calculus
The market’s forward path is increasingly conditioned by the interplay of standards evolution and raw material economics. Two dynamics deserve particular attention because they directly influence product design, qualification timelines, and cost structures.
On the regulatory side, the July 30, 2025 revision of UL 817 introduced new requirements for Heater-Use Power-Supply Cords, with the broader standard for Cord Sets and Power-Supply Cords having been updated on the same date. For manufacturers and specifiers, this is not a procedural footnote; it is a product definition event. Heater-related applications impose distinct thermal, loading, and safety expectations, and revisions of this nature typically trigger requalification cycles, documentation updates, and in some cases material or construction adjustments. Companies that anticipate the operational implications of UL 817 changes can shorten time-to-compliance and reduce the risk of specification rejections, while those that treat standards revision as a back-office task may face delayed launches and eroded quoting accuracy.
On the cost side, polymer pricing remains a central variable in cord and cable economics. As of April 2026, PVC pricing diverged meaningfully by geography: China PVC prices reached approximately 735.45 USD per metric ton, while U.S. PVC prices stood at about 822.45 USD per metric ton. That gap is strategically significant for any organization balancing offshore sourcing, domestic production, inventory timing, and pass-through pricing. Material volatility of this nature influences not only direct cost of goods, but also the relative attractiveness of different product tiers, the feasibility of long-term supply agreements, and the negotiation leverage between buyers and suppliers. It also interacts with certification requirements, since material substitution in response to cost pressure must still satisfy performance and safety expectations.
Together, these forces define a market environment where compliance agility and input-cost intelligence are competitive differentiators. The full report integrates these developments into the broader dynamics section, linking standards and materials to segmentation behavior, regional cost structures, and the strategic options available to both producers and procurement organizations.
Why the 2026 Decision Window Demands This Level of Intelligence
Entering 2026, enterprises face a convergence of planning imperatives that makes high-resolution market intelligence essential. Demand is expanding at a durable pace, but the composition of that demand varies by environment, application, and region. Standards are being refined in ways that affect product eligibility and qualification lead times. Material pricing is diverging across geographies, altering the economics of sourcing models that may have appeared balanced on paper. In this context, decisions made on the basis of coarse market narratives are increasingly likely to produce suboptimal capacity allocation, misaligned SKU emphasis, or unanticipated compliance exposure.
The strategic value of this study lies in its ability to convert these moving parts into a coherent decision framework. It helps leadership teams answer practical questions: where should inventory and production emphasis be placed to match the most resilient demand pools; which product categories carry the strongest combination of volume and margin durability; how should supplier portfolios be structured to absorb material volatility and certification cycles; and where do regional dynamics create entry timing advantages or risks. By anchoring these questions in a 2026–2032 horizon, the report enables plans that are forward-compatible rather than reactive.
For organizations that compete on reliability, certified performance, or configuration agility, the publication also serves as a benchmarking foundation. Understanding how market size, segmentation behavior, and competitive positioning interlock makes it possible to calibrate go-to-market priorities, refine pricing strategy, and anticipate where differentiation will command premium attention in specification processes.
What the Complete Study Unlocks
This preview has outlined the structural logic of the market, the trajectory implied by the historical and forecast data, the competitive architecture that defines how value is captured, and the regulatory and material variables that are already reshaping operational calculus. The full report extends well beyond this frame. It delivers the detailed segmentation analysis, regional demand context, company profiling depth, standards impact assessment, and material-cost sensitivity perspective needed to translate macro direction into executable plans.
Because the study is designed to support real-world decision cycles, the complete version includes the granular breakdowns, scenario considerations, and benchmarking references that leadership teams require when setting procurement calendars, prioritizing product development, evaluating distribution geography, and stress-testing sourcing strategies against regulatory and input-cost shifts. These elements are intentionally developed in full within the publication so that readers can apply them directly to internal planning without having to reconstruct the underlying logic.
For executives, analysts, and operations leaders who need to align strategy with the realities of a growing but increasingly complex market, the complete research offers the evidentiary base and structural clarity required to move from awareness to action. To access the full segmentation detail, competitive profiles, regional context, and compliance and materials analysis, and to integrate the complete forecast with your internal planning models, visit the source page for the Power Cords & Extension Cords Market research and obtain the full report.
For detailed analysis of this topic, please visit the official page: Power Cords & Extension Cords Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com