

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: GaN on Diamond Market Hits $33M in 2025, Projects 17.0% CAGR to 2032

Precision Cooling, Strategic Cooling: Why GaN on Diamond Semiconductor Substrates Demand Your 2026 Attention
The Silent Inflection Point in High-Power Electronics
The semiconductor industry has long treated thermal management as a constraint to be engineered around, but a structural shift is underway. Gallium nitride on diamond substrates represent a material alliance that redefines what is physically possible in high-power, high-frequency electronics. At the device level, the underlying semiconductor continues to deliver superior electron mobility and switching performance, while the diamond substrate introduces thermal conductivity that conventional silicon carbide or aluminum nitride platforms simply cannot match. This convergence is no longer confined to laboratory demonstrations or defense prototypes. It is entering a phase where capital allocation, supply chain design, and product roadmaps must account for it as a mainstream strategic variable. Our latest market research on GaN on Diamond Semiconductor Substrates is built for decision makers who need to understand not just where the market is heading, but what it means for sourcing strategies, competitive positioning, and technology bets in 2026 and beyond.
The strategic importance of this substrate category lies in its ability to unlock higher power density without sacrificing reliability. Systems that once required aggressive external cooling, large thermal spreaders, or operational compromises are now being re-evaluated under a new thermal envelope. Radar architectures, satellite communications payloads, and broadband RF amplifiers are among the first to benefit, but the ripple effects extend into any design where heat flux has become the limiting factor. As device architects push toward higher frequency, smaller form factors, and more demanding duty cycles, the choice of substrate is no longer a cost detail. It is a performance multiplier that can determine whether a product vision is achievable at all.
This analysis is intended to give executives, product leaders, and technology strategists a grounded view of that inflection point. It synthesizes historical trajectory, forward-looking growth dynamics, competitive behavior, and the operational friction that shapes commercialization. The goal is to provide enough analytical rigor to support serious planning, while deliberately leaving the granular breakdowns for the full report, where the type-specific, application-specific, and regional intelligence is structured for direct use in investment cases, sourcing decisions, and go-to-market timing.
From Niche Capability to Commercial Infrastructure
The market for GaN on Diamond Semiconductor Substrates has moved through a recognizable evolution over the past several years. Early activity was defined by material science validation, limited wafer availability, and a narrow set of high-value applications willing to absorb premium costs. That period established proof of concept and created the first credible supply relationships. What followed has been a transition from experimental adoption to more deliberate commercial scaling, where demand signals are increasingly tied to real product requirements rather than research curiosity alone.
Over the historical window from 2020 through 2025, revenue growth has reflected this maturation pattern, with the market expanding from a relatively modest base in 2020 to a materially larger footprint by the end of the current base year. That progression is not merely a story of rising unit demand; it signals growing confidence among downstream buyers and a broader acceptance that diamond-enabled thermal performance can justify the economics in the right contexts. The trajectory into the forecast period through 2032 suggests that this is not a short-lived hype cycle. Instead, the market appears positioned to sustain a compound annual growth rate of approximately 17.0 percent, implying a path toward nearly one hundred million USD in revenue by the close of the forecast window.
For strategists, the most important implication is not the headline number itself, but the shape of the growth curve. A sustained double-digit CAGR across a multi-year horizon typically indicates that adoption is being pulled by application requirements and that the enabling ecosystem—material supply, device integration, and system-level validation—is expanding in parallel. This is the kind of market dynamic where timing matters. Companies that wait until the category is fully commoditized may find themselves competing in a crowded late-entry environment. Companies that engage too early, without a clear value proposition or supply assurance, risk absorbing costs that the broader market is not yet prepared to support. The current window offers a distinct advantage to those who can align technical readiness with disciplined commercial logic.
The Commercial Core: Where Value Is Actually Created
A market of this nature only becomes strategically useful when it is understood at the level of type, application, and regional behavior. That is where the broad narrative separates from the decisions that actually move budgets and engineering plans. In the full study, these dimensions are developed in detail so that leaders can distinguish between segments that are genuinely scaling and those that remain aspirational or constrained. For now, the executive-level picture is clear enough to frame the opportunity without giving away the operational architecture that makes the research actionable.
On the material side, the substrate landscape is anchored by a meaningful divide between single crystal diamond and polycrystalline diamond. That distinction is not a minor specification detail; it shapes thermal performance, device integration complexity, yield economics, and the set of applications where the solution is genuinely defensible. Different end use cases tolerate different trade-offs between performance and cost, and knowing which substrate form factor aligns with which market need is essential for pricing strategy, roadmap planning, and investor storytelling. The broader market structure reflects a clear performance-intensive core, with the dominant material category capturing a substantial share of current revenue while the secondary category serves more cost-sensitive or application-flexible roles.
On the application side, the demand engine is concentrated in segments where power density, thermal resistance, and frequency performance are non-negotiable. RF power amplifiers stand out as a leading driver, reflecting the ongoing push for higher output, better efficiency, and more compact designs in advanced communications and electronic warfare systems. Microwave and millimetre wave circuits represent another substantial pillar, given their importance to high-bandwidth links, sensing systems, and next-generation communication architectures. Radar sensing equipment adds a further layer of demand tied to defense, aerospace, and industrial detection requirements, while additional emerging uses continue to broaden the addressable space. In the complete analysis, these application dynamics are unpacked so that buyers can see not just where revenue originates today, but which application clusters are most likely to become the primary growth engines over the forecast horizon.
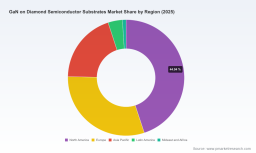
Regionally, the market is far from uniform. Some geographies command disproportionate share based on underlying industry structure, defense procurement patterns, satellite infrastructure development, and the presence of advanced semiconductor manufacturing and integration ecosystems. Other regions reflect smaller but strategically meaningful entry points, where demand may be less mature today but where supply chain localization, government support, or regional technology initiatives could reshape participation over time. The complete study preserves these regional distinctions in a form that supports scenario planning, supplier evaluation, and footprint decisions without reducing the market to a simplistic one-size-fits-all narrative.
Competitive Architecture: Who Shapes the Market and How
The GaN on Diamond Semiconductor Substrates market is not a fragmented commodity landscape. It is a space where a relatively concentrated group of specialized players exerts significant influence over technology direction, supply availability, and customer confidence. The overall market concentration reflects that reality, with a modest group of leading participants commanding a meaningful share of activity. That concentration matters because it signals where buyer leverage sits, where supplier dependency may emerge, and where partnerships or vertical integration strategies could alter bargaining power over the next several years.
Element Six continues to occupy a foundational role in synthetic diamond substrates, particularly where extreme thermal performance is required for RF, power, and defense electronics. Its technology relevance extends beyond material supply, touching the credibility and performance baseline of the entire category. Akash Systems has been advancing GaN-on-diamond in the context of satellite communications, where thermal and efficiency constraints are especially acute and where the value of effective cooling can directly influence payload architecture. Qorvo, Inc. is positioned where GaN-on-diamond transistors and power amplifiers intersect with RF and satellite applications, giving it a device-level perspective that bridges substrate capability and system performance.
RFHIC Corporation adds a notable regional and application-specific strength, particularly in radar, microwave, and satellite-related uses where wafer and epi-level capability can shape downstream competitiveness. Coherent Corp. is relevant for its push to scale GaN-on-diamond wafers for broader commercial RF applications, which speaks to an important industry goal: moving performance-leading materials into markets that can absorb volume if the economics improve. Blue Wave Semiconductor rounds out the competitive picture with a focus on high-power RF and defense electronics, reinforcing the recurring theme that defense and high-performance communications remain central demand anchors for this substrate class.
Recent activity among these players makes the strategic stakes even clearer. In March 2025, Element Six introduced a new ultra-high-purity single-crystal diamond wafer optimized for RF and power device applications, underscoring the continued focus on material quality as a differentiator. In April 2025, Cree Inc. completed the acquisition of a diamond synthesis startup, a move that points toward greater vertical integration and an effort to strengthen control over key steps in the GaN-on-diamond product chain. In May 2025, Akash Systems secured CHIPS Act funding to advance diamond-cooling satellite technology, highlighting how public investment can accelerate development in strategically prioritized segments. In August 2025, a consortium of Japanese firms launched a regional diamond synthesis facility with the stated aim of improving supply chain resilience for GaN-on-diamond substrates, reflecting a broader push to reduce dependency risk in critical material flows. And in November 2024, Qorvo unveiled a GaN-on-diamond power amplifier for satellite communications designed to reduce thermal resistance, illustrating how product-level innovation continues to validate the material strategy in real deployments.
Together, these developments show a market that is not standing still. Participants are pursuing advancement through material improvement, acquisition, funding, regional capacity expansion, and product-level demonstrations. For customers and competitors alike, the implication is that the landscape will likely remain dynamic, with differentiation arising from purity, thermal performance, supply assurance, integration capability, and alignment with the highest-value applications.
Forces Shaping the Road Ahead: Friction, Policy, and Supply Realities
No strategic assessment of this market would be complete without acknowledging the forces that temper enthusiasm with operational realism. GaN on Diamond Semiconductor Substrates face several bottlenecks that influence both timing and economics. Supply chain bottlenecks in diamond wafer production and high production costs remain central constraints, limiting how quickly commercial scaling can proceed across broader applications. The cost associated with CVD diamond wafer fabrication and bonding processes adds further expense, which means that adoption is, at present, concentrated where the thermal and performance payoff is large enough to justify premium pricing. Limited global diamond wafer production capacity reinforces this dynamic by creating supply constraints that can slow ramp-up, particularly if demand accelerates faster than manufacturing can accommodate.
Geopolitical and policy factors are equally important. Supply disruptions tied to broader conflict-related logistics challenges have contributed to regional imbalances in substrate availability, reminding participants that material access is not purely a technical problem. At the same time, U.S. defense-related contracting activity continues to promote GaN-on-diamond integration in defense and hypersonic applications that impose demanding thermal and power density requirements. This type of demand does not merely add volume; it shapes product specifications, drives qualification priorities, and can pull the entire ecosystem toward higher performance benchmarks.
These dynamics create both opportunity and caution. For suppliers, the challenge is to expand capacity and reduce cost without compromising the material quality that makes the category compelling in the first place. For buyers, the challenge is to secure access to qualified substrates while avoiding over-reliance on narrow supply channels. For investors and strategists, the challenge is to separate durable structural growth from near-term optimism that may be vulnerable to cost, capacity, or geopolitical friction. The complete research study is designed to address these tensions head-on, offering the kind of operational context needed to evaluate entry timing, partnership strategy, and risk exposure with greater confidence.
What This Research Delivers for 2026 Planning
Strategic decisions in fast-moving technology markets are often made under incomplete information. The value of a strong industry study is not simply to confirm what leaders already suspect, but to equip them with structure, evidence, and scenario-ready intelligence that can be used in budgeting, sourcing, product planning, and competitive response. This GaN on Diamond Semiconductor Substrates market report is built around that practical purpose.
At the executive level, the study provides a clear view of historical performance and forward-looking growth dynamics, enabling leaders to assess whether the market is large enough, fast enough, and application-backed enough to justify dedicated attention in 2026 planning cycles. At the operating level, it goes further into the segmentation logic that matters for real decisions: type-wise distinctions, application-wise demand patterns, and regional participation. These breakdowns are essential for understanding where margin profiles may differ, where competition is more intense, and where strategic entry or partnership can be timed for maximum advantage.
The report also addresses the competitive field in a way that supports benchmarking and positioning. Rather than presenting company names as a static list, it frames them within the logic of what each participant is trying to achieve, how they are competing on material quality, device integration, and application fit, and what recent developments suggest about the direction of travel. That approach helps readers evaluate supplier partnerships, assess threat vectors, and anticipate where consolidation, capacity expansion, or targeted funding may alter market balance.
Equally important, the study integrates the operational and external forces that shape execution risk. Supply constraints, cost structures, geopolitical disruption, and defense-driven requirements are treated not as side notes, but as factors that affect viability, timing, and the realistic pace of commercialization. That context is especially valuable for organizations evaluating whether to adopt, invest, qualify, or partner, because the difference between a promising technology and a defensible business case often lies in those practical details.
Readers looking for the full strategic picture will find detailed segmentation values, market size trajectories, competitive profiles, and scenario-ready context in the complete report. Those details are intentionally not enumerated here, because the study is designed to function as a decision tool rather than a summary that can be fully consumed at a glance. The most useful reading of this category is one that connects the broad growth narrative with the granular intelligence required to act on it.
Worldwide Synthetic Single Crystal Diamond Market
The Strategic Takeaway
GaN on Diamond Semiconductor Substrates are transitioning from a high-performance exception to a strategically relevant platform for a defined set of demanding applications. That transition matters because thermal constraints are becoming more expensive to ignore and because the competitive landscape is evolving quickly through material innovation, funding, acquisition, regional capacity building, and product-level validation. The market's growth trajectory indicates that serious interest is warranted, but the real value lies in understanding the structure beneath the growth curve: which types lead, which applications drive demand, which regions matter most, and how supply and policy forces shape execution risk. For organizations planning in 2026, the question is no longer whether the category deserves attention. The question is whether they will engage with enough foresight to shape their own position rather than react to it later. The full research study is prepared to help answer that question with the precision that high-stakes semiconductor strategy requires.
GaN on Diamond Semiconductor Substrates Market
For detailed analysis of this topic, please visit the official page: GaN on Diamond Semiconductor Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com