

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Textile Chemicals Market to Reach $41.34 Billion by 2032 at 4.8% CAGR

Navigating the Textile Chemicals Market: Strategic Intelligence for 2026 and Beyond
The global textile chemicals market stands at a critical inflection point. As supply chains recalibrate, regulatory frameworks tighten, and sustainability imperatives reshape procurement priorities, chemical suppliers, formulators, and textile manufacturers must look beyond historical benchmarks to anticipate the forces that will define competitive advantage through 2032. Our newly released Textile Chemicals Market research delivers the analytical architecture required to navigate this complexity with precision.
Built on a rigorous six-year historical foundation spanning 2020 through 2025 and projecting forward across a seven-year forecast horizon, this study translates macro-level trajectory data into actionable decision frameworks. The market reached an estimated USD 30.0 billion in 2025, building on a steady climb from USD 21.5 billion in 2020. Forward projections indicate the sector will expand to USD 31.4 billion in 2026 and continue its ascent toward USD 41.34 billion by 2032, underpinned by a compound annual growth rate of 4.8 percent. These figures are not merely retrospective confirmations; they represent the baseline against which capital allocation, capacity planning, and product portfolio strategy must be calibrated in the current fiscal year.
For executives evaluating market entry, expansion, or repositioning, understanding the velocity and distribution of this growth is indispensable. The report dissects the trajectory across multiple analytical dimensions, enabling leadership teams to isolate high-probability opportunities while mitigating exposure to structural headwinds. This introduction outlines the strategic architecture of the study, the competitive and regulatory forces reshaping the landscape, and the practical intelligence embedded within each chapter.
Strategic Value for 2026 Decision-Making
The 2026 operating environment demands more than aggregated market data. Procurement leaders, R&D directors, and corporate strategists require segmentation that aligns with actual purchasing behavior, formulation economics, and regional supply dynamics. Our research is structured to answer the questions that directly influence quarterly planning and multi-year investment thesis:
- Which product categories are capturing disproportionate value share, and what formulation or performance attributes are driving that preference?
- How are end-use sectors reallocating chemical procurement budgets as apparel demand stabilizes, home textiles evolve, and technical textiles gain industrial traction?
- Where are regional demand centers converging with manufacturing capability, and which logistics or compliance constraints reshape margin profiles?
- What concentration patterns exist among incumbent suppliers, and how does that influence negotiation leverage, supply continuity, and partnership strategy?
The study maps these dimensions without diluting them into superficial aggregates. Instead, it provides a layered view that allows teams to drill from high-level trajectory into category-level dynamics, application-driven procurement patterns, and regional variation in demand intensity. The forecast period through 2032 is particularly valuable for capacity expansion decisions, M&A screening, and long-range product development roadmaps, because it connects near-term momentum with the structural shifts that will compound over the next seven years.
By anchoring 2026 planning in a market that has already demonstrated resilience through post-pandemic normalization and is now encountering a new wave of regulatory and sustainability requirements, organizations can move from reactive adjustments to proactive positioning. The report is designed to be a working document for strategy sessions, not a static reference, with analytical constructs that translate directly into investment memos, procurement guidelines, and commercial planning assumptions.
Competitive Landscape and Key Players
The competitive architecture of the textile chemicals sector reflects a blend of global scale players, regional specialists, and integrated distributors, each pursuing distinct value propositions across the processing chain. Concentration analysis within the study indicates that the top three players command approximately 45 percent of market revenue, while the top five extend that share to roughly 55 percent. This level of consolidation signals meaningful competitive gravity around established formulations, technical service capabilities, and global distribution networks, while still leaving substantial space for regional specialists and niche innovators.
Several organizations define the current competitive frontier. Archroma, headquartered in Switzerland, operates as a global leader in sustainable dyes, colorants, and performance chemicals engineered specifically for dyeing, finishing, and printing applications. Its portfolio orientation toward sustainability-aligned formulations positions it at the intersection of regulatory compliance and premium product strategy. Sarex Chemicals, based in India, specializes in textile auxiliaries and pre-treatment chemicals, alongside solutions for dyeing and finishing processes, reflecting the depth of capability present among regional manufacturers that serve high-volume processing ecosystems. Fineotex Chemical, also India-based, manufactures specialty textile chemicals spanning pre-treatment, dyeing, printing, and finishing across the full value chain, illustrating the vertically broad approach some suppliers adopt to capture share at multiple processing stages.
Azelis, headquartered in Belgium, functions as a distributor and integrated supplier of dyes, bleaching agents, pretreatment chemicals, and finishing solutions, underscoring the continued importance of distribution-centric models that combine technical support with supply reliability. Huntsman Textile Effects, operating from Switzerland and Germany, provides functional dyes, textile finishing chemicals, and performance solutions, aligning its offering with applications that require enhanced fabric functionality and process efficiency. NICCA Chemical, Japan's leading developer and manufacturer of scouring, dyeing, and finishing chemicals, represents the technical precision and process expertise that characterize advanced Asian formulation capability. CHT Group, based in Germany, specializes in textile chemicals, auxiliaries, and dyeing solutions for printing, finishing, and processing, reinforcing Europe's enduring strength in specialty chemical engineering and application know-how.
These companies are not analyzed in isolation. The report places them within a competitive framework that considers portfolio breadth, regional footprint, sustainability alignment, technical service depth, and pricing architecture. By understanding where each player derives advantage, organizations can better anticipate supplier behavior, evaluate partnership candidates, and identify white spaces where new entrants or reformulated offerings could capture meaningful share.
Regulatory Acceleration and Industry Dynamics
No analysis of the textile chemicals market in 2026 is complete without confronting the accelerating pace of regulatory and standards-based change. Compliance is no longer a defensive cost center; it is a determinant of market access, brand partnership eligibility, and downstream customer trust. Recent developments make this reality unmistakable.
The regulatory environment has intensified across multiple fronts. OEKO-TEX STANDARD 100 reduced the Bisphenol A limit from 100 mg/kg to 10 mg/kg effective April 2025, following the WHO classification of BPA as an endocrine disruptor. Subsequent updates as of April 2026 added PFOS-related substances at 1 mg/kg and introduced two new SVHC substances, Decamethyltetrasiloxane and siloxanes, at 1000 mg/kg. In October 2025, OEKO-TEX also added new SVHC substances with 1000 mg/kg limit values for STANDARD 100, while setting the PFOS limit at 25 µg/kg for STANDARD 100 and ORGANIC COTTON. These revisions compress the formulation tolerance window and raise the cost of non-compliance, compelling suppliers and manufacturers to revalidate inputs and adjust recipes.
Textile Chemicals Market
France introduced a parallel constraint through Law 2025-188 and Decree 2025-1376, which prohibit PFAS-containing textiles, clothing, footwear, and waterproofing agents effective January 2026, with limited exemptions for certain recycled or industrial applications. This national measure signals a broader European appetite for targeted chemical restrictions and creates direct implications for finishing agents, waterproofing chemistries, and performance additives used in apparel and home textile applications.
On the standards side, GOTS Version 8.0, released in March 2026, introduces new chemical input approval criteria, enhanced accountability provisions, and mandatory due diligence for organic textile chemicals, effective March 2027. The update mandates toxicity hazard requirements and on-site audits for all textile chemicals used in organic fibre production. For suppliers serving certified organic supply chains, the compliance burden and documentation rigor increase materially, and early alignment becomes a competitive differentiator rather than a last-minute remediation exercise.
The ZDHC Roadmap to Zero Programme also advanced with its 2025 microfibre research and ClearStream wastewater guidelines for textiles and leather, reinforcing zero-discharge targets and pushing the industry toward more rigorous effluent management. These guidelines interact directly with chemical selection, process design, and wastewater treatment strategies, making chemical performance in aqueous systems a strategic consideration rather than a purely technical parameter.
Industry events reflect the same momentum. Techtextil 2026 launched a dedicated Textile Chemicals & Dyes product segment featuring more than 30 exhibitors presenting dyes, auxiliaries, functional finishes, and polymer technologies. Early booking for the segment, announced in February 2026, confirmed participation from major players such as Archroma, CHT, and Rudolf, signaling strong industry appetite for concentrated knowledge exchange. In parallel, the 52nd DyeChem Asia International Expo is scheduled for 3–5 June 2026 in Thailand, positioning itself as Asia's platform for textile chemicals and auxiliaries and underscoring the region's centrality to supply, innovation, and cost dynamics.
Report Scope and Actionable Insights
To translate this landscape into usable intelligence, the report is organized around operational decision points rather than abstract market description. It starts with a comprehensive market sizing and forecast architecture that connects historical performance with forward projections, providing a consistent baseline for scenario planning. From there, the analysis segments the market by type, application, and region, enabling readers to identify where growth is concentrated and where structural constraints may temper expansion.
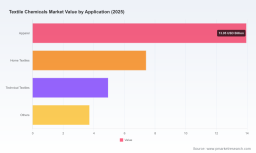
The type perspective examines categories such as colorants and auxiliaries, coating and sizing agents, finishing agents, and other specialized inputs, clarifying which functional roles are capturing demand and why. The application perspective maps consumption across apparel, home textiles, technical textiles, and other uses, linking chemical demand to end-market behavior, fabric engineering requirements, and processing intensity. The regional perspective evaluates demand distribution and supply interplay across major geographic zones, highlighting where manufacturing concentration, import reliance, regulatory cadence, and logistics economics shape market outcomes.
Beyond segmentation, the study integrates competitive profiling, regulatory mapping, and value chain dynamics into a coherent narrative. Readers gain visibility into concentration patterns, supplier positioning, and the strategic implications of recent standards revisions and trade-show momentum. The report also examines how sustainability requirements, wastewater expectations, and restricted-substance lists are reshaping formulation choices, procurement criteria, and supplier qualification processes. This integrated view is intended to support cross-functional teams—from R&D and procurement to sales and corporate development—in aligning their assumptions and priorities.
Why This Study Matters Now
The textile chemicals market is being reshaped by forces that reward early clarity and penalize delayed response. Regulatory thresholds are tightening, standards bodies are increasing audit and due-diligence requirements, and major trade platforms are consolidating chemical-focused programming, all of which indicate that the information environment is becoming more structured and more consequential. At the same time, the macro trajectory points to sustained expansion, with the market projected to advance from USD 31.4 billion in 2026 to USD 41.34 billion by 2032. Sustained growth in a tightening compliance environment creates a paradox: opportunity expands, but the pathway to capturing it narrows for organizations that lack precise intelligence.
This report is designed to resolve that tension. It provides the segmentation, competitive context, regulatory mapping, and forecast discipline required to make 2026 decisions with confidence and to extend those decisions into a defensible multi-year strategy. For organizations evaluating supplier partnerships, formulating product roadmaps, planning capacity, or screening market-entry opportunities, the study offers a structured foundation for informed action.
Textile Dyes Market
The full analysis, including detailed segmentation breakdowns, competitive profiles, regulatory timelines, and forward-looking scenario constructs, is available through our complete Textile Chemicals Market research. We invite strategy, procurement, and commercial teams to access the full report and use its architecture to sharpen their 2026 planning and position their organizations for the growth trajectory ahead.
For detailed analysis of this topic, please visit the official page: Textile Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com