

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: IT & Electronics
PW Consulting Forecasts D&O Insurance Market to Expand at 7.64% CAGR Through 2032
By pmarketresearch, 2026-07-15
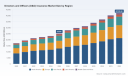
Directors and Officers (D&O) Insurance Market 2026: Strategic Imperatives from PW Consulting’s Market Outlook
As boards, risk officers, insurers, and brokers enter 2026, the Directors and Officers (D&O) insurance landscape has moved from episodic volatility to a new, structurally nuanced phase. Our latest PW Consulting Directors and Officers Insurance Market report — with a 2025 base year and a 2026–2032 forecast horizon — synthesizes five years of market evolution (2020–2025) and delivers the decision-grade intelligence leaders need to set underwriting strategy, capital allocation, and governance priorities for the next strategic cycle.
Directors and Officers (D&O) Insurance Market
Why this report matters for 2026 decision-making
-
Market scale and trajectory. The global D&O market stood at USD 25,200 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of approximately 7.64% through the forecast window. By 2032, our baseline projection places the market in excess of USD 42 billion, underscoring continued commercial opportunity alongside rising exposure complexity.
Directors and Officers (D&O) Insurance Market -
Claims inflation and cost pressure. Legal-services inflation and growing claim severity are shifting loss-cost curves. Our analysis quantifies the downstream impact on defense erosion, retention economics, and insurer working layers — forces that will shape renewals, capacity deployment, and product design in 2026.
Directors and Officers (D&O) Insurance Market -
Emerging liabilities are reshaping underwriting. AI governance, ESG-related disclosure risks, cyber-linked director exposures, and geopolitical trade friction have transitioned from perimeter concerns to central underwriting criteria. Boards and insurers who align governance frameworks with updated coverage architecture will gain first-mover advantage.
-
Stabilizing but selective pricing environment. Market intelligence from multiple sources indicates premium stabilization in 2026 with selective upward pressure in higher-severity lines and sectors exposed to insolvency and securities litigation. That selective repricing creates both threat and opportunity across client segments.
Report at a glance — practical, actionable deliverables
PW Consulting’s market study is structured as a working playbook for commercial and strategic decisions in 2026. Key deliverables include:
-
Market sizing and trajectory modeling — multi-scenario forecasts calibrated to macro and micro drivers, enabling stress-testing of premium and loss scenarios under different economic and litigation environments.
-
Claims- and defense-cost heat maps — qualitative and quantitative drivers of severity by risk vector, with implications for attachment points, aggregate buying patterns, and policy wordings.
-
Underwriting playbooks — sector-specific risk checklists, enhanced submission templates, and recommended covenants for governance, cyber hygiene, and AI oversight.
-
Product and pricing architecture options — design templates for layered covers, bespoke Side A enhancements, and modular add-ons that respond to insolvency, cyber contagion, and regulatory inquiry risk.
-
Distribution and broker strategies — go-to-market recommendations for cross-sell, capacity allocation, and incentive alignment with placement partners.
-
Regulatory and litigation scenario toolbox — mapped pathways for regulatory shifts, securities-class action dynamics, and cross-border enforcement that could materially affect D&O exposures.
-
Insurer benchmarking and competitive scorecards — forward-looking capability assessments across underwriting, claims handling, and product innovation to inform partner selection and M&A diligence.
Competitive landscape — how incumbents are positioning for 2026
The market’s center of gravity remains with well-capitalized insurers that combine global placement capabilities with specialized product engineering. Our competitive analysis synthesizes public positioning, capability signals, and product emphasis across incumbents to reveal strategic vectors for 2026.
-
Chubb — Leverages multinational distribution and local policy footprints to serve complex, cross-border placements. Their focus on tailored Side A enhancements and governance-driven underwriting makes them a lead partner for multinational boards seeking continuity of coverage across jurisdictions.
-
AIG — Continues to emphasize comprehensive management-liability suites for public, private, and nonprofit clients, with product breadth calibrated to securities and regulatory claims. Their scale positions them to underwrite layered placements and participate in larger excess placements.
-
Travelers Insurance — Concentrates on disciplined underwriting and claims protection for middle-market clients, with product simplicity and distribution reach that resonate with sector-focused risk managers.
-
Liberty Mutual / Ironshore — Known for underwriting complex risks, Liberty’s specialty platforms are tilting toward bespoke solutions for emergent exposures, including insolvency and professional-liability cross-overs.
-
Allianz — Public thought leadership on geopolitics, insolvency trends, and cyber contagion has positioned Allianz as a go-to provider for global boards navigating macro risk amplification.
-
Zurich Insurance Group — Focuses on integrated solutions for multinational and mid-sized enterprises, emphasizing management and professional liability alignment coupled with risk mitigation advisory.
-
AXA XL — Offers targeted financial-lines innovations; their willingness to enhance coverage for emerging exposures (e.g., AI oversight clauses) is a differentiator in competitive placements.
-
Beazley — Strong in specialty and cyber-convergent risks, with product agility and claims advocacy that appeal to digitally exposed boards and smaller-cap public entities.
-
Hiscox — Targets small-to-mid-sized enterprises with streamlined offerings and sector-oriented distribution, capturing scale in a price-sensitive segment.
-
Berkshire Hathaway Specialty Insurance — Competes on balance-sheet strength and willingness to support high-limit, complex risk placements — an important capacity partner in layered towers.
Across the competitive set, the differentiators for 2026 will include: product modularity tied to governance controls; speed and transparency of claims response; redistribution of capacity across reinsurers; and data-driven underwriting for AI and cyber-related director exposures.
Industry dynamics and recent development signals
-
Rising insolvency pressure: Industry research signals a near-term uptick in global business insolvencies. This trend materially amplifies D&O exposure in sectors with capital-cycle stress (notably automotive, construction, and retail) and should inform sector-specific underwriting stress tests.
-
Securities litigation backdrop: Public filings and industry reports indicate a step-up in settlement sizes for securities class actions, a factor that sustains high attachment energy in public-company placements.
-
Legal cost inflation: Cumulative legal-services inflation has materially increased defense costs since 2020. That rise is eroding traditional working layers and pushing reinsurers and primary underwriters to reassess retention policy economics.
-
Emergent liability vectors: AI governance, ESG reporting, and geopolitical risk are now principal considerations when underwriting the fiduciary and oversight exposures of executives and boards.
-
Market sentiment: Multiple market commentators and rating agencies have signaled stabilization in premium trajectories for 2026 but with selective tightening where loss frequency or severity is increasing.
Strategic imperatives for boards, insurers, and brokers in 2026
-
Boards and senior management: Integrate insurance-aware governance. Enhance disclosure discipline, adopt board-level AI oversight frameworks, and coordinate with CFOs and risk officers to model D&O contingent liabilities under bankruptcy and securities-litigation scenarios.
-
Insurers and underwriters: Re-calibrate product architecture toward modular, governance-linked covers and introduce clearer triggers for cyber-related director exposures. Embed legal-cost inflation assumptions into loss-model scenarios and reassess working-layer economics.
-
Brokers and distribution partners: Develop solution bundles that pair preventive advisory (governance, cyber hygiene, AI policy) with placement strategies that reduce attach risk and lower total cost of risk for clients.
-
Reinsurers and capital providers: Prioritize capacity allocations to segments with predictable underwriting tail and develop products that flex capacity in response to litigation cycles and insolvency waves.
-
Investors and M&A teams: Include D&O exposure mapping in diligence playbooks, focusing on historical governance incidents, litigation pipelines, and cross-border enforcement risks that can materially affect post-closing liability profiles.
How PW Consulting translates analysis into advantage
Our D&O market study is intentionally structured as a decision instrument: not just descriptive market intelligence, but prescriptive playbooks and scenario toolkits that teams can operationalize during renewals, budgeting cycles, and strategic planning. Core capabilities we deploy for clients include bespoke scenario modeling, underwriting optimization workshops, claims-readiness diagnostics, and M&A D&O due-diligence packages.
In keeping with our "trailer" principle, this press summary surfaces the macro trajectory, competitive themes, and strategic imperatives — while preserving the detailed, segment-level data and dynamic matrices that make the full report uniquely actionable. If your strategic plan for 2026 depends on precise regional supply-demand balances, coverage-level elasticity, competitor share dynamics, or modeled loss-cost ladders, the full PW Consulting report provides that calibrated intelligence and downloadable analytical assets.
Next steps
-
Download or request the full Directors and Officers Insurance Market report to access the comprehensive data annex, segment-level forecasts, insurer scorecards, and implementation templates.
-
Contact PW Consulting for a tailored briefing: we offer executive summaries, board-ready slide decks, and scenario workshops that translate the report’s insights into executable 90–180 day plans.
-
Engage in a rapid diagnostic if you are preparing for a major renewal, capacity negotiation, or M&A transaction — our team will align the report’s findings to your specific exposures and strategic objectives.
The D&O market in 2026 presents a dual narrative: expanding commercial scale alongside intensifying exposure complexity. Boards and insurers who combine forward-looking governance with disciplined underwriting, targeted product innovation, and scenario-based capital planning will capture disproportionate value. PW Consulting’s report equips decision-makers with the framework and the data to act confidently — and to act early.
For detailed analysis of this topic, please visit the official page: Directors and Officers (D&O) Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: International Business Travel Insurance Plans Market Poised for 7.85% CAGR, New Insights Reveal
By pmarketresearch, 2026-07-15
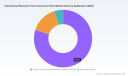
PW Consulting: Strategic Brief — International Business Travel Insurance Plans Market (Base year 2025) — A 2026 Decision‑Maker’s Playbook
PW Consulting today publishes an executive briefing drawn from our full market research report on the International Business Travel Insurance Plans market. Built on a 2025 base year and a historical review (2020–2025), the research presents an independent forecast through 2032. At a macro level, the market is projected to grow at a compound annual growth rate (CAGR) of 7.85% — expanding from roughly USD 18.5 billion in 2025 to approximately USD 31.4 billion by 2032. For executives and procurement leaders planning for 2026, the report crystallizes where investment, partnerships and product innovation will deliver the greatest strategic upside — and where the greatest operational risk lies.
International Business Travel Insurance Plans Market
Why this briefing matters for 2026 strategy
-
Actionable foresight: 2026 will be the first full planning cycle where firms must translate post‑pandemic travel recovery into resilient, compliant, and cost‑efficient travel risk programs. Our forecast and scenario work turn macro growth assumptions into concrete implications for insurer selection, benefit design, and vendor governance.
International Business Travel Insurance Plans Market -
Duty of care as a business imperative: Regulatory and corporate expectations around employee safety are converging with buyer willingness to pay for enhanced coverage. This alters procurement criteria — from price‑only comparisons to assessments of network strength, evacuation capabilities, and real‑time assistance services.
International Business Travel Insurance Plans Market -
Operational levers for immediate impact: Small changes in policy design and distribution (e.g., bundling digital assistance, telemedicine, and trip disruption cover) can materially reduce company exposure and improve traveler experience — measurable ROI we map in the report.
Key strategic implications for corporate buyers and insurers in 2026
-
Reconfigure supplier agreements around outcomes, not just premiums. Our client work shows most value is captured by purchasers who introduce SLAs tied to response times for medical evacuations, claims turn‑around and post‑event assistance.
-
Invest in data and integration. Integrating insurer APIs with travel‑management platforms and HR systems is becoming table stakes for automated enrollment, near‑real‑time risk alerts and T&E reconciliation.
-
Differentiate through hybrid products. Expect demand for blended offerings that combine short‑term trip cover with global employee health wraps, emergency assistance and wellbeing services. These hybrids increase stickiness and margin potential for carriers that can underwrite cross‑product exposures.
-
Prioritize distribution partnerships. Affinity partnerships, travel management companies (TMCs), and HR platforms are accelerating reach. Our competitive benchmarking reveals partnership models that materially accelerate adoption without requiring broad retail distribution footprints.
-
Assess captive and pooling options. For large multinational employers, alternative risk mechanisms (captives, pooled self‑insurance) increasingly complement market solutions — particularly where long‑tail medical evacuation and repatriation risks are price sensitive.
-
Plan for regulatory and compliance headwinds. Strengthened duty‑of‑care requirements and cross‑border data privacy rules influence contract language, incident reporting and insurer selection criteria.
What’s in the full report — practical, procurement‑ready content
-
Granular market sizing and forecasting (base year 2025; historical 2020–2025; forecast 2026–2032) with scenario analysis that quantifies the P&L impact of alternative travel recovery pathways.
-
Buyer personas and decision matrices for corporate (travel programs), SME buyers, and HR/T&E stakeholders — enabling procurement teams to map requirements to available product archetypes.
-
Insurer and product scorecards: multi‑criteria benchmarking that rates vendors on network reach, claims performance, digital integration capability, underwriting flexibility and cost of cover.
-
Commercial contracting playbook: sample service level agreements, KPIs, claims governance frameworks, and model clauses addressing duty of care, vendor liability and data protection.
-
Implementation roadmaps and quick‑win checklists for the first 90, 180 and 365 days following supplier selection.
-
Proprietary tools: ROI and total cost of ownership (TCO) calculators, supplier negotiation scripts, and a travel‑risk heat map tied to near‑term geopolitical and health risk scenarios.
-
Case studies and operational playbooks from leading enterprises that have reduced both cost and traveler friction while improving incident outcomes.
Note: This briefing highlights the report’s approach and strategic outputs. The full report contains the detailed segmentation tables, regional and application splits, and the complete vendor scorecards that are critical to procurement and product teams. Those proprietary datasets are gated in the full publication.
Competitive landscape — incumbent strengths and vectors of disruption
The market remains a mix of large global insurers, specialized international health players and agile niche operators. Leading incumbents combine breadth of global assistance networks with product modularity and enterprise sales capability. The competitive set we evaluate includes global multi‑line carriers with travel divisions, specialist international medical insurers, and newer entrants focused on digital distribution and rapid claims adjudication.
-
Allianz Partners — recognized for comprehensive international travel plans, deep assistance networks and an affinity/distribution play. Recent strategic moves (notably 2026 industry and partnership activity) underscore a push to consolidate affinity channels and raise product visibility in key markets.
-
International Medical Group (IMG) — a specialist in international medical and employer solutions; strength in employer‑centric offerings and medical evacuation services positions it well for corporate programs that prioritize comprehensive medical coverage.
-
Seven Corners and Travelex Insurance Services — both known for flexible, modular packages that appeal to frequent international travelers and corporate travel programs requiring rapid customization and short‑term trip protection.
-
Travel Guard (AIG) and Berkshire Hathaway Travel Protection — strong claims processes, global assistance capabilities, and enterprise sales teams; appropriate for clients seeking scale and standardized SLAs across jurisdictions.
-
Blue Cross Blue Shield Global Solutions — leverages global partnerships and local network access for group expat plans and multinational employee programs, attractive when centralized administration and global provider access are priorities.
Across these players, we observe three competing strategic models: (1) network and assistance dominance, (2) product modularity with API‑first distribution, and (3) partnership/affinity aggregation. Each model presents different implications for corporate buyers: cost predictability, service consistency, and integration complexity.
Recent market moves to watch (implications for 2026)
-
Partnership acceleration: High‑profile alliance activity and board‑level appointments in 2026 reflect accelerated efforts by incumbents to secure distribution and underwriting capacity for affinity partners. Buyers should expect more bundled offerings delivered via non‑traditional channels (TMCs, corporate benefits platforms).
-
Product convergence: Insurance products are increasingly merging travel medical, evacuation, wellbeing and trip disruption — creating consolidation opportunities but also requiring greater underwriting sophistication.
-
Digital claims and assistance: Carriers investing in real‑time assistance platforms reduce leakage and improve outcomes; firms should prioritize vendors with demonstrable API integration and regional operational capability.
How procurement and risk teams should act now
-
Run a rapid vendor rationalization: Use our scorecard to benchmark current suppliers versus target service outcomes and identify a short‑list for RFPs in Q1–Q2 2026.
-
Test hybrid product pilots: Co‑design pilot programs combining annual multi‑trip elements with short‑term top‑ups to capture both frequency and tail risk economics.
-
Align budgets to scenario pathways: Our scenario outputs translate macro CAGR and demand drivers into budgetary ranges—helping CFOs set prudent reserves for 2026 procurement cycles.
-
Strengthen contract language on duty of care: Update incident reporting, escalation and audit clauses to reflect heightened corporate and regulatory expectations.
Next steps and access
For strategy teams, procurement leads and insurer executives preparing for 2026, the full PW Consulting market report provides the empirical foundation and practical toolset needed to execute with confidence. The briefing shared here is a curated view of our findings designed to demonstrate the report’s strategic value. To access the full research, detailed segment tables, vendor scorecards and downloadable procurement templates, please visit the PW Consulting publications page or contact our research team directly to request the complete report and licensing options.
For detailed analysis of this topic, please visit the official page: International Business Travel Insurance Plans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Managed Security Services Market to More Than Double to USD86.78 Billion by 2032, Driven by 11.5% CAGR
By pmarketresearch, 2026-07-15
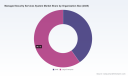
Managed Security Services System Market 2026: Strategic Imperatives from PW Consulting
PW Consulting today publishes an executive-level briefing drawn from our forthcoming Managed Security Services System Market research report (base year 2025, historical window 2020–2025, forecast 2026–2032). This briefing is designed to surface the strategic conclusions that will matter to CISOs, procurement leaders, and technology investors as they set priorities and budgets for 2026. It intentionally highlights the decision-grade insights and practical frameworks contained in the full report while preserving granular segmentation and vendor scorecard data to encourage direct access to the complete study.
Managed Security Services System Market
Why this report matters for 2026 decisions
-
Rapid, sustained market growth creates both opportunity and vendor risk. Our market model tracks a compound annual growth rate of 11.5% across the 2026–2032 forecast window, reflecting accelerating demand for outsourced detection, response, and managed resilience across cloud, edge, and hybrid estates. The total market has more than doubled since 2020 and is on a clear upward trajectory into the early 2030s.
Managed Security Services System Market -
Energy, regulation, and supply-side constraints are now first-order strategic variables. New regional bills, national pledges on ratepayer protections, and data‑handling rules are reshaping cost profiles for providers—and therefore contractual risks for buyers.
Managed Security Services System Market -
Service design is evolving from commodity monitoring to outcome contracts that combine MDR, orchestration (SOAR), XDR-enablement, and advisory vCISO capabilities. Buyers who demand outcome-based metrics and integrated resilience clauses will extract better economic and security outcomes.
What the full report delivers (practical, operational outputs)
PW Consulting structured this market study for active practitioners. The deliverables embedded in the full report are geared to convert insight into procurement and operational action:
-
Decision frameworks for build vs. buy vs. co-managed architectures—complete with a vendor-agnostic capability map and maturity-level gating criteria.
-
Vendor evaluation templates and RFP/RFI language calibrated to modern outcomes (MTTD/MTTR SLAs, false-positive economics, playbook coverage, and escalation-to-vCISO paths).
-
Service design blueprints for integrating MDR, SASE, managed firewall, threat intel, and vulnerability management into a single operational picture.
-
TCO and ROI models that account for energy and infrastructure pass-through risks, regulatory compliance costs, and transition expenses for cloud/hybrid migrations.
-
Tabletop exercise scenarios, incident response runbooks, and vCISO engagement templates for board-level reporting and continuous improvement cycles.
-
Negotiation playbooks and contract templates that capture indemnity placement, audit rights, data locality controls, and performance credits linked to containment outcomes.
Market dynamics shaping 2026
-
From fragmentation to selective consolidation: concentration metrics in our study show the market remains relatively fragmented compared with traditional telecom or cloud markets, with a small but growing set of established global providers and a diverse mid‑tier ecosystem driving innovation. This structure creates options for buyers: global scale or specialized regional/mid‑market expertise—each with different risk and price trade-offs.
-
Regulatory and infrastructure shocks are redefining commercial models. A wave of data center legislation and national-level energy pledges is already affecting provider cost bases and may lead to regionalized pricing, territorial deployment strategies, and new SLAs tied to energy resilience.
-
Product and platform differentiation is increasingly achieved via automation, AI-enabled detection orchestration, and certificate/lifecycle automation that reduce operational friction and containment time.
-
Service packaging is moving away from monolithic bundles to modular, outcome-oriented offers that allow buyers to scale detection, threat intel, and incident response independently.
Competitive landscape: strategic positions to watch
The managed security space in 2026 is defined by a mix of global systems integrators, network incumbents, pure‑play MSSPs, and specialist MDR firms. The full report includes vendor scorecards and comparative matrices; below is a high‑level strategic read on leading players and the capabilities buyers should evaluate.
-
IBM Security — Deep hybrid-cloud systems integration and a broad 24/7 managed services footprint. IBM plays to enterprise accounts that require tight integration across on-prem, private cloud, and public cloud estates. Key buyer consideration: strong orchestration and compliance capabilities but assess agility for small-to-mid-market pilots.
-
Verizon — Leverages global network infrastructure and carrier-grade DDoS/SASE capabilities. Best suited to organizations that prioritize integrated network security and operator-scale incident response. Key buyer consideration: network-coupled resilience vs. independence of cloud-native detection stacks.
-
LevelBlue — A pure-play MSSP with roots in established provider offerings; increasingly recognized in analyst research. Attractive for buyers seeking focused MDR capabilities and flexible deployment models (including FedRAMP-authorized services). Key buyer consideration: evaluate platform interoperability and threat intel sharing constructs.
-
Tata Communications — Emphasizes global reach and network-integrated monitoring. Strong for multinational customers with complex international estates that need unified operations and regional compliance workflows.
-
Secureworks — Built around the Taegis XDR platform; emphasizes analytics-driven detection and response. Best for enterprises aiming for advanced telemetry and threat hunting at scale.
-
Arctic Wolf — Marketed around a “Concierge Security” approach pairing human analysts with SOC technology. Effective for organizations seeking managed detection with strong customer engagement models and outcome SLAs.
-
eSentire — Expert‑led MDR with a focus on 24/7 operations and threat containment. Consider for workloads requiring proactive hunting and specialized incident playbooks.
Recent provider activity in early 2026 underscores how quickly capability stacks are evolving. Examples include an AI-enabled managed security operations suite launched by a major supplier, recognition of specialized SOC capabilities tied to major cloud platforms, and platform launches that automate previously manual certificate and trust processes. These moves accelerate time-to-detection improvements and push buyers to re-assess incumbent contracts.
Regulatory tailwinds and operational risk
-
New state and national energy and data center regulations are material to procurement. Buyers should quantify exposure to energy pass-throughs, geographic data residency requirements, and potential limitations on cross-border incident handling.
-
Legislation that targets bulk data transactions and enhanced controls for foreign-party access imposes new technical and contractual obligations on MSSPs and their customers—particularly for multi-jurisdictional operations.
-
Procurement teams must now demand stronger evidence of regulatory posture from providers—technical attestations, third‑party audits, and contractual remedies tied to noncompliance.
Actionable recommendations for 2026
-
Adopt an outcomes-first procurement approach. Define detection and containment outcomes (MTTD/MTTR/containment rate) and build payment/success milestones around them instead of pure headcount or device counts.
-
Include energy and infrastructure clauses in contracts. Require transparency on provider energy exposure and contingency plans for grid disruptions or tariff shifts.
-
Run modular pilots that validate AI-assisted detection and certificate automation before full-scale migration. Use those pilots to stress-test incident escalation pathways and vendor-integrated SOAR playbooks.
-
Mandate cross-border handling and data residency controls that align with your regulatory footprint and the evolving Bulk Data Rule-like regimes.
-
Require vendor openness on telemetry and integration: insist on standard APIs, event normalization, and data export rights to avoid lock-in.
-
Create a two‑track sourcing strategy: secure global coverage for core resilience while commissioning boutique specialists for threat hunting, offensive security, and industry-specific intelligence.
Methodology and signal confidence
PW Consulting’s market sizing and forecasts combine bottom‑up vendor revenue modeling, demand-side surveys, and trend extrapolation from 2020–2025. The 2026–2032 forecasts are stress‑tested with scenario analyses—including energy shock, rapid regulation, and accelerated cloud adoption—to produce a central case with a measured confidence interval. Our competitive analysis integrates public filings, direct vendor interviews, and third-party validation to reflect both capability and market access.
Next steps: where to get the complete intelligence
This briefing synthesizes the strategic imperatives from PW Consulting’s Managed Security Services System Market research. The full report contains granular segmentation by geography, service type, organization size, detailed vendor scorecards, country‑level regulatory matrices, downloadable RFP templates, TCO spreadsheets, and playbooks referenced above. To access the complete analysis and the practical toolset for 2026 procurement and operating-model decisions, please visit our report page or contact a PW Consulting industry analyst.
PW Consulting remains available to run executive workshops, vendor selection programs, and implementation oversight to convert this market intelligence into measurable security and business outcomes.
For detailed analysis of this topic, please visit the official page: Managed Security Services System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: FC‑BGA Package Substrates Market Poised for 15% CAGR Through 2032
By pmarketresearch, 2026-07-13
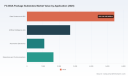
FC-BGA Package Substrates Market: Strategic Imperatives for 2026 — PW Consulting Insight
Executive summary
As semiconductor architectures pivot toward extreme I/O density and advanced compute, the flip-chip ball grid array (FC‑BGA) package substrate market is undergoing one of the most consequential growth phases in its history. PW Consulting’s new FC‑BGA Package Substrates Market report (base year 2025) finds that the global market has expanded rapidly from a modest multi‑billion USD base in 2020 to a significantly larger market by 2025, and is forecast to continue a high‑growth trajectory through 2032 at a compound annual growth rate (CAGR) of approximately 15% for the 2026–2032 horizon. Our bottom‑up market model projects total market value crossing key inflection points in 2026 and nearly tripling by 2032 under the base case — dynamics that will materially shape capital allocation, supplier strategy, and industrial policy throughout 2026 and beyond.
FC-BGA Package Substrates Market
Why this matters for 2026 corporate decision‑making
- Capacity timing is strategic: Long lead times and concentrated capacity mean that openings made in 2026 will determine supply balances and pricing power into the next decade. Our scenario analysis shows that investment decisions taken in 2026 produce outsized effects on utilization and delivery windows through 2028–2030.
- Raw materials and input risk are binding constraints: ABF build‑up films, high‑end copper foil, and CCL availability are now first‑order drivers of cost and throughput. Price shocks and extended supply lead times are already being observed and amplify the consequences of delayed capacity expansions.
- Customer segmentation is shifting: Data center, HPC, and AI workloads are the principal demand engines for advanced FC‑BGA substrates, while adjacent segments (networking, automotive, and edge compute) create complementary demand patterns that reward flexible capacity and qualification pathways.
Market trajectory and macro view
PW Consulting’s multi‑scenario forecast integrates historical trends (2020–2025) and forward modeling for 2026–2032. Industry recovery and reinvestment lifted the market from its 2020 base to a substantially larger market by 2025, with 2026 representing a critical acceleration point in absolute market value. Under our central scenario, the market grows at roughly 15% CAGR over 2026–2032, with 2026 marking the transition from the immediate post‑cycle replenishment phase into a sustained expansion driven by AI servers, GPUs, and high‑layer count requirements.
FC-BGA Package Substrates Market
Supply‑side dynamics: capacity, concentration and strategic chokepoints
- Concentration and scale matter: The supply base is moderately concentrated; the top three suppliers command a substantial share of market capacity, and the top five become dominant when capacity expansions are considered. This concentration accelerates during cyclical tightness and increases the strategic value of securing preferred supplier status.
- New lines and geographic shifts: Recent capacity announcements and launches — including major production starts and greenfield expansions in multiple jurisdictions — will reshape regional supply balances. These moves are tactical responses to both customer requirements and geopolitical incentive structures, and they materially influence lead times and pricing across 2026.
- Raw material friction points: Price increases for ABF films, extended lead times for CCLs, and a widening gap in high‑end copper foil availability create multi‑layered bottlenecks. These input constraints imply that nominal substrate capacity is not equivalent to effective throughput unless raw material contracts and inventory strategies are synchronized.
Competitive landscape: who matters and why
Leading global substrate manufacturers have differentiated along technical capability, scale, and customer proximity. Key players analyzed in the report include long‑standing Japanese manufacturers renowned for ultra‑fine microfabrication; Taiwanese producers that balance volume with rapid qualification cycles; Korean groups investing heavily to capture AI substrate demand; European specialists targeting niche high‑reliability applications; and a growing set of Chinese and regional suppliers pursuing volume and cost leadership.
FC-BGA Package Substrates Market
- Manufacturers with advanced microfabrication and ultra‑fine wiring capabilities are best positioned to serve the highest layer‑count, highest I/O density packages needed by AI and HPC customers.
- Large Taiwanese players remain pivotal for server and GPU supply chains due to scale and established customer relationships.
- Korean investments — particularly new greenfield capacity targeted at high‑growth compute centers — are rapidly changing the competitive map.
- European and select regional suppliers are capitalizing on premium, high‑reliability segments and localized demand for automotive and industrial electronics.
Notable recent industry developments include production line launches and capacity expansion programs by global incumbents, and multi‑billion‑KRW scale investments to add FC‑BGA capacity in lower‑cost manufacturing jurisdictions. These moves validate our market view that substrate capacity will be a primary battleground in 2026.
Segment and raw‑material intelligence (what we include in the report)
PW Consulting’s full report provides a practical, operational playbook designed for procurement teams, product planners, and corporate strategy groups. Key deliverables include:
- Granular demand model (bottom‑up by package type and application) with vintage demand curves for 2020–2025 and scenario projections for 2026–2032.
- Supply capacity database including age, technology node capability, planned expansions, and ramp profiles — enabling accurate lead‑time and utilization forecasts.
- Input supply assessment for ABF films, CCLs, and high‑end copper foil, including supplier concentration, lead‑time elasticity, and price shock sensitivity.
- Supplier scorecards and qualification roadmaps to support accelerated onboarding or dual‑sourcing for mission‑critical programs.
- Contract negotiation playbook — practical terms and protective clauses designed for periodic shortages, force majeure, and long lead‑time management.
- Scenario and stress tests for pricing, capacity shutdowns, tariffs, and raw‑material supply shocks, with quantified P&L impacts under multiple cases.
- Strategic M&A and J‑V playbook tailored to substrate value chain consolidation and capability acquisition opportunities.
To preserve commercial value for clients, our public summary intentionally withholds certain granular split figures and price trajectories — these are contained in the full report and the downloadable data annex.
Strategic implications and recommended actions for 2026
- Prioritize lead‑time management: Establish multi‑tiered supplier agreements with capacity reservations and clear ramp milestones. For companies dependent on high‑layer count substrates, securing allocation in 2026 is more valuable than spot‑market purchases later.
- Hedge raw‑material exposure: Negotiate long‑term procurement contracts for ABF films and premium copper foil, and evaluate strategic inventory positioning. Joint procurement or off‑take agreements with substrate makers can reduce price volatility and secure throughput.
- Invest selectively in qualification: Accelerate parallel qualification tracks with at least two qualified suppliers for each strategic product family. Passing qualification earlier in 2026 will unlock capacity priority in 2027–2028 cycles.
- Reconsider vertical integration and partnerships: Where scale and margin dynamics justify, explore partial vertical integration or exclusive co‑investment with substrate manufacturers to secure technological roadmaps and priority capacity.
- Localize with eyes open: Geography matters — incentives, tariffs, and industrial policy can materially shift landed costs. Use our scenario maps to model total landed cost under varying tariff regimes and incentive packages before siting decisions.
- Prepare for consolidation: Industry profit pools and capacity imbalances make M&A attractive. Identify targets with complementary technology (e.g., ultra‑fine wiring capability or specialized build‑up processes) to accelerate time to market.
Risk matrix: what keeps supply chain executives awake at night
- Input price spikes: Historic and recent ABF film price increases demonstrate that raw‑material inflation can outpace substrate pricing adjustments, squeezing margins.
- Lead‑time escalation: Extended lead times for CCLs and substrate production have been observed during peaks, with episodes of beyond‑30‑week delivery timelines in prior cycles.
- Geopolitical/tariff risk: Tariff regimes on advanced substrates and critical inputs are reshaping cost competitiveness and driving strategic re‑routing of supply chains.
- Capacity under‑utilization: Premature capacity additions without raw‑material assurance can create stranded assets and depressed returns.
What PW Consulting’s report enables for 2026
For executives preparing 2026 budgets and capital plans, our FC‑BGA report provides actionable intelligence to convert growth forecasts into executable supply strategies. Clients will receive the data and tools to quantify the trade‑offs between speed to market, cost, and risk exposure — enabling precision in negotiating supplier commitments, scheduling capital projects, and shaping governance for sourcing critical substrates.
Next steps and access
PW Consulting’s public brief is intentionally selective. The detailed demand and supply matrices, supplier scorecards, contract templates, and model workbooks — including our near‑term allocation model and upside/downside scenarios — are included in the full report and protected data annex. Organizations planning capacity decisions, procurement negotiations, or strategic investments in 2026 should consult the full deliverable to translate the high‑level imperatives above into executable plans.
For access to the complete FC‑BGA Package Substrates Market report, model license, and bespoke advisory engagements tailored to 2026 decision cycles, please visit PW Consulting’s report page or contact our advisory desk for a guided walkthrough of the findings and scenario tools.
For detailed analysis of this topic, please visit the official page: FC-BGA Package Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: PLC Software Market to Expand at a 7.15% CAGR — New Insights Reveal Robust Growth Ahead
By pmarketresearch, 2026-07-13
Plc Software Market 2026: Strategic Imperatives for Decision-Makers — PW Consulting Outlook
As enterprises accelerate digital transformation across manufacturing, energy, and critical infrastructure, PLC (Programmable Logic Controller) software is evolving from a niche automation tool into the operational backbone of industrial intelligence. PW Consulting’s latest Plc Software Market report (base year 2025; historic window 2020–2025; forecast 2026–2032) synthesizes market dynamics, vendor positioning, regulatory shifts, and actionable playbooks that senior executives and procurement leads need to set strategy in 2026. The market is projected to grow at a 7.15% CAGR through the forecast period, building on a multi-year recovery and steady expansion that culminates in a sizable addressable market by 2032.
Plc Software Market
Why this report matters for 2026 decisions
-
Timing: 2026 is a pivot year. Organizations are moving from pilot deployments of AI, edge compute, and cloud-connected OT to enterprise-grade rollouts. Decisions made now—vendor selection, cybersecurity design, and integration architecture—have multi-year cost and uptime consequences.
Plc Software Market -
Signal vs. noise: The PLC software landscape is being reshaped by fast-moving innovations (GenAI-assisted engineering, software-defined automation, PC-based control stacks) and tighter regulatory requirements. Our report separates durable structural trends from transient vendor announcements.
Plc Software Market -
Actionability: The study is built around decision-support assets—vendor scorecards, procurement checklists, ROI templates, and migration roadmaps—so that leadership can move from strategy to execution without re-inventing analysis.
Market trajectory and macro context
After a period of uneven growth in the early 2020s driven by supply-chain disruptions and cyclical capex patterns, the Plc Software market re-stabilized, posting consistent expansion into 2025. In nominal terms, the global market reached a multi-billion-dollar scale in 2025 (reported in USD, revenue unit: Million), and under the central scenario we model a continuation of investment momentum through 2032—supported by an annualized growth rate of 7.15%. This trajectory is underpinned by three structural forces: the industrial adoption of AI/analytics at the control layer, the push to standardize engineering workflows across geographically distributed operations, and the need to remediate OT cyber risk at scale.
What’s inside the report — practical, executable content
-
Deep market synthesis: trend narratives, demand drivers, and scenario-based forecasts (2026–2032) that quantify upside and downside risk under alternative macroeconomic and regulatory outcomes.
-
Vendor benchmarking: qualitative and quantitative scorecards across product breadth, engineering ergonomics, interoperability, cybersecurity posture, cloud integration, and enterprise licensing terms.
-
Procurement and deployment playbooks: contract negotiation checklists (including SLAs for engineering automation and security), phased migration roadmaps for brownfield sites, and cost modeling templates calibrated to control-system lifecycles.
-
Security and compliance modules: OT vulnerability management frameworks, incident response runbooks, and compliance impact matrices for emerging rules—critical given new regulations affecting automated decision-making and data handling.
-
Use-case libraries: validated case studies and reference architectures for high-impact applications (e.g., synchronous motion control, multi-site batch orchestration, remote lifecycle management) with KPIs and estimated payback horizons.
-
Investment guidance: M&A and partnership candidate profiles and a risk-return lens for acquiring engineering tools, security middleware, or platform capabilities.
Competitive landscape: strategic profiles and implications
The Plc Software ecosystem is a mix of integrated industrial conglomerates, specialist controls vendors, and independent software platforms. Market concentration is meaningful: the top three vendors hold a sizable share, and the top five account for a dominant majority—an important consideration for ecosystem lock-in and negotiating leverage.
-
Siemens AG (Munich) — Siemens continues to lead with a full-stack strategy that integrates PLC programming, simulation, and digital-twin capabilities. Its TIA Portal and STEP 7 family are migrating GenAI assistants into engineering workflows, improving first-pass code quality and shortening commissioning cycles. Strategic takeaways: Siemens is the natural choice where integrated digital-enterprise narratives and manufacturing IT alignment are prioritized.
-
Rockwell Automation (Milwaukee) — Rockwell’s Studio 5000 and the FactoryTalk ecosystem remain deeply entrenched in North American industrial ecosystems, with strengths in Ethernet/IP networking and an extensive partner channel. Strategic takeaways: for operations with North American supply chains and existing Rockwell PLC fleets, incremental modernization via Rockwell’s ecosystem minimizes disruption.
-
Schneider Electric (Rueil-Malmaison) — Schneider’s EcoStruxure suite targets energy management and distributed automation. Its emphasis on IEC standards and cloud integration is attractive for utilities and energy-heavy industries. Strategic takeaways: Schneider is a compelling option for organizations linking PLC modernization to energy optimization programs.
-
Mitsubishi Electric (Tokyo) — With MELSOFT and GX Works, Mitsubishi focuses on high-performance control for automotive and semiconductor manufacturing in Asia-Pacific. Strategic takeaways: leaders in high-speed discrete production should prioritize Mitsubishi where cycle-time optimization is a core KPI.
-
Beckhoff Automation (Verl) — Beckhoff’s PC-based TwinCAT stack pushes the boundary of runtime performance and flexible engineering, particularly where OEMs and integrators favor software-defined control. Strategic takeaways: consider Beckhoff for architectures that require tight integration of motion, robotics, and AI on industrial PCs.
-
ABB Ltd. (Zurich) — ABB’s Automation Builder (CODESYS-based) complements its drives and motion portfolio, making it effective for infrastructure and process automation. Strategic takeaways: ABB remains a strong proposition where scale and cross-domain integration are needed.
-
CODESYS Group (Kempten) — As an independent IEC 61131-3-compliant platform, CODESYS is a common denominator across diverse hardware, enabling multi-vendor strategies and reduced lock-in. Strategic takeaways: CODESYS is a strategic hedge for enterprises targeting platform neutrality and flexible supplier mixes.
Recent developments that change the calculus
-
AI and engineering automation are accelerating. Industry showcases and vendor updates in 2026 emphasized AI-assisted code generation, integrated code analysis, and lifecycle management—capabilities that materially reduce commissioning time and human error.
-
Open, software-defined automation continues to gain traction. Software Defined Automation’s 2026 product launch and Beckhoff’s 30-year milestone underscore a market shift toward abstracted control logic and multi-vendor runtime environments.
-
Regulatory and legal shifts are now part of procurement risk. California’s CPPA regulations (effective January 2026) and U.S. DOJ rules on bulk data transactions require risk assessments, cybersecurity audits, and explicit governance for ADMT (Automated Decision-Making Technology) used in industrial software.
-
OT cybersecurity is moving from checklist to investment. Rising PLC-targeted threats mean organizations must bake vulnerability management and secure update pipelines into vendor agreements—no longer optional add-ons.
Strategic recommendations for 2026
-
Adopt a platform-flexible procurement stance. Prioritize vendors that support IEC standards, multi-vendor runtimes, and open APIs to avoid single-supplier lock-in and to future-proof engineering stacks.
-
Elevate OT cybersecurity to board-level priority. Require vendor transparency on vulnerability discovery, patch timelines, and secure update mechanisms. Factor in compliance costs from CPPA and DOJ rules when modeling TCO.
-
Prioritize AI-enabled engineering where ROI is demonstrable. Use pilot programs to quantify reductions in commissioning time and error rates; then scale where payback is shortest.
-
Build a phased modernization roadmap. Start with remote lifecycle management and version-control tooling for distributed sites, then standardize on simulation and digital-twin capabilities to shorten test cycles.
-
Insist on contractual SLAs for engineering tools. Negotiate clear KPIs for maintainability, backward compatibility, and interoperability to mitigate upgrade risk.
-
Invest in skills and change management. The real barrier to value capture is often organizational: train control engineers in modern toolchains and create cross-functional teams that bridge IT, OT, and cybersecurity.
Conclusion: how PW Consulting’s report helps you act
For executive teams preparing budgets, evaluating acquisition targets, or re-platforming industrial control systems in 2026, the Plc Software Market report is designed to be a pragmatic guide. It offers the strategic context to prioritize investments, the vendor analysis to scope partner selection, and the implementation artifacts—checklists, scorecards, and financial templates—needed to move from decision to execution.
We intentionally keep granular regional and application breakdowns, and proprietary vendor share tables, exclusive to the full report—this is where the model scenarios, downloadable spreadsheets (USD, revenue unit: Million), and split-level market data live. To access the complete datasets, detailed segmentation, and the operational toolset that will support your 2026 roadmap, please visit the report page on PW Consulting’s website.
For detailed analysis of this topic, please visit the official page: Plc Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AI in Telecommunications to Grow at 24.85% CAGR, Market Poised to Reach USD 59.19 Billion by 2032
By pmarketresearch, 2026-07-13
Artificial Intelligence in the Telecommunication Market: Strategic Imperatives for 2026
Executive summary
As telecommunications operators accelerate AI investments, the market is shifting from experimentation to enterprise-scale deployment. PW Consulting’s new market study — Artificial Intelligence in the Telecommunication Market (base year 2025) — maps this transition, combining a rigorous historical analysis (2020–2025) with a scenario-based forecast through 2032. The headline: the market has moved from early-adopter growth into a compounding expansion phase, with an expected compound annual growth rate of 24.85% over the forecast window. For strategy teams budgeting and prioritizing in 2026, the report provides the decision-grade intelligence needed to reconcile commercial opportunity, regulatory exposure, and operational readiness — without sacrificing pragmatic playbooks for execution.
Artificial Intelligence In The Telecommunication Market
Why 2026 is a pivot year
-
Capital allocation decisions in 2026 will determine who leads the next wave of network autonomy. Our analysis shows the market scale already reached a critical inflection point in 2025 and is forecast to continue on a steep trajectory through 2032. Executives face a narrow window to convert pilots into differentiated, scalable platforms that capture disproportionate value.
Artificial Intelligence In The Telecommunication Market -
The confluence of technology maturation (agentic AI, telco-tailored models, GPU-accelerated stacks), commercial trials, and tightening energy and regulatory constraints makes 2026 the year to shift from “proof of concept” to “proof of value.” Decisions made this year on architecture, partner choice, and data governance will materially influence cost curves and go-to-market speed over the next three to five years.
Artificial Intelligence In The Telecommunication Market -
Market concentration metrics indicate a moderately dynamic competitive landscape where a handful of platform and infrastructure players can shape industry standards — but there remains space for focused, domain-specialized entrants to capture value through vertical differentiation and operations-led propositions.
Market trajectory and what it means for investment timing
Our topline market model traces rapid expansion from the early 2020s into a large addressable market by the early 2030s. The sector’s compound annual growth rate of 24.85% reflects an accelerating cadence of deployments across network optimization, customer analytics, fraud mitigation, and adjacent enterprise offerings. Practically, this means that investments in AI-enabled network orchestration, edge inference platforms, and AI-driven customer experience platforms will see compounding returns — but timing and architecture choices matter.
Companies that front-load efforts to standardize data schemas, instrument monitoring, and create reusable model pipelines are positioned to compress time-to-value. Conversely, late movers who prioritize point solutions without operational integration risk becoming perpetual pilots with sub-scale economics.
What decision-makers will find in the report (practical contents)
-
Actionable playbooks for pilot-to-production: step-by-step deployment sequencing, acceptance criteria, and a maturity model tailored to network operators, data service providers, and managed service partners.
-
Commercial frameworks and ROI templates to quantify total cost of ownership (TCO), capital versus operational trade-offs for edge vs. centralized inference, and scenario-based NPV models that account for energy and regulatory externalities.
-
Vendor assessment toolkits and vendor scorecards: a repeatable methodology to evaluate infrastructure providers, model vendors, systems integrators, and hyperscalers across capability, integration risk, and strategic alignment.
-
Risk matrices and compliance playbooks addressing energy, siting, and data governance. These include mitigation paths for escalating data center operating costs and state-level regulatory constraints.
-
Partner ecosystem blueprints: how to structure revenue-sharing, IP ownership, and integration responsibilities between telcos, cloud providers, chipmakers, and specialist AI vendors.
-
A library of operator case studies and tested KPIs for network optimization, predictive maintenance, fraud mitigation, and customer lifetime-value uplift — intentionally aggregated at sector level to preserve strategic confidentiality while demonstrating measurable outcomes.
Competitive landscape — strategic implications
The competitive map is shaped by two sets of players: infrastructure and compute platform leaders, and incumbent telecom equipment and software suppliers who are embedding AI across network domains. Our competitive analysis synthesizes product trajectories, partnership patterns, and go-to-market moves across the leading companies.
-
NVIDIA continues to define the high-performance compute layer for telecom AI. Its GPU-accelerated stacks, telco-specific model blueprints, and growing set of live AI-RAN trials with major carriers position it as the preferred choice for operators prioritizing performance-intensive, low-latency workloads.
-
Ericsson and Nokia are competing on AI-native network strategies, focusing on integrating intelligence into RAN and orchestration layers. Their emphasis on autonomous operations and software-defined architectures is aimed at reducing operational expense through automation and energy-aware scheduling.
-
Huawei’s full-stack AI Core Network proposition is designed for operators seeking vertically integrated solutions and deep on-premises intelligence. Its product direction underscores the strategic split between open ecosystem approaches and vertically integrated offers.
-
Cloud and platform providers — Microsoft and IBM — are pushing differentiated value through managed AI services, telecom-specific data platforms, and pre-integrated tools for analytics, customer experience, and fraud detection. Their scale in cloud and enterprise services makes them natural partners for operators that want to reduce internal build cost and accelerate deployment.
-
Cisco and other networking incumbents are embedding AI capabilities into hardware and network services, offering hybrid paths that combine traditional networking investments with new AI workloads.
-
Large operators such as AT&T are increasingly operating as both buyers and orchestrators — trialing agentic AI for customer service and network operations while actively partnering in AI-RAN and edge initiatives.
Recent market signals and their strategic read
-
Industry disclosures in early 2026 — including a major vendor report citing widespread planned increases in telco AI budgets and multiple vendor-operator partnerships for live AI-RAN trials — signal that pilots are moving into network-integration phases. This validates a market dynamic where competitive differentiation will be realized through integration depth and operational excellence rather than feature lists alone.
-
Public MoUs and strategy unveilings highlight longer-term commitments to AI-powered RAN and autonomous networks through the second half of this decade. These agreements reduce technology adoption uncertainty but raise questions about vendor lock-in and multi-vendor interoperability — critical governance considerations addressed in our procurement playbooks.
-
Product launches for AI Core Network capabilities show suppliers are racing to offer end-to-end generative and agentic network functionality. Operators must assess where to place strategic bets: adopt integrated stacks for speed-to-market or assemble best-of-breed stacks to preserve flexibility.
Energy, regulation and infrastructure — the under-appreciated constraints
Energy and regulatory factors are fast becoming determinative for AI deployment economics. For example, U.S. data center electricity consumption was reported at roughly 176 TWh in 2023 and global data center demand approached 415 TWh in 2024, with forecasts indicating a sharp increase in AI-driven load. Acute regional pressures — from state-level bills regulating water, siting and energy to federal commitments that shift the cost of new generation infrastructure onto hyperscalers — materially affect deployment costs and timeline risk.
Recent market monitoring has also revealed volatile wholesale power markets in certain grids, with quarter-over-quarter price escalations tied in part to data center demand. For telcos and their partners, this translates into immediate strategic questions: Where should inference and training workloads be sited? Which workloads must remain on-premises for latency or sovereignty reasons? And how should contracts and TCO models be structured to reflect the true cost of compute and energy?
How the report informs 2026 decisions — three practical change levers
-
Strategic architecture decisions: Use our decision matrices to choose between centralized cloud, distributed edge, and hybrid topologies based on workload profiles, latency, and regulatory constraints.
-
Commercial negotiations and partner governance: Implement the vendor scorecards and contract templates to secure favorable data ownership, SLAs, and infrastructure-cost-sharing arrangements — and to de-risk vendor lock-in.
-
Energy and compliance hedging: Apply energy-impact scenarios and regulatory playbooks to anticipate siting constraints, capital expenditure timing, and to qualify incentives or mitigation strategies before committing to large-scale deployments.
Final note — what we intentionally withhold here
This briefing highlights strategic contours and practical implications; it deliberately omits detailed regional, solution, and end-user level splits that underpin our proprietary models. Those subsegment allocations, receiver-specific growth curves, and granular revenue figures are included in the full PW Consulting report and accompanying data annex — essential inputs for transaction diligence, procurement negotiation, and detailed capex planning.
Call to action
For executive teams preparing 2026 budgets and three-year roadmaps, PW Consulting’s full report provides the calibrated, operationally focused intelligence required to move from experimentation to scale. Access to the complete dataset, vendor scorecards, ROI templates, and deployment playbooks is available on our publication page. Use the report to align internal stakeholders, stress-test supplier choices, and lock in deployment sequences that capture first-mover operational advantage without incurring undue energy or regulatory risk.
For detailed analysis of this topic, please visit the official page: Artificial Intelligence In The Telecommunication Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AC Capacitors Market Poised to Hit USD 3,970.16 Million by 2032 at a 4.85% CAGR — Asia Pacific Leads with USD 1,231.5M
By pmarketresearch, 2026-07-13
AC Capacitors Market 2026: Strategic Insights for Decisions that Matter
PW Consulting’s latest market intelligence on the AC capacitors sector combines rigorous historical analysis (2020–2025), a clearly defined 2026 base, and scenario-driven forecasts through 2032. The global AC capacitors market—measured in USD Million—registered steady growth to a base-year size of USD 2,850.0 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 4.85% across the 2026–2032 forecast window. By 2032 the market is expected to approach roughly USD 3,970 Million under PW Consulting’s central scenario. This briefing unpacks the strategic levers, risk vectors, and competitive dynamics that should shape executive decisions in 2026, while preserving the granular segment intelligence for subscribers who require transaction‑grade detail.
Ac Capacitors Market
Why this report matters for 2026 decision-making
- Timing: 2026 is a hinge year. With legacy industrial demand converging against accelerating electrification and efficiency regulations, procurement cycles, product roadmaps, and supplier strategies decided now will lock in cost and capability profiles for multiple years.
- Scale and momentum: The market’s trajectory from 2020 through 2025 demonstrates resilience across end markets, and our forecast to 2032 quantifies the opportunity and structural shifts executives must anticipate when allocating capital or resizing supply footprints.
- Practicality: PW Consulting’s deliverables are built to be operational—model-ready forecasts, supplier risk heat maps, scenario-adjusted price indices, and prioritized action plans tailored to common buyer and supplier archetypes.
Market trajectory: what the headline numbers reveal
Readers should treat the headline market numbers as directional imperatives. After a steady expansion to USD 2,850.0 Million in 2025, our central forecast anticipates consistent growth through the 2026–2032 period at a 4.85% CAGR, reflecting a mix of replacement demand in legacy HVAC and motor sectors, coupled with incremental gains in power-electronics and emerging industrial applications. The trajectory implies that companies with clear product differentiation, resilient supply chains, and the ability to capture adjacent power-electronics demand will outperform market averages.
Ac Capacitors Market
Two quick strategic implications flow from this profile: first, mid‑tier manufacturers and component buyers should plan capital and contract cycles around multi‑year demand steadiness rather than short-term spikes; second, diversification into power‑electronics‑grade film technologies and higher‑temperature/voltage ratings is warranted for players seeking premium positioning.
Ac Capacitors Market
Supply chain dynamics that will shape 2026 outcomes
- Raw material cost and availability: Aluminum foil and polypropylene film dynamics are the most immediate cost drivers. Recent reports indicate aluminum foil prices have risen in key production regions, and polypropylene film supply is under pressure from competing demand in packaging and electric-vehicle segments. These trends compress margins for commoditized product lines and create arbitrage opportunities for differentiated film formulations.
- Lead-time inflation: Average lead times for passive components moved to roughly 19 weeks as of late 2025. That cadence degrades responsiveness for OEMs with lean inventories, increasing the importance of buffer strategies, multi‑sourcing, and advance purchase agreements.
- Quality bottlenecks: High‑purity aluminum foil suppliers have reached etching-capacity limits in some regions, raising the strategic value of vertical integration or long-term agreements with specialty foil suppliers for firms competing in high-reliability segments.
Competitive landscape: incumbents, moves, and strategic postures
The AC capacitors market demonstrates moderate concentration: the top three companies account for approximately 28.5% of market share (CR3), while the top five reach about 39.2% (CR5). That structure indicates room for regional champions and niche specialists to prosper alongside global players.
- Barker Microfarads (BMI) — Hillsville, VA, USA: BMI’s positioning in high‑reliability motor start and run film capacitors for HVAC and motor applications is a durable asset. For 2026, BMI’s strategic playbook should focus on leveraging service, customization, and inventory responsiveness to capture premium aftermarket and retrofit demand.
- AmRad Engineering — USA: AmRad’s focus on USA-made motor run capacitors, including dual‑run offerings for HVAC, positions it well amidst resurgent onshoring and supplier‑diversification trends. Its strategic pathway should emphasize certified manufacturing capacity and targeted OEM partnerships.
- Cornell Dubilier Electronics (CDE) — Liberty, SC, USA: CDE’s broad AC film motor run and power film capacitor portfolio, combined with recent product introductions aimed at harsher environments, signals a push into higher-margin, high-reliability power-electronics niches. Expect continued product innovation and selective vertical integration.
- TDK (EPCOS) — Japan/Germany: TDK’s global scale and regulatory-compliant MotorCap portfolio are complemented by recent product launches (notably an extended X2 safety film capacitor portfolio introduced in early 2026 supporting higher AC ratings). TDK’s R&D cadence and cross-regional footprint make it a strategic standard-bearer for OEMs requiring certified, industrial-grade solutions.
- Vishay Intertechnology — Malvern, PA, USA: Vishay’s capabilities in AC film, motor run, and high‑voltage power capacitors give it an advantage in industrial and power-electronics conversions. For 2026, Vishay’s best opportunities lie in bundling capacitors with broader power modules and leveraging global distribution channels.
Recent product activity—examples include TDK’s February 2026 expansion of its X2 safety film capacitor family and Cornell Dubilier’s August 2025 release of a high‑temperature DC link capacitor—highlights a trend toward higher-voltage, higher-temperature designs suitable for demanding environments and adjacent power-electronics applications. These moves are consistent with the market’s gradual tilt toward performance differentiation.
Practical components of the PW Consulting report
The full report is structured to inform operational, commercial, and M&A decisions. Key contents include:
- Methodology and transparent market-accounting frameworks that reconcile top-down macro indicators with bottom-up supply-side intelligence.
- Historical time series (2020–2025) and scenario-based forecasts (2026–2032), with model files ready for client re-parameterization.
- Supply chain heat maps highlighting exposure to raw‑material volatility, lead‑time risk, and single‑source dependencies.
- Price and input-cost modeling aligned with polypropylene and aluminum‑foil dynamics, and sensitivity analyses that quantify margin impacts under alternative commodity regimes.
- Competitive benchmarking and capability matrices for incumbent suppliers and disruptive challengers, including technology roadmaps and go‑to‑market archetypes.
- Commercial playbooks: supplier selection checklists, negotiation levers, and procurement-timing heuristics designed for OEMs, contract manufacturers, and Tier‑1 suppliers.
- M&A and partnership diagnostics: valuation multiples, integration pitfalls, and synergy capture templates tailored to capacitor-facing assets.
How senior leaders should act in 2026
- Procurement leaders: Lock prioritized volumes on strategic film types now while maintaining optionality through secondary suppliers. Structure contracts to share commodity upsides or to include indexed pricing bands to protect margins.
- Product and engineering: Prioritize modular capacitor platforms that can be tuned for higher temperature/voltage ratings with limited requalification cost—this reduces time‑to‑market for OEMs reacting to new industrial and power-electronics requirements.
- Operations and supply chain: Reassess lead-time buffers and inventory policies with the expectation of extended procurement cycles; invest in forecasting fidelity and supplier development where high-purity foil or specialty film is a bottleneck.
- Corporate development: Evaluate tuck-ins that add differentiated film technologies or regional manufacturing capacity, focusing on assets that shorten qualification cycles for key OEMs.
Readership note — what we are intentionally withholding here
This communication is a strategic preview intended to demonstrate analytical depth while preserving the transactional intelligence that makes PW Consulting’s full report a decision-enabling asset. We have therefore intentionally omitted detailed segment-level splits, specific regional revenue breakdowns, and granular application‑level dollar values from this release. Subscribers to the complete report receive the full segmentation matrix, disaggregated time-series, and downloadable model files required to execute procurement, engineering, and M&A plays in 2026.
Closing: the actionable edge for 2026
For executives weighing capital allocation, supplier selection, or product roadmaps in 2026, the AC capacitors market presents a balance of steady growth and targeted disruption. The headline market expansion to roughly USD 3,970 Million by 2032 (central scenario) at a 4.85% CAGR masks meaningful shifts in supplier economics, technology thresholds, and lead-time realities that will determine winners and laggards. Companies that pair disciplined procurement strategies with selective engineering investments in higher-performance film and safety-rated capacitors will capture disproportionate value.
To access the full dataset, proprietary segmentation, scenario models, and supplier dossiers that underpin these conclusions, please consult PW Consulting’s full Ac Capacitors Market report. The complete deliverable is engineered to convert insight into executable plans for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Ac Capacitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Integrated Optical Delay Line Market to Expand at a 7.5% CAGR, Fueling Growth in Defense, Telecommunications and Data Centers
By pmarketresearch, 2026-07-13
Integrated Optical Delay Line Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on Integrated Optical Delay Lines (IODLs) synthesizes five years of historical performance and a seven-year forecast to 2032, delivering a concise strategic lens for C-suite executives, product leaders, and investors preparing decisions in 2026. This briefing presents the high‑level market trajectory, critical technology and supply‑chain inflection points, and the competitive moves that will shape opportunities — while preserving the full segment-level granularity for subscribers to the full report.
Integrated Optical Delay Line Market
Market snapshot — a market in steady expansion
At the macro level, the IODL market is transitioning from research‑led experimentation toward selective commercial adoption across telecommunications, microwave photonics, lidar, sensing, and emerging quantum transduction applications. The market expanded materially through the early 2020s, with a compound annual growth trajectory that we model at 7.5% across the forecast horizon. PW Consulting’s base-year alignment to 2025 and our 2026–2032 forecast show continuing growth pressure driven by broader system‑level needs for compact true‑time delay, reduced latency, and improved integration density.
Integrated Optical Delay Line Market
For context, the market’s maturation is evident in its revenue progression from the early 2020s into 2025 and the subsequent forecast to 2032. This steady growth underpins strategic choices in R&D allocation, capacity planning, and M&A timing: it is large enough to attract multi‑disciplinary entrants, yet not so commoditized as to eliminate premium pockets for differentiated material platforms, packaging approaches, and integrated module offerings.
Integrated Optical Delay Line Market
Why this matters for 2026 strategy
- Timing of commercialization vs. scale: 2026 is the inflection year where early technical demonstrations and pilot deployments meet the pragmatic demands of system integrators. Organizations must decide whether to move from prototyping partnerships into captive capability or to secure long‑lead supply agreements with specialist foundries and module suppliers.
- Capital allocation tradeoffs: With a mid‑single‑digit CAGR and clear pockets of high‑value applications (e.g., defense, high‑end telecom, and quantum transduction), companies must prioritize between targeted vertical plays and broader horizontal product lines. PW Consulting’s scenario models help quantify payback horizons under different go‑to‑market paths.
- Platform bets matter: Material-platform choices and foundry partner selection determine future feature sets (loss, thermal stability, footprint) and cost curves. Our analysis shows that low‑loss waveguide platforms and multimode silicon photonic approaches are unlocking new delay densities; however, packaging and thermo‑mechanical stability remain decisive for field reliability.
Technology and supply‑chain dynamics to watch
Technical advances and foundry availability are key constraints and enablers in 2026. Recent work on multimode silicon photonics demonstrates a pathway to break traditional delay‑density limits, while electro‑optic transducer innovations broaden the addressable application set into quantum and microwave‑to‑optical domains.
- Foundry & process readiness: Multi‑project wafer (MPW) services and 220‑nm SOI process nodes are enabling compact, mm²‑scale delay implementations suitable for system integration. Decision‑makers should assess foundry roadmaps and MPW cadence as part of any near‑term ramp plan.
- Material choices: Silicon‑on‑insulator, silicon nitride, and lithium niobate each offer distinct tradeoffs across loss, bandwidth, and integration complexity. Low‑loss waveguides (<0.1 dB/m) are becoming table stakes for ns‑scale delays in many use cases.
- Packaging & integration: The gulf between chip demonstration and productized module is dominated by packaging, connectorization, and thermal control. Suppliers that combine optical design with robust mechanical and electrical integration will command premium positioning.
- Standards & controls: Industry standards advocating low‑loss and thermal stability are raising the bar for fielded products. Concurrently, export controls on precision photonic components for dual‑use radar and quantum systems will shape market access strategies and supplier geographies.
Competitive landscape — focused, but with white space
The IODL market exhibits moderate concentration: the top three suppliers account for a meaningful portion of current revenues, and the top five increase that share further. This concentration underscores the presence of established technology providers while leaving room for specialized entrants and regional players to capture niche value.
Key industry participants highlighted in our research illustrate distinct go‑to‑market models and technical emphases:
- Enablence Technologies (Ottawa): Specializes in planar lightwave circuit (PLC) implementations enabling ultra‑long delay lines in compact footprints. Their recent partnership to supply PLC chips for FMCW LiDAR sensor makers signals a clear commercialization vector into automotive and robotics sensing stacks.
- IBM (Armonk): Approaches IODLs from a research and systems perspective, focusing on electro‑optic transducers and integration pathways for quantum transduction and microwave‑to‑optical conversions. Their patent activity reflects strategic intent to lower decoherence and insertion loss in high‑precision applications.
- Microwave Photonic Systems (MPS) (West Chester): Targets RF and radar systems with packaged photonic delay solutions optimized for wide bandwidths and fieldable integration — a useful model for defense and communications primes.
- Agiltron (Woburn): Provides modular delay products with user interfaces and high‑resolution switching, offering system integrators a lower‑risk path to prototype and pilot deployments.
- G&H (Gooch & Housego) (Ilminster): Focuses on custom fiber optic assemblies and small‑form‑factor variable optical delay lines, representing the bridge between fiber‑based incumbents and emerging on‑chip approaches.
Recent developments reinforce the pattern: partnerships aligning component specialists with system integrators, patent grants signaling strategic IP plays in quantum and transduction, and university demonstrations pushing technical boundaries. Taken together, these moves indicate an ecosystem evolving from academic demonstrations to commercially structured value chains.
Risk vectors and regulatory considerations
Strategic plans in 2026 must factor in several non‑market risks that materially affect timing and market access:
- Export controls and dual‑use scrutiny: High‑precision delay solutions used in radar and quantum systems are increasingly scrutinized under export control frameworks. Early engagement with compliance and licensing teams is mandatory for companies targeting cross‑border sales.
- Standards compliance: IEEE and related photonics standards are converging on low‑loss and thermal stability benchmarks. Products that do not meet emerging normative requirements will face adoption resistance in conservative telecom and defense procurement cycles.
- Supply chain concentration: Dependence on a narrow set of foundries or specialty material suppliers exposes programs to capacity constraints and lead‑time volatility. Diversified multi‑foundry strategies and qualification roadmaps are prudent hedges.
What the PW Consulting report contains — practical, decision‑grade deliverables
To preserve the signal in this preview while guiding actionable next steps, the full Integrated Optical Delay Line Market report provides the following practitioner‑oriented modules:
- Detailed market model (historic 2020–2025; forecast 2026–2032) with scenario toggles for adoption curves, price erosion, and application mix. (High‑level figures are summarized in this briefing; subscriber access unlocks the interactive model.)
- Competitive benchmarking with vendor diagnostic matrices across technology platform, packaging maturity, IP posture, and commercial readiness.
- Go‑to‑market playbooks tailored to three archetypes: system integrator, component foundry, and diversified OEM — including channel strategies, sample‑to‑production timelines, and recommended partner archetypes.
- Supplier selection framework and RFQ checklist for qualifying foundries, material vendors, and assembly partners — designed to shorten qualification cycles and reduce time‑to‑field risk.
- Regulatory & risk assessment with mitigation pathways for export control, standards compliance, and dual‑use governance.
- Investment and M&A due diligence template, including prioritized diligence questions for IP, tech transfer readiness, and integration costs.
Note: consistent with the preview principle, we intentionally omit the detailed region, application and type‑level revenue breakdowns from this summary. The full report includes those subsegment tables, growth shares, and sensitivity testing that underpin the strategic recommendations above.
Actionable recommendations for 2026
- Map capability to application economics: Prioritize platform investments that align with near‑term, high‑margin applications (defense, specialized telecom cores, and quantum systems). Use pilot partnerships to de‑risk packaging and thermal control before committing to full volume ramps.
- Secure foundry and packaging options early: Negotiate capacity reservations or preferred MPW slots with foundries that support your chosen substrate and process. Concurrently, qualify at least two packaging partners to de‑risk single‑vendor exposure.
- Protect and scout IP thoughtfully: Combine defensive patenting where necessary (e.g., transduction or integration methods) with active scouting of university consortia for emerging multimode and low‑loss techniques.
- Integrate compliance into commercial planning: Build export control and standards compliance into product roadmaps and tender responses to avoid late‑stage market exclusions.
- Use modular commercialization: Where feasible, offer modularized delay units or turnkey modules to accelerate adoption by system integrators while preserving optionality for future integration into custom SoCs.
Next steps — how PW Consulting can help
For leadership teams preparing 2026 investment rounds, product roadmaps, or M&A diligence, PW Consulting offers tailored engagements ranging from rapid market validation sprints to full commercial readiness programs, including access to the interactive market model, vendor scorecards, and our scenario analyses. The full report contains the subsegment revenue tables, competitive shares, and downloadable financial models necessary for board and investor presentations.
To obtain the comprehensive Integrated Optical Delay Line Market report and unlock the granular segmentation, sensitivity analyses, and supplier scorecards referenced in this preview, please visit the PW Consulting reports portal or contact our industry team for a briefing tailored to your strategic context.
Closing observation
Integrated optical delay lines are moving from a technical novelty toward selective commercial utility. The market’s steady mid‑single‑digit CAGR reflects this balance: meaningful growth and opportunity, but with decisive differentiation driven by platform choice, packaging excellence, and compliance-aware commercialization. Organizations that align product strategy, foundry partnerships, and regulatory planning in 2026 will capture preferential positions as the market expands through the early 2030s.
For detailed analysis of this topic, please visit the official page: Integrated Optical Delay Line Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Autostereoscopic Displays Market to Grow at 17.88% CAGR, Surpassing USD 5.76 Billion by 2032
By pmarketresearch, 2026-07-13
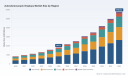
Autostereoscopic Displays Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
As enterprises prepare capital allocation and product roadmaps for 2026, autostereoscopic (glasses-free 3D) displays are moving from niche showcase technology toward repeatable commercial deployments across digital signage, medical visualization, automotive cabins and premium consumer devices. PW Consulting’s forthcoming market study — anchored on a 2025 base year and projecting through 2032 — quantifies this shift and translates it into operational guidance. Our topline forecast shows the market expanding from a 2025 base into a multi‑billion dollar opportunity by 2032, driven by a compound annual growth rate of 17.88% across the 2026–2032 forecast horizon. This preview outlines the strategic value the full report delivers to boards, product chiefs, procurement teams and private investors, while intentionally holding back granular segment tables to preserve the exclusive value of the full dataset.
Autostereoscopic Displays Market
Why 2026 Is a Strategic Inflection Point
-
From a demand perspective, maturity in display optics, head- and eye-tracking, and system-on-chip integration is lowering the cost and complexity thresholds for large-format signboards, medical monitors and in-vehicle displays. Commercial pilots are moving into scaled rollouts.
Autostereoscopic Displays Market -
From a supply-side perspective, 2025–2026 is marked by policy and input-cost shocks that materially affect sourcing and margin dynamics. Recent trade and tariff actions targeting electronic components, together with concentrated production of optical films and AMOLED materials in Asia, create acute procurement risk — and procurement teams must act now to secure continuity and pricing leverage.
Autostereoscopic Displays Market -
From a competitive perspective, incumbent display OEMs and a growing set of specialist innovators are deploying differentiated technologies — lenticular optics, parallax barriers, directional backlighting, light-field systems and switchable solutions — producing a bifurcated landscape where system-level integration and application-specific validation determine winners.
What the Full Report Provides — Practical, Decision‑Ready Tools
The full PW Consulting report is built for immediate operational use by commercial leaders and investors. Key deliverables include:
-
Robust market sizing and scenario forecasts (base year 2025; forecast period 2026–2032) with demand drivers mapped to application and technology adoption curves, enabling three-tier scenario planning (conservative, base, accelerated).
-
Technology roadmaps and architecture trade-off models that compare optical approaches (lenticular, parallax, directional backlight) against light-field and switchable displays, with actionable criteria for cost, image fidelity, viewing angle, power consumption and integration complexity.
-
Procurement playbooks: supplier scorecards, total cost of ownership (TCO) calculators, contract clauses addressing tariff and IP risk, and near-term sourcing decision trees tailored to 2026 budget cycles.
-
Go-to-market playbooks for vendors and systems integrators including product positioning by application (advertising & signage, healthcare visualization, in-vehicle UX), pilot-to-scale roadmaps, pricing frameworks and channel strategies.
-
Risk matrices that translate macro-policy shocks and raw material volatility into financial sensitivities, plus mitigation templates for multi-sourcing, buffer inventory and hedging of critical optics components.
-
Investment and M&A scorecards that map IP, manufacturing capacity, customer concentration and margin profiles to acquisition valuation bands and integration risk tiers.
-
Vendor profiles and comparative capability matrices (executive summaries of market players, product strengths, distribution footprints, and go-to-market vectors) to accelerate supplier selection and partnership diligence.
Competitive Landscape — Who Matters, and How
The market structure as of 2025–2026 shows moderate concentration: the top three players account for a meaningful share of revenue, while the top five consolidate a majority position. This concentration dynamic creates both strategic advantages for incumbents and windows of opportunity for fast‑moving specialists.
-
Magnetic 3D (New York) continues to be a visible commercial force in large-format digital signage and enterprise displays. With recent product expansions into all-in-one multiview displays, the firm is prioritizing turnkey solutions for retail and experiential signage where ease-of-deployment matters most.
-
Alioscopy (Paris) remains positioned on the high end of precision lenticular optics, serving professional visualization and specialty display needs where resolution and color fidelity are non-negotiable. Its engineering-led approach and high-resolution offerings match use cases in professional design and industrial visualization.
-
Leia Inc. (USA) pushes the consumer-device angle with switchable light-field stacks and spatial AI tooling. Their platform approach — marrying hardware with spatial content tooling — is a template for consumer OEM partnerships and licensing models.
-
Dimenco (Netherlands), Barco (Belgium) and specialist groups such as 3D Global Solutions and MOPIC are leaning into vertical applications: medical visualization, endoscopic systems and secure professional displays where certified performance and domain-specific features (eye-tracking, low-latency rendering) command premium pricing.
-
Major OEMs (Samsung, LG, Philips) are experimenting with both research-grade autostereoscopic prototypes and commercial signage offerings. Their reach and channel muscle can rapidly scale proven module technology but will require product differentiation to justify above-commodity pricing.
-
New entrants and scale-ups (e.g., Zondision) are notable for integrating eye-tracking with custom ASICs — an indicator that vertical integration at the silicon level is a competitive lever for cost and performance.
Recent industry activity reinforces the above dynamics. Through late 2025 and into mid-2026 we observed multiple product introductions focused on interactive, eye-tracked autostereoscopic monitors and large-format signage demonstrations at major trade events. These launches indicate a move from technical proof-of-concept to customer-validated solutions in specific verticals.
Regulatory, Supply‑Chain and Cost Considerations Shaping Near‑Term Strategy
-
Trade policy risk is no longer hypothetical. In 2025 and early 2026, reciprocal tariffs and targeted duties on Chinese-origin electronics created immediate sourcing pressure for modules and optical films. Some exemptions exist but are temporary and subject to review — creating an imperative to stress-test supplier contracts and design dual-sourcing strategies.
-
Optical films, parallax barriers and AMOLED supply chains remain geographically concentrated. Tariff uncertainty and logistics disruptions can cascade into price increases for module BOMs; procurement teams should model 10–25% input-cost shocks in downside scenarios and prioritize inventory, multi-sourcing and design flexibility.
-
Labor and proximity advantages in Asian production continue to provide measurable cost levers. Our analysis shows that manufacturing bases in Asia often yield lower direct production cost versus Western alternatives — a material factor when evaluating whether to localize production or accept longer supply chains for high‑value systems.
Actionable 90‑Day Roadmap for Executive Teams
To translate insight into action for 2026, PW Consulting recommends this prioritized checklist for commercial and procurement leaders:
-
Complete an exposure audit: quantify component-level sourcing concentration, tariff exposure and single-supplier risks for critical optical components.
-
Initiate high-priority pilots in one vertical where your organization can capture premium pricing (e.g., healthcare visualization or premium signage); structure pilots with milestone-based purchase commitments to derisk scale-up.
-
Deploy TCO and sensitivity modeling from the report to evaluate make-vs-buy decisions, factoring in potential tariff regimes and freight constraints.
-
Open parallel supplier engagement streams: one near-term partner with established capacity and one strategic partner focused on differentiation (optics, ASICs, spatial software).
-
Lock in IP and integration terms early when engaging with module suppliers; define clear acceptance tests for viewing-angle, latency and calibration to avoid costly integration rework.
-
For investors and acquirers: use the report’s M&A scorecards to flag targets with defensible IP, validated customer pilots and scalable manufacturing roadmaps.
Why PW Consulting’s Report Is a 2026 Operational Essential
Our study blends market economics, technology assessment and procurement-grade tools into a single deliverable calibrated to the 2026 decision calendar. The forecast is granular enough to model program economics into multi-year CAPEX cycles yet delivered with templates and playbooks that enable immediate action. While this preview highlights strategic takeaways, the full report contains the detailed, machine-readable datasets, segmentation tables, vendor financials and scenario models that procurement, product and corporate development teams will require to execute confidently in 2026.
PW Consulting intentionally withholds the full segmentation matrices and certain granular split figures in this public summary to preserve the actionable value of the primary dataset. Those locked elements include itemized regional and application-level revenue splits and per-technology SKU economics — the exact inputs that underwrite procurement decisions and investment valuations.
Next Steps
For executive teams preparing budgets, product roadmaps or M&A pipelines for 2026, securing the full PW Consulting Autostereoscopic Displays Market report will provide the data and templates needed to move from strategy to procurement and commercialization. The report’s combination of validated market forecasts (2026–2032), competitive diagnostics, supplier scorecards, regulatory sensitivity analyses and operational playbooks is tailored for rapid adoption.
To access the full dataset and decision tools referenced in this preview, please visit the PW Consulting report page or contact our strategy desk for an executive briefing. The 2026 window for decisive supplier engagement, pilot conversion and portfolio positioning is narrow — market leaders will pair informed scenario planning with near-term operational moves to capture the outsized returns that a 17.88% CAGR market trajectory makes possible.
For detailed analysis of this topic, please visit the official page: Autostereoscopic Displays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Desktop Virtualization Software Market to Surge from USD 19,450.6 Million in 2025 to USD 44,029.5 Million by 2032 at a 12.38% CAGR
By pmarketresearch, 2026-07-13
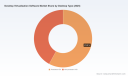
Desktop Virtualization Software Market 2026: Strategic Imperatives for Enterprise Decision‑Makers
Executive summary
The desktop virtualization software market is entering a decisive phase where technology maturation, regulatory pressure, and changing consumption models converge to reshape enterprise IT strategy. Our latest PW Consulting market study — anchored on a 2025 base year and projecting through 2032 — shows the market roughly doubling in size over the last five years and continuing strong, with a compounded annual growth rate of 12.38% across the forecast horizon. By 2025 the market had reached just under USD 19.5 billion (revenue basis, millions USD unit), and our scenario analysis points to an exit market of approximately USD 44.0 billion by 2032 under the base forecast. At the same time, concentration metrics indicate the top vendors control a substantial majority of revenue, underscoring a competitive environment that combines dominant cloud platforms with specialized niche providers.
Desktop Virtualization Software Market
Why this report matters for 2026 decision cycles
For CIOs, CTOs, and procurement leaders finalizing budgets and strategic roadmaps in 2026, the decision to refresh desktop virtualization strategies is no longer tactical — it’s transformational. This report translates macro momentum into actionable intelligence: when to accelerate cloud-first migrations, how to structure hybrid operating models, what cost levers to expect from security and compliance, and how vendor licensing shifts can alter multi‑year TCO. We deliberately present deep, practitioner‑oriented guidance while reserving the full granular segment dataset for subscribers — a design choice that balances public strategic signaling with the confidentiality enterprise buyers require.
Desktop Virtualization Software Market
What’s in the report (practical, operational content)
- Market sizing and forecast methodology, including scenario and sensitivity analyses covering 2026–2032.
- Demand-side drivers and buyer personas mapped to real procurement cycles, with workload classification templates to prioritize migration candidates.
- Deployment decision framework (cloud vs. on‑premises vs. hybrid) with a step‑by‑step playbook for pilots and scale‑up phases.
- Full vendor scorecards and comparative capability matrices covering product architecture, management tooling, security controls, and channel models.
- TCO and ROI models with editable inputs for hardware, licensing, workforce, and operational security add‑ons; a practitioner’s guide to capture hidden costs.
- Compliance and data‑sovereignty checklists aligned to major regimes (GDPR, HIPAA, PCI‑DSS) and guidance on mitigating legal exposure linked to extraterritorial laws.
- Procurement negotiation templates and SLA clauses tuned for cloud desktop engagements and managed service contracts.
- Case studies and migration templates from multi‑industry implementations, plus a risk register for common failure modes.
Note: To preserve the value of the research as a decision‑ready asset, public summaries omit the full segmentation tables. The report contains comprehensive breakouts by region, deployment mode, and desktop type — available through the report portal.
Desktop Virtualization Software Market
Key market dynamics shaping vendor and buyer behavior
- Cloud acceleration vs. hybrid realism: Enterprises are accelerating cloud desktop adoption for scale and management simplicity, yet hybrid deployments remain the pragmatic choice for regulated workloads and latency‑sensitive use cases. Our forecasting reflects persistent demand for both approaches.
- Licensing and activation risk: Vendor moves to cloud‑centric licensing models and mandatory activation services create migration windows that require active vendor engagement and careful cutover planning to avoid service disruption.
- Security and operational cost trade‑offs: Zero Trust enforcement, device compliance checks, and advanced monitoring materially increase operational spend. These are often licensed or delivered as premium modules and must be included in three‑ to five‑year TCO scenarios.
- Regulatory and sovereignty pressures: Data residency concerns and extraterritorial legislation are reshaping provider selection, pushing some buyers toward localized deployments or regionally certified partners.
Competitive landscape — who matters and what to watch
The vendor landscape is a hybrid of hyperscaler cloud platforms, legacy virtualization specialists, and agile niche players. The market’s structure favors integrated cloud ecosystems while leaving room for differentiation around management simplicity, application performance, and enterprise security posture. Key players profiled in the report include:
- Microsoft Corporation — Strong momentum around Azure Virtual Desktop and Windows 365, with deep integration into Microsoft 365 and hybrid options that appeal to organizations standardizing on Microsoft stacks. Recent platform updates have extended application‑attach and session host support, underscoring continued investment in scale and manageability.
- Amazon Web Services (AWS) — Amazon WorkSpaces continues to broaden regional availability and platform capabilities, including recent support for next‑generation Windows server releases and TPM‑enhanced security bundles. AWS’s flexible pricing and global footprint make it a credible choice for cross‑region enterprises.
- Citrix Systems, Inc. — Citrix remains a go‑to for high‑performance remote access and secure application delivery, but recent mandates around cloud‑based licensing activation require customers to plan migrations carefully to maintain continuity.
- Omnissa (formerly VMware) — Enterprise VDI solutions with strong hybrid/on‑prem integration appeal to organizations prioritizing in‑house control and advanced virtual desktop management.
- Nutanix, Parallels, Inuvika, and Oracle — These vendors provide differentiated choices: Nutanix with hybrid integration plays, Parallels for SMB simplicity, Inuvika as a cost‑effective open alternative for Linux workloads, and Oracle for customers seeking tight coupling with enterprise database and cloud services.
Our market concentration analysis shows the largest vendors account for a dominant share of market revenue, creating both strategic dependencies and competitive opportunities for specialized providers. For buyers, this means negotiating power exists but requires a disciplined approach to vendor comparison beyond sticker pricing.
Recent vendor developments to monitor
- AWS expanded WorkSpaces regional availability and enhanced platform support for recent Windows Server releases (notable updates in Q1–Q2 2026).
- Microsoft enhanced application‑attach capabilities to support newer session host versions, improving lifecycle flexibility for application management.
- Nutanix announced public‑preview integrations for hybrid Azure Virtual Desktop scenarios on its AHV hypervisor — a notable signal of increased interoperability between hyperconverged infrastructure vendors and hyperscalers.
- Citrix’s migration to a cloud License Activation Service introduced a hard timeline that has implications for licensing continuity and migration project sequencing.
Risks and compliance considerations
Implementations face a confluence of legal, operational, and technical risks. From a compliance perspective, VDI deployments used in regulated industries must demonstrate workload isolation, encryption, and auditability consistent with HIPAA, PCI‑DSS, and GDPR obligations. Data sovereignty and the potential applicability of extraterritorial laws (for example, the US CLOUD Act) can constrain public cloud choices and necessitate hybrid or localized architectures. Operationally, the incremental workforce and tooling needed to enforce Zero Trust and continuous monitoring are frequently underestimated; our field work shows these items are common drivers of unexpected cost overruns.
Practical next steps for 2026 buyers
- Initiate an application workload mapping exercise this quarter to classify candidates for persistent vs. non‑persistent delivery and to prioritize migration batches.
- Run vendor‑neutral TCO scenarios that include security add‑ons, licensing activation conditions, and regional compliance costs over a five‑year horizon.
- Engage early with incumbent vendors where mandatory license activation or migration windows exist to avoid service interruptions and secure transition discounts.
- Pilot hybrid reference architectures for regulated workloads, validating latency, user experience, and data residency controls before wide rollout.
- Update procurement templates to include SLA points for license portability, data residency guarantees, and clear exit provisions.
How PW Consulting can help
PW Consulting’s Desktop Virtualization Software Market Report is designed to be a working resource for practitioners: not a passive briefing, but a playbook. Subscribers receive the full dataset (detailed segmentation breakouts, vendor scorecards, and editable financial models) alongside advisory hours for customized scenario modeling and implementation planning. For teams gearing up for procurement cycles and board‑level approvals in 2026, our analysts can accelerate vendor evaluations, quantify migration costs, and build defensible roadmaps aligned to your risk tolerance and regulatory footprint.
To access the full intelligence — including the complete regional, deployment‑mode, and desktop‑type breakouts that inform the TCO and segment forecasts — please visit the PW Consulting report landing page for purchase and subscription options. The public summary above highlights the strategic contours; the full report equips your team to make the specific, defensible decisions required this year.
For detailed analysis of this topic, please visit the official page: Desktop Virtualization Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com