

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Managed Security Services Market to More Than Double to USD86.78 Billion by 2032, Driven by 11.5% CAGR

Managed Security Services System Market 2026: Strategic Imperatives from PW Consulting
PW Consulting today publishes an executive-level briefing drawn from our forthcoming Managed Security Services System Market research report (base year 2025, historical window 2020–2025, forecast 2026–2032). This briefing is designed to surface the strategic conclusions that will matter to CISOs, procurement leaders, and technology investors as they set priorities and budgets for 2026. It intentionally highlights the decision-grade insights and practical frameworks contained in the full report while preserving granular segmentation and vendor scorecard data to encourage direct access to the complete study.
Managed Security Services System Market
Why this report matters for 2026 decisions
-
Rapid, sustained market growth creates both opportunity and vendor risk. Our market model tracks a compound annual growth rate of 11.5% across the 2026–2032 forecast window, reflecting accelerating demand for outsourced detection, response, and managed resilience across cloud, edge, and hybrid estates. The total market has more than doubled since 2020 and is on a clear upward trajectory into the early 2030s.
Managed Security Services System Market -
Energy, regulation, and supply-side constraints are now first-order strategic variables. New regional bills, national pledges on ratepayer protections, and data‑handling rules are reshaping cost profiles for providers—and therefore contractual risks for buyers.
Managed Security Services System Market -
Service design is evolving from commodity monitoring to outcome contracts that combine MDR, orchestration (SOAR), XDR-enablement, and advisory vCISO capabilities. Buyers who demand outcome-based metrics and integrated resilience clauses will extract better economic and security outcomes.
What the full report delivers (practical, operational outputs)
PW Consulting structured this market study for active practitioners. The deliverables embedded in the full report are geared to convert insight into procurement and operational action:
-
Decision frameworks for build vs. buy vs. co-managed architectures—complete with a vendor-agnostic capability map and maturity-level gating criteria.
-
Vendor evaluation templates and RFP/RFI language calibrated to modern outcomes (MTTD/MTTR SLAs, false-positive economics, playbook coverage, and escalation-to-vCISO paths).
-
Service design blueprints for integrating MDR, SASE, managed firewall, threat intel, and vulnerability management into a single operational picture.
-
TCO and ROI models that account for energy and infrastructure pass-through risks, regulatory compliance costs, and transition expenses for cloud/hybrid migrations.
-
Tabletop exercise scenarios, incident response runbooks, and vCISO engagement templates for board-level reporting and continuous improvement cycles.
-
Negotiation playbooks and contract templates that capture indemnity placement, audit rights, data locality controls, and performance credits linked to containment outcomes.
Market dynamics shaping 2026
-
From fragmentation to selective consolidation: concentration metrics in our study show the market remains relatively fragmented compared with traditional telecom or cloud markets, with a small but growing set of established global providers and a diverse mid‑tier ecosystem driving innovation. This structure creates options for buyers: global scale or specialized regional/mid‑market expertise—each with different risk and price trade-offs.
-
Regulatory and infrastructure shocks are redefining commercial models. A wave of data center legislation and national-level energy pledges is already affecting provider cost bases and may lead to regionalized pricing, territorial deployment strategies, and new SLAs tied to energy resilience.
-
Product and platform differentiation is increasingly achieved via automation, AI-enabled detection orchestration, and certificate/lifecycle automation that reduce operational friction and containment time.
-
Service packaging is moving away from monolithic bundles to modular, outcome-oriented offers that allow buyers to scale detection, threat intel, and incident response independently.
Competitive landscape: strategic positions to watch
The managed security space in 2026 is defined by a mix of global systems integrators, network incumbents, pure‑play MSSPs, and specialist MDR firms. The full report includes vendor scorecards and comparative matrices; below is a high‑level strategic read on leading players and the capabilities buyers should evaluate.
-
IBM Security — Deep hybrid-cloud systems integration and a broad 24/7 managed services footprint. IBM plays to enterprise accounts that require tight integration across on-prem, private cloud, and public cloud estates. Key buyer consideration: strong orchestration and compliance capabilities but assess agility for small-to-mid-market pilots.
-
Verizon — Leverages global network infrastructure and carrier-grade DDoS/SASE capabilities. Best suited to organizations that prioritize integrated network security and operator-scale incident response. Key buyer consideration: network-coupled resilience vs. independence of cloud-native detection stacks.
-
LevelBlue — A pure-play MSSP with roots in established provider offerings; increasingly recognized in analyst research. Attractive for buyers seeking focused MDR capabilities and flexible deployment models (including FedRAMP-authorized services). Key buyer consideration: evaluate platform interoperability and threat intel sharing constructs.
-
Tata Communications — Emphasizes global reach and network-integrated monitoring. Strong for multinational customers with complex international estates that need unified operations and regional compliance workflows.
-
Secureworks — Built around the Taegis XDR platform; emphasizes analytics-driven detection and response. Best for enterprises aiming for advanced telemetry and threat hunting at scale.
-
Arctic Wolf — Marketed around a “Concierge Security” approach pairing human analysts with SOC technology. Effective for organizations seeking managed detection with strong customer engagement models and outcome SLAs.
-
eSentire — Expert‑led MDR with a focus on 24/7 operations and threat containment. Consider for workloads requiring proactive hunting and specialized incident playbooks.
Recent provider activity in early 2026 underscores how quickly capability stacks are evolving. Examples include an AI-enabled managed security operations suite launched by a major supplier, recognition of specialized SOC capabilities tied to major cloud platforms, and platform launches that automate previously manual certificate and trust processes. These moves accelerate time-to-detection improvements and push buyers to re-assess incumbent contracts.
Regulatory tailwinds and operational risk
-
New state and national energy and data center regulations are material to procurement. Buyers should quantify exposure to energy pass-throughs, geographic data residency requirements, and potential limitations on cross-border incident handling.
-
Legislation that targets bulk data transactions and enhanced controls for foreign-party access imposes new technical and contractual obligations on MSSPs and their customers—particularly for multi-jurisdictional operations.
-
Procurement teams must now demand stronger evidence of regulatory posture from providers—technical attestations, third‑party audits, and contractual remedies tied to noncompliance.
Actionable recommendations for 2026
-
Adopt an outcomes-first procurement approach. Define detection and containment outcomes (MTTD/MTTR/containment rate) and build payment/success milestones around them instead of pure headcount or device counts.
-
Include energy and infrastructure clauses in contracts. Require transparency on provider energy exposure and contingency plans for grid disruptions or tariff shifts.
-
Run modular pilots that validate AI-assisted detection and certificate automation before full-scale migration. Use those pilots to stress-test incident escalation pathways and vendor-integrated SOAR playbooks.
-
Mandate cross-border handling and data residency controls that align with your regulatory footprint and the evolving Bulk Data Rule-like regimes.
-
Require vendor openness on telemetry and integration: insist on standard APIs, event normalization, and data export rights to avoid lock-in.
-
Create a two‑track sourcing strategy: secure global coverage for core resilience while commissioning boutique specialists for threat hunting, offensive security, and industry-specific intelligence.
Methodology and signal confidence
PW Consulting’s market sizing and forecasts combine bottom‑up vendor revenue modeling, demand-side surveys, and trend extrapolation from 2020–2025. The 2026–2032 forecasts are stress‑tested with scenario analyses—including energy shock, rapid regulation, and accelerated cloud adoption—to produce a central case with a measured confidence interval. Our competitive analysis integrates public filings, direct vendor interviews, and third-party validation to reflect both capability and market access.
Next steps: where to get the complete intelligence
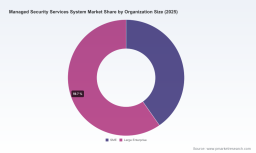
This briefing synthesizes the strategic imperatives from PW Consulting’s Managed Security Services System Market research. The full report contains granular segmentation by geography, service type, organization size, detailed vendor scorecards, country‑level regulatory matrices, downloadable RFP templates, TCO spreadsheets, and playbooks referenced above. To access the complete analysis and the practical toolset for 2026 procurement and operating-model decisions, please visit our report page or contact a PW Consulting industry analyst.
PW Consulting remains available to run executive workshops, vendor selection programs, and implementation oversight to convert this market intelligence into measurable security and business outcomes.
For detailed analysis of this topic, please visit the official page: Managed Security Services System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com