

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: IT & Electronics
PW Consulting Forecast: GPS & GNSS Receivers in Aviation Market to Grow at a 6.75% CAGR Through 2032
By pmarketresearch, 2026-07-13
GPS and GNSS Receivers in Aviation Market — Strategic Insights for 2026 Decision-Makers
As airspace modernization, geostrategic tensions, and higher integrity requirements reshape airborne navigation, organizations must translate technical trends into actionable strategy. PW Consulting’s latest market study on GPS and GNSS receivers in aviation frames that translation for 2026 decision cycles. The report shows that the global market — having reached approximately USD 1,850 million in the 2025 base year — is on a sustained growth path, with projections reaching roughly USD 2,923 million by 2032 at a compound annual growth rate (CAGR) of 6.75% over the 2026–2032 forecast window. These headline figures understate the structural shifts driving procurement, R&D, and partnership priorities across airlines, OEMs, defense programmes, and avionics suppliers.
Gps And Gnss Receivers In Aviation Market
What this report delivers — practical, decision-ready intelligence
-
A concise executive framework that maps regulatory catalysts, threat vectors (jamming/spoofing), and mission requirements to receiver-class decisions — civilian, business/general aviation retrofit, and military assured PNT.
Gps And Gnss Receivers In Aviation Market -
Vendor benchmarking and capability matrices covering certification status, anti-jam/anti-spoofing effectiveness, multi-frequency support, GNSS+INS integration, and roadmap alignment with NextGen/SESAR programmes.
Gps And Gnss Receivers In Aviation Market -
Procurement playbooks and retrofit / new-build total cost of ownership (TCO) models that operationalize certification timelines, lifecycle support, and avionics integration risk.
-
Scenario-based stress tests quantifying operational exposure to localized interference and global service degradation, with recommended mitigation portfolios (hardware, software, and operational procedures).
-
Commercial opportunities and M&A scouting templates for investors and corporates seeking to position across the value chain — from OEM modules to integrated avionics and cyber-resilient PNT services.
Why 2026 is a pivot point
Several converging drivers make 2026 a decisive planning year. Regulatory programmes (notably NextGen and SESAR) are accelerating adoption of L5 and DFMC-capable receivers to enable performance-based navigation and precision approaches. At the same time, aviation authorities have published updated interference guidance, reflecting a steep increase in jamming and spoofing incidents over recent years. National mandates and regional rules — such as dual-frequency compliance requirements from major airworthiness authorities — are accelerating retrofit demand and shaping OEM specifications.
For operators and systems integrators, this creates a dual challenge: deploy technology that meets emergent safety and navigation performance standards while also hedging against an increasingly contested signal environment. The commercial implication is that buyers are no longer making decisions based purely on position accuracy metrics; resilience, certification velocity, and integration risk dominate procurement criteria.
Technology and capability trends to watch
-
Resilient PNT architectures — Multi-frequency, multi-constellation receivers paired with inertial measurement systems (GNSS+INS) are now baseline design choices for mission-critical platforms. Anti-jam and anti-spoofing countermeasures, both at the RF front-end and in signal-processing algorithms, are becoming de facto requirements for defense and key commercial applications.
-
Certification and retrofit readiness — Suppliers who can demonstrate certified retrofit pathways (EASA/FAA/CAAC compliance) and offer installation-friendly form factors are gaining faster adoption in the business and general aviation segments.
-
Modularization and OEM ecosystems — There is a divergence between vertically integrated avionics suites and modular OEM receiver suppliers. The former target full-system value capture; the latter focus on high-precision modules and software IP that can be embedded across platforms.
-
Software-defined resilience — Firmware-upgradeable anti-jam/anti-spoofing and the ability to ingest alternative PNT sources (e.g., terrestrial ranging, timing over data links) are strategic differentiators that reduce hardware replacement cycles.
Competitive landscape — what the market structure implies
The market exhibits moderate concentration: the top-three vendors control a meaningful portion of market value, and the top-five capture a clear majority share. This structure favors players who combine certification credentials, breadth across civil and military portfolios, and demonstrable operational deployments.
Key incumbent profiles illustrate the strategic segmentation:
-
Garmin (Schaffhausen) — Strength in certified avionics and retrofit solutions for general aviation and business jets; competitive advantage lies in panel-mount and embedded options that meet FAA/EASA standards and fast aftermarket adoption cycles.
-
Honeywell — Broad avionics integration capability with GNSS receivers and inertial systems for commercial and defense platforms. Honeywell’s value is in aircraft-system integration and lifecycle support at fleet scale.
-
Collins Aerospace (RTX) — Supplier of multi-constellation receivers and integrated navigation products for commercial and military applications, with an emphasis on mission systems and upgrade paths for secure navigation services.
-
Thales — Focused on resilient PNT with certified receivers offering LPV/RNP and anti-jam features; recent product launches underline a push into compact, high-assurance solutions for both crewed and unmanned platforms.
-
Trimble and NovAtel — OEM-grade, high-precision positioning specialists that feed aircraft manufacturers and government programmes where centimeter-level accuracy and SBAS integrity are priority criteria.
-
Defense-focused suppliers (Northrop Grumman, L3Harris, BAE Systems) — Emphasize M-code capable receivers, embedded GPS/INS modernizations, and solutions designed for contested electromagnetic environments.
-
Specialist entrants (Septentrio) — Offer advanced multi-frequency modules with strong anti-jam and anti-spoofing claims targeting a niche of high-precision and high-integrity applications.
Recent product and regulatory developments underscore this dynamic. Strategic deliveries of modernized embedded navigation systems and new anti-jam compact receivers have emerged alongside aviation authority guidance that raises operational reporting and mitigation expectations for interference events. For purchasers, this means vendor selection must account for both product capability and the supplier’s ability to meet evolving regulatory evidence requirements.
Operational and commercial implications — recommended actions for 2026 planners
Leaders must treat receiver procurement as a systems decision that spans policy, operations, and engineering. The following priorities distill the most consequential moves:
-
Prioritize resilient PNT in capital plans — Require demonstrable anti-jam/anti-spoofing performance and GNSS+INS integration capability in procurement specifications. Incorporate certification milestones into supplier contract terms.
-
Diversify supplier risk — Balance incumbents with specialist OEMs to avoid single-source exposure, and require modular interfaces to enable later upgrades without full-system replacement.
-
Accelerate retrofit strategies — For mixed fleets, develop prioritized retrofit roadmaps that align with airworthiness mandates and minimize downtime through staged installation plans and common avionics baselines.
-
Embed scenario planning — Quantify operational exposure to localized interference and plan contingency navigation procedures, pilot training updates, and ATC coordination protocols.
-
Invest in software and data — Allocate R&D to firmware upgradability, anomaly detection, and integration of alternative PNT data feeds to extend product life and reduce hardware refresh costs.
-
Evaluate partnership and M&A plays — Identify technology niches (e.g., front-end anti-jam RF, INS sensor fusion, certified retrofit packaging) that are attractive for bolt-on acquisitions or strategic alliances.
Why PW Consulting’s report is a 2026 boardroom tool
This study translates market projections and technical intelligence into executable plans. Beyond headline growth — the projected market expansion from the 2025 base to 2032 at a 6.75% CAGR — the report delivers templates for procurement, a vendor capability scoring system, regulatory compliance matrices, and tailored scenario analyses. These deliverables are built for executives and functional leads who must justify capital allocations, adjust product roadmaps, and defend resilience investments to boards and auditors.
Importantly, PW Consulting’s approach follows the “need-to-act” principle: highlight where decisions materially affect operational continuity and cost, then provide the tactical tools necessary to execute. For firms that must reconcile fleet modernization with constrained budgets and certification timelines, the report frames the trade-offs and prescribes concrete next steps.
Next steps — how to use the intelligence
-
For procurement teams: use the vendor scorecards and TCO models to short-list suppliers and negotiate milestone-based contracts that link payment to certification and field-proven performance.
-
For product and engineering: adopt the technology roadmap and integration checklists to prioritize firmware modularity and sensor fusion investments that extend platform life.
-
For risk and operations leadership: operationalize the scenario stress-tests to update emergency procedures, ATC coordination, and crew training materials.
-
For investors and corporate strategists: interrogate the market consolidation metrics and M&A templates to identify value-creation targets across OEM modules, avionics integration, and PNT services.
PW Consulting’s full report contains the granular segmentation, regional and application-level forecasts, and detailed vendor market shares that many teams will need to finalize procurement and investment decisions. These datasets and the full suite of practical tools are available in the report’s comprehensive deliverables; PW Consulting can also provide tailored workshops to map the findings to a client’s specific fleet and programme constraints.
For organizations preparing budgets, specification documents, or M&A theses in 2026, this report converts macro momentum into pragmatic action: the growth runway is clear, but the winners will be those who couple technology selection with regulatory foresight and operational resilience.
For detailed analysis of this topic, please visit the official page: Gps And Gnss Receivers In Aviation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Paid Micro Short Drama Market Reaches USD 1,250 Million in 2025, Poised to Grow at a 22.45% CAGR Through 2032
By pmarketresearch, 2026-07-13
Paid Micro Short Drama Production Market: Strategic Outlook for 2026 — PW Consulting Insights
PW Consulting’s new Paid Micro Short Drama Production Market report (base year 2025; forecast period 2026–2032) arrives at a turning point for content strategy and production economics. Our analysis quantifies a market that expanded rapidly through 2020–2025 and is projected to grow at a robust compound annual growth rate (CAGR) of 22.45% across the 2026–2032 forecast window. From an industry value measured in the low hundreds of millions in 2020, the ecosystem exceeded one billion USD by 2025 and is forecast to reach multiple billions by the early 2030s. For decision-makers planning 2026 budgets and strategic initiatives, this trajectory reframes every investment question — from greenlighting slates to selecting production partners and monetization stacks.
Paid Micro Short Drama Production Market
Why this report matters for 2026 decisions
-
Timing: The market has reached commercial scale. Where previously micro-short drama was experimental or promotional, 2025 marked the inflection where dedicated paid channels, vertical-first formats, and coin/subscription mechanisms became repeatable revenue engines. 2026 is the first full planning year where firms can confidently allocate meaningful content CAPEX and expect market-level returns.
Paid Micro Short Drama Production Market -
Cost transformation: Production economics are compressing rapidly due to two forces — compact live-action shoots optimized for vertical formats, and the emergence of AI-native or AI-assisted production workflows. Our report distills how those forces change cost-per-minute and per-episode economics, and what that means for margin-sensitive business models.
Paid Micro Short Drama Production Market -
Structural concentration and competition: The market is not winner-take-all. Top players collectively account for a meaningful but not overwhelming share of revenues, creating opportunity for well-capitalized entrants, regional champions, and specialized studios. We quantify concentration metrics and analyze why differentiated IP and distribution partnerships matter more than scale alone.
Key strategic themes executives must confront in 2026
-
Monetization architecture: Paid micro short dramas are monetized through hybrid mechanisms — microtransactions, time-gated subscriptions, and sponsorship integrations. The right combination depends on audience cohort, content genre, and distribution channel economics. Our report provides frameworks to map unit economics to pricing strategies and lifetime-value (LTV) expectations for core customer segments.
-
Production playbooks and total-cost modelling: Production budgets for professional vertical series vary by ambition, but the sector now supports models from lean rapid-shoot titles to premium “S-class” serialized IP. AI-assisted pipelines can reduce certain production costs dramatically; our modelling shows the trade-offs in quality, speed-to-market, and rights ownership that determine where to deploy AI versus traditional crews.
-
Distribution and partnership engineering: Distribution is multi-architectural — from dedicated short-drama apps and social ecosystems to select OTT partnerships and telco bundles. The most successful strategies in 2025–2026 combine platform placement with direct-to-consumer monetization and strategic regional localizers. We map the commercial levers needed to optimize revenue share, promotional support, and discovery economics.
-
IP strategy and localization: Original IP, licensed adaptations, and brand-sponsored custom content each carry different margin profiles and scalability characteristics. Executives must decide whether to build repeatable original franchises, purchase and localize foreign IP, or monetize through bespoke brand storytelling. Our report offers decision matrices for IP investment versus licensing, including valuation heuristics for short-form serialized formats.
-
Regulatory and labor risk management: Regulatory frameworks and guild agreements have adapted to new formats. Authorities in key markets are introducing transparency and labeling rules for AI-generated content, while major talent guilds have established contracts tailored to microdrama budgets. These developments change cost lines and compliance obligations; our compliance checklist and negotiation playbooks prepare legal and production teams for 2026 realities.
What’s inside the report — practical deliverables
-
Executive dashboards and scenario models: Interactive revenue and cost scenarios across multiple monetization mixes, with stress-testing for acquisition costs and retention decay assumptions.
-
Production cost benchmark toolkit: Line-item templates for vertical microdrama shoots, AI-assisted workflows, and hybrid production; break-even and margin levers for different budget bands.
-
Go-to-market playbooks: Channel strategies for apps, social platforms, OTT windows, and telco partnerships; promotional mechanics and subscriber conversion best practices.
-
IP and content strategy frameworks: Decision matrices for original vs. licensed vs. branded formats, with guidance on territorial rights, localization, dubbing/subtitling economics, and franchise development roadmaps.
-
Regulatory and labor compliance modules: Checklists for AI labeling, content review protocols in regulated markets, and contract templates aligned to the microdrama-specific guild agreements.
-
Competitive intelligence and M&A screen: Profiles of leading studios, platform operators, and production hubs; acquisition scoring templates and integration risk assessments.
Competitive landscape — players shaping 2026
The industry now includes platform-focused operators, vertically specialized producers, and emergent AI-native studios. Notable companies captured in our competitive analysis include:
-
Crazy Maple Studio (ReelShort) — A California-based leader with significant backing and a platform-driven model; focuses on vertical episodic content with coin-based unlocks and subscription hybrids tailored for international audiences.
-
Beijing Dianzhong Technology (DramaBox) — A major China-origin platform and producer with demonstrated strength in overseas markets via localized translations, in-app monetization strategies, and distribution synergies with regional partners.
-
Linmon Media — Expanding from established content production into vertical microdrama slates targeting Asian markets; recent slate launches demonstrate how traditional production houses are adapting format and release strategies for short-form serialized IP.
-
AR Asia Productions — A Hong Kong-based studio that leverages platform and telco partnerships for content delivery across multiple Asian territories and genres, experimenting with bundled distribution models.
-
Vigloo (SpoonLabs) — A Seoul headquartered studio at the vanguard of AI-assisted production, releasing fully AI-native titles in compressed timelines to test English-language and global audiences.
-
Holywater (MyDrama/MyMuse) — A European-based outfit producing Hollywood-caliber microdramas with strategic investment ties and a focus on premium vertical storytelling for international paid platforms.
These companies illustrate three sustainable competitive approaches: platform-anchored ecosystems that control discovery and payments; studio-driven IP owners focusing on franchise value and licensing; and technology-first entrants that compress production cycles and cost bases through AI. Our concentration analysis quantifies that the top-three participants capture a material portion of market revenue while the top-five broaden that footprint — a structure that supports both consolidation and continued niche-entry opportunities.
Recent developments shaping the 2026 playbook
-
Slate launches and regional expansion: Established studios are converting proven long-form IP strategies into microdrama slates geared to regional consumption windows and mobile-first viewing patterns.
-
AI-native releases: Fully AI-produced titles are commercially viable experiments that demonstrate dramatically compressed production cycles; such releases are reshaping content timelines and unit economics.
-
Production infrastructure scaling: Government-backed and private AI-assisted production hubs are enabling thousands of micro-production teams to access tooling and standardized pipelines — accelerating output but also increasing supply-side competition.
-
Regulatory and guild alignment: New labeling requirements for AI-generated content and microdrama-specific talent agreements have created operational constraints and protections that buyers and studios must incorporate into budgets and contracts.
Five recommended moves for 2026
-
Run controlled experiments on monetization hybrids. Test microtransaction-first titles alongside timed subscription windows to identify highest LTV cohorts before large-scale rollouts.
-
Invest selectively in AI-assisted tooling but protect premium IP. Use AI to lower marginal production costs on high-volume slates, while reserving higher-budget human-centric shoots for flagship franchises.
-
Secure distribution partnerships that combine discovery and revenue share. Favor partners offering marketing levers and cross-border promotion rather than pure hosting.
-
Integrate compliance and guild negotiation into pre-production. Treat labeling, content review, and talent contracts as strategic line items that influence scheduling, costs, and release tactics.
-
Adopt an acquisition pipeline for tech and IP. Prioritize targets that enhance production velocity, localization capability, or proprietary audience analytics rather than raw content libraries alone.
How PW Consulting can accelerate your 2026 agenda
Our report is designed as an operational toolkit for executives: from CFOs building content budgets to CMOs optimizing acquisition spend, and from studio heads evaluating production models to corporate development teams screening M&A. The report’s datasets, scenario models, and playbooks translate market-level growth forecasts into executable strategies for 2026 decision cycles.
Note on proprietary detail: This article highlights the report’s major findings and strategic implications but intentionally omits granular segment tables and regional splits to encourage direct engagement with the full dataset and accompanying Excel models. Those detailed segment-level breakouts, company-level revenue estimates, and modelable outputs are available on the report’s source page for subscribers and enterprise clients.
For a copy of the full Paid Micro Short Drama Production Market report, including interactive financial models, company scorecards, and the complete segmentation breakdown used to inform 2026 planning, visit our official report page or contact PW Consulting’s industry desk for a briefing.
For detailed analysis of this topic, please visit the official page: Paid Micro Short Drama Production Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Cloud Backup System Market to Expand from USD 7.15 Billion (2025) to USD 15.08 Billion by 2032 at an 11.25% CAGR
By pmarketresearch, 2026-07-13
Cloud Backup System Market 2026: Strategic Imperatives from PW Consulting’s Latest Market Report
As enterprises reset priorities for 2026, PW Consulting’s new Cloud Backup System Market report delivers the high‑fidelity, decision‑ready intelligence leaders need to allocate capital, redesign operations, and negotiate supplier engagements. Anchored on a 2025 base year and projecting through 2032, our analysis synthesizes market sizing, competitive dynamics, regulatory pressure, and infrastructure cost drivers to illuminate where backup investments will generate the greatest risk‑adjusted returns. The market’s trajectory — from a USD 7,150 Million base in 2025 toward an expected USD 15,083 Million by 2032 at a compound annual growth rate of 11.25% — underpins the urgency and scale of decisions IT and security executives must make in 2026.
Cloud Backup System Market
Why this report matters for 2026 decision cycles
-
Accelerated adoption and operational complexity: Public cloud adoption, hybrid architectures, and SaaS proliferation have amplified backup surface area and recovery expectations. Our report translates macro growth into executable roadmaps for storage architects and resilience leaders.
Cloud Backup System Market -
Capital and operating tradeoffs: With rising data center construction and energy costs, capital planning now intersects with TCO of backup strategies. We provide models that map backup architecture choices to multi‑year cost outcomes and carbon/energy footprints.
Cloud Backup System Market -
Regulatory and sovereignty constraints: Data sovereignty, evolving energy reporting requirements, and sectoral privacy rules are reshaping where and how backups can be stored. The report frames compliance‑first backup architectures to prevent costly retrofits.
-
Cyber resilience as a boardroom priority: Ransomware and supply‑chain risk make recovery time objectives (RTOs) and immutable/air‑gapped designs procurement imperatives. Our frameworks prioritize resilience investments by business‑impact and recovery criticality.
What the report contains — practical assets for immediate use
PW Consulting built this report to be prescriptive, not just descriptive. Clients receive a layered suite of tools and analyses that translate market insight into execution plans:
-
Market sizing and trend narrative (2020–2025 history; 2026–2032 forecast) with scenario variants that stress‑test slower vs. faster cloud adoption paths.
-
Strategic vendor scorecards and procurement playbooks — comparative matrices that evaluate solution fit across resilience posture, integration with major cloud providers, operational automation, and cost per TB at various recovery SLAs.
-
Deployment and migration roadmaps for three archetypal enterprise profiles (cloud‑native, hybrid‑first, and regulated‑data), including phased milestones, KPIs, and risk checkpoints.
-
TCO and ROI modeling toolkit (spreadsheet‑based) that incorporates energy, facility, and labor cost assumptions to compare on‑prem, cloud, and hybrid backup scenarios over 5–7 year horizons.
-
Compliance and sovereignty decision trees that align backup locality, encryption, and access controls to major regulatory frameworks and sectoral mandates.
-
Operational playbooks for ransomware‑ready backups: retention policies, immutable storage patterns, air‑gap options, and validation cadences designed for rapid recovery and forensic readiness.
-
Vendor negotiation templates and SOW guardrails to secure resilience guarantees, clarify SLAs for point‑in‑time restore, and codify responsibilities across cloud and managed service partners.
Key market dynamics shaping vendor and customer strategies
Several structural forces are converging on the cloud backup market in 2026, raising the strategic stakes for buyers and vendors alike:
-
Energy and infrastructure cost pressures: Data center construction and operational costs are rising, and industry benchmarking indicates material increases in cost per megawatt. This drives interest in cloud‑native offload and in strategies that reduce long‑term on‑prem footprint.
-
Regulatory tightening on energy metrics and data locality: Regional directives now require reporting on power and water efficiency in data facilities, and data sovereignty rules continue to incentivize localized or edge deployments for critical backups.
-
Moderate market concentration: Market concentration metrics show a landscape where leading suppliers command a meaningful share but do not create a closed oligopoly — a pattern that favors differentiated vendors and solution specialization.
-
Security and resilience innovation: Vendors are embedding cybersecurity features — from immutable vaults to integrated scanning and recovery orchestration — responding to buyer demand for integrated protection stacks.
Competitive landscape — who to watch and why
The report includes an in‑depth competitive assessment of incumbent cloud providers and specialist backup vendors. Our analysis highlights capabilities, strategic positioning, and where each provider is likely to win or struggle as buyer needs evolve.
-
Amazon Web Services (AWS): AWS Backup continues to centralize policy‑based protection across AWS services and hybrid endpoints, emphasizing automation and ransomware recovery capabilities. Their scale and integration remain core advantages for cloud‑centric enterprises.
-
Microsoft Corporation: Azure Backup’s tight integration within Microsoft’s ecosystem makes it a default choice for enterprises with heavy Microsoft footprints, particularly where unified identity and compliance controls matter.
-
Google LLC: Google’s Backup and DR offerings have advanced multi‑region vaults and increased backup frequency options, reinforcing its appeal to cloud‑native workloads with strict recovery windows.
-
Veeam Software: Veeam’s platform focus on hybrid protection and expanded security features positions it as a leader for organizations seeking cross‑platform recovery and ransomware scanning across cloud and on‑prem assets.
-
Commvault Systems: Emphasizing unified data protection and cyber resilience, Commvault’s partnerships and air‑gap features cater to enterprises that prioritize defensibility and regulatory alignment.
-
Rubrik, Druva, Cohesity: These specialists continue to push automation and cloud‑native management models, often offering faster time‑to‑value for hybrid and SaaS backup use cases.
-
Acronis, Veritas, Backblaze, Barracuda: Each brings niche strengths — from cyber‑integrated backup to cost‑effective cloud storage options and focused SaaS/email protection — enabling targeted procurement strategies.
Recent vendor developments further validate trends we track. For example, product updates and releases in early‑to‑mid 2026 expanded scanning and cross‑platform coverage, while strategic partnerships have deepened integration between backup specialists and major cloud platforms. These moves accelerate buyer expectations for interoperability, automated recovery testing, and partner‑mediated managed services.
Strategic playbook for enterprise leaders in 2026
For CIOs, CISOs, and procurement leaders planning budgets and vendor selections this year, PW Consulting recommends a three‑track approach:
-
Stabilize: Harden critical backups with immutable storage, validated air‑gaps, and defined recovery exercises for top business processes. Make these non‑negotiables in contracts and SLAs.
-
Optimize: Use a phased TCO migration plan to rebalance on‑prem and cloud backups, factoring in projected energy and construction cost inflation. Apply lifecycle policies and deduplication to rein in storage growth.
-
Differentiate: Invest in automation, metadata‑driven recovery, and integrated cyber‑forensics to reduce mean time to recovery and lower operational overhead. Prioritize vendors that demonstrate cross‑cloud orchestration and transparent cost models.
How PW Consulting’s report accelerates procurement and architecture choices
We designed the report to shorten vendor selection cycles and de‑risk architectural pivots. Practical outputs include weighted vendor scorecards, sample RFP language, and validated TCO scenarios that executives can present to finance and audit committees. Our scenario planning also helps boards understand the funding and operational commitments required under differing growth and regulatory outcomes.
Accessing the full intelligence
This release is intentionally a strategic “preview.” To preserve actionable value for subscribers and to support confidential procurement workflows, we have withheld granular regional and application segmentation figures from this public summary. The full report contains detailed sub‑segment data, downloadable financial models, and complete vendor benchmarking tables that are essential for procurement negotiation and technical specification workshops.
For organizations evaluating backup strategy in 2026, the full PW Consulting Cloud Backup System Market report is the operational playbook needed to convert market momentum into durable resilience. Visit our report page to unlock the complete dataset, download the TCO toolkit, and schedule a briefing with our analysts.
For detailed analysis of this topic, please visit the official page: Cloud Backup System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Closeouts Market to Grow from USD 285.5 Billion in 2025 to USD 454.0 Billion by 2032 at 6.85% CAGR; Online Liquidation Platforms Command USD 165.4 Billion
By pmarketresearch, 2026-07-13
Closeouts Market 2026: Strategic Playbook and Market Intelligence — PW Consulting Preview
Executive summary
The closeouts market — the industrial ecosystem that converts overstock, customer returns, and surplus consumer goods into recoverable value — is entering a decisive phase. Our new Closeouts Market report (base year 2025) synthesizes five years of historical trends (2020–2025) and delivers an operationally-focused forecast for 2026–2032. At the macro level, the market expanded meaningfully in recent years (from roughly USD 250 billion in 2023 to USD 285.5 billion in 2025) and is projected to continue growing: our model anticipates the market crossing the USD 300 billion threshold in 2026 and reaching approximately USD 454 billion by 2032, at a compound annual growth rate of 6.85% over the forecast period.
Closeouts Market
This release functions as a strategic “trailer”: it demonstrates the analytical depth and actionable orientation of the full report while deliberately withholding granular segmentation tables and proprietary modeling outputs — content that is available on the report landing page for decision-makers conducting vendor selection, investment due diligence, or channel redesign in 2026.
Closeouts Market
Why this matters for enterprise decisions in 2026
- Capital allocation: The projected mid-single-digit CAGR underscores continued opportunity for scale players and niche specialists alike. Boards and CFOs evaluating investments in liquidation platforms, warehousing, or returns processing need model-ready forecasts and scenario stress tests to size capex and working capital.
- Channel strategy: Retailers and brands seeking to optimize recoveries must decide where to direct inventory (direct secondary retail, auction, online liquidation marketplaces) — a choice that materially affects margin, brand control, and speed-to-cash.
- Risk management: Macro headwinds — from tariff pass-through on imported consumer goods to retailer insolvencies increasing inventory inflows — are forcing a reappraisal of sourcing, pricing, and compliance frameworks.
What the PW Consulting Closeouts Market report delivers
We designed the study for operators, corporate strategists, private equity sponsors, and logistics partners who require practical, transaction-ready intelligence. Highlights include:
Closeouts Market
- Market architecture and dynamics: concise maps of value pools and liquidity channels, with scenario-based forecasts for 2026–2032 calibrated to macroeconomic and trade-policy inputs.
- Operational playbooks: step-by-step guides for warehouse-to-consumer workflows (inspection, grading, listing, fulfillment), plus performance benchmarks for return-to-revenue timelines.
- Channel optimization toolkit: decision matrices to choose between auction, marketplace, pallet sale, and direct-secondary retailing given inventory quality, velocity targets, and brand exposure constraints.
- Technology adoption blueprints: ROI frameworks for investments in AI-driven grading, automated sorting, dynamic pricing engines, and integrations that reduce disposition cycle time and shrinkage.
- M&A and partnership framework: diligence checklists, valuation multipliers calibrations for platform consolidations, and a playbook for integrating distinct operating models (auction vs. pallet vs. retail outlet).
- Regulatory & tariff impact module: practical guidance on hedging, pricing pass-through, and compliance considerations as trade policy evolves.
- Data products & dashboards: curated datasets and KPIs (transaction velocity, recovery rate, lot yield curves) designed for CFOs and heads of liquidation — note: detailed segmentation tables and raw datasets are available exclusively in the full report.
Competitive landscape — strategic profiles and implications
The closeouts ecosystem is characterized by numerous specialized operators and a modest level of concentration. Top-three firms collectively control under one-fifth of industry throughput, and the top-five remain below one-quarter of total capacity — a structure that favors both scale-driven consolidation and continued niche innovation.
- Direct Liquidation (United States — directliquidation.com)
Position: Market-facing leader with deep retailer/manufacturer partnerships and an auction/wholesale playbook. Strategic implication: its direct relationships with brands give it preferential access to name-brand inventory and data — a model that other platforms emulate through partnerships or white-label arrangements.
- B-Stock (United States — bstock.com)
Position: Large online wholesale marketplace connecting buyers to returned and overstocked goods from major retailers. Strategic implication: B-Stock’s value comes from marketplace liquidity and buyer network effects. For enterprises, marketplace presence accelerates velocity but requires disciplined grading and seller-side governance to protect brand equity.
- Liquidation.com (United States — liquidation.com)
Position: Auction-based platform focused on surplus consumer goods. Strategic implication: auction mechanics can maximize recoveries for heterogeneous lots but demand robust logistics and buyer screening to reduce transaction costs.
- Overstock Trader (United States — overstocktrader.com)
Position: Facilitates direct relationships between brands and off-price retailers/wholesalers. Strategic implication: direct B2B matching is increasingly attractive to sellers prioritizing speed and margin retention over market-wide discovery.
- BULQ (United States — bulq.com)
Position: Pallet and truckload wholesale supplier with emphasis on standardized SKUs and frequent lot cycles. Strategic implication: BULQ’s standardized units reduce buyer friction and enable consistent pricing — a model attractive to resellers scaling online.
- Kole Imports (United States — koleimports.com) & Similar Import/Distributor Players
Position: Direct importer and large-scale distributor supplying general merchandise and closeouts to off-price channels. Strategic implication: control of import/distribution pathways remains a differentiator where tariff exposure and freight cadence materially influence landed cost.
- Smaller B2B Specialists (e.g., Total Surplus Solutions, Countryside Closeouts, Global Distributors, UpLiquidation)
Position: Regional and category-focused players that provide micro-market access to resellers. Strategic implication: these firms are fertile targets for roll-up strategies and for acquirers seeking last-mile market coverage and specialized sourcing.
Recent industry dynamics shaping 2026 strategies
- Trade-policy and tariff pressure:
U.S. tariffs on imported consumer goods remain a salient driver of landed-cost volatility. Recent analyses indicate substantial pass-through to consumers in many categories. For liquidation stakeholders, tariffs alter the calculus of resale pricing, import arbitrage plays, and cross-border flows — all factors we model in the report’s scenario set.
- Inventory influx from retailer distress and conservative consumer spend:
A wave of higher overstock levels, amplified by retailer restructurings and more cautious households, is feeding supply into liquidation channels. This raises both opportunity (higher available volumes) and risk (downward pressure on realized prices and longer holding periods).
- Event-driven sourcing and network effects:
Industry gatherings such as ASD Market Week (March 2026), which showcased 250+ closeout suppliers, continue to accelerate deal flow, cross-border introductions, and product sourcing partnerships. Trade events, when combined with digital marketplaces, are proving instrumental in matching supply surges to buyer appetite.
Strategic imperatives for 2026 — what leaders should do now
Based on our modeling and field interviews, PW Consulting recommends a prioritized set of actions for executives planning capital and operational moves in 2026:
- Invest in grading and pricing automation:
Accuracy and speed in SKU condition assessment directly increase recovery rates. Pilots of AI-assisted grading and dynamic pricing should be deployed in Q1–Q2 2026, with 6–12 month ROI targets tied to reduced hold time and improved lot yields.
- Adopt a portfolio approach to disposition channels:
Rather than exclusive reliance on a single channel, build rules-based routing that matches inventory quality and velocity targets to auction, marketplace, pallet, or direct B2B sales to maximize blended recovery.
- Hedge tariff and logistics exposure:
Implement layered pricing clauses, revisit sourcing geographies, and contract freight capacity to moderate landed cost swings. Consider nearshoring or bonded-warehousing strategies for categories with high tariff sensitivity.
- Prepare for consolidation and M&A-enabled scale:
Fragmentation creates roll-up opportunity. Build an M&A playbook focused on integrating logistics, standardizing grading, and consolidating buyer databases to capture network effects at scale.
- Elevate compliance and reputation controls:
Stronger brand owners are increasingly selective about disposition channels. Implement traceability, quality gates, and brand-protection SLAs to maintain long-term access to high-value supply.
Concluding perspective and next steps
The closeouts market’s trajectory to 2032 presents a mix of durable growth and intensifying operational complexity. Our forecast and playbooks are designed to help executives convert that complexity into defensible advantage — whether through technology-led operations, selective M&A, or smarter channel engineering.
PW Consulting’s full Closeouts Market report includes the granular segmentation, proprietary recovery-rate matrices, downloadable datasets, and step-by-step integration templates that enterprise teams and investors demand. This preview highlights the strategic contours; the full report supplies the tactical depth required to make high-confidence decisions in 2026.
To access the full dataset, scenario models, and the operational toolkits referenced here, please visit the report landing page for purchase and instant access to supplementary materials and executive briefings.
For detailed analysis of this topic, please visit the official page: Closeouts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SMD Common Mode Chokes Market to Grow at 6.5% CAGR, Rising from USD 850 Million in 2025 to USD 1.32 Billion by 2032
By pmarketresearch, 2026-07-13
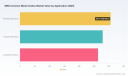
SMD Common Mode Chokes Market — Strategic Preview for 2026 Decision‑Makers
Executive summary
PW Consulting’s latest SMD Common Mode Chokes Market study (base year: 2025; historical: 2020–2025; forecast: 2026–2032) provides decision‑ready intelligence for procurement heads, product roadmap teams, and corporate strategy leaders preparing for 2026 and beyond. The market has shown steady expansion from an estimated USD 620.4 Million in 2020 to USD 850.0 Million in 2025 and is projected to continue growing through the forecast window at a compound annual growth rate (CAGR) of 6.5%, reaching an overall market size of roughly USD 1.32 Billion by 2032. This briefing highlights the strategic implications of those trends without revealing the proprietary segmentation tables included in the full report — a deliberate “trailer” to underpin executive decisions while preserving the granular intelligence available in the paid study.
Smd Common Mode Chokes Market
Why this matters for 2026
- Supply chain, design, and sourcing choices made in early 2026 will determine product cost curves and qualification schedules across the 2026–2032 growth window.
- Component manufacturers and systems OEMs face a market that is expanding but not homogeneous: product families, materials, and application requirements are differentiating winners from laggards.
- Raw material volatility and constrained lead times for advanced core materials create both operational risk and arbitrage opportunities for firms that align sourcing strategy with product roadmaps.
Market dynamics driving the next phase of growth
The SMD common mode choke market is being shaped by converging forces across end markets and supply chains. Demand drivers include ongoing electrification and higher power-density electronics in automotive and industrial systems, persistent emphasis on EMI/EMC compliance in telecom and datacom equipment, and continuous miniaturization and integration in consumer devices. These structural drivers underpin the multi‑year CAGR and the sustained expansion of the addressable market.
Smd Common Mode Chokes Market
On the supply‑side, ferrite cores and copper conductors remain the dominant cost and capacity levers. Advanced magnetic materials — including nanocrystalline cores used in higher‑performance chokes — have materially longer standard lead times (typical quoting ranges of 8–12 weeks and stretching to 16–22 weeks during constrained periods). Price volatility in ferrite and copper, influenced by broader commodities cycles and geopolitics, directly impacts BOM costs, margin planning, and contract negotiation windows for component buyers.
Smd Common Mode Chokes Market
Regulatory and test frameworks continue to codify requirements for common mode chokes in power applications; industry reference standards such as IEC/EN 60938‑2 remain pivotal for design validation and supplier qualification. The manufacturing footprint is concentrated in Asia‑Pacific hubs with strong capabilities for high-volume SMT processing and magnetic materials; this concentration is a factor in both cost leadership and geopolitical risk models.
Competitive landscape — what the leading suppliers signal
The vendor field combines global passive giants, specialized EMC players, and targeted power‑component suppliers. Key suppliers reviewed in the report include TDK Corporation, Murata Manufacturing, YAGEO Group (Pulse Electronics), Bourns, Vishay, Schaffner, Eaton, Littelfuse, Sumida, and Coilcraft. Our comparative view synthesizes product portfolios, technical differentiation, route-to-market, and go‑to‑design strategies.
- TDK Corporation (Tokyo, Japan) — TDK’s SurfIND family and similar high‑current SMD chokes (notably rated up to the mid‑30A range in recent launches) emphasize high thermal robustness and reflow compatibility for telecom and industrial power modules. Strategically, TDK reinforces the premium high‑current segment and is a go‑to for OEMs prioritizing thermal and mechanical reliability.
- Murata Manufacturing (Kyoto, Japan) — Murata’s broad SMT choke portfolio targets EMC compliance across diverse current ratings and package sizes. Murata remains competitive on miniaturization and integration for consumer and compact power supplies.
- YAGEO Group / Pulse Electronics (Taipei, Taiwan) — YAGEO’s introduction of high‑current designs with specialized core geometries signals an intent to capture DC/DC converter and power line design wins where compactness and current handling are prioritized.
- Bourns, Inc. (Riverside, USA) — With AEC‑Q200 compliant lines, Bourns is positioned for automotive design‑ins and the qualification cycles required by tier‑1 suppliers.
- Vishay, Schaffner, Eaton, Littelfuse, Sumida, Coilcraft — Each brings differentiated strengths: Vishay’s high‑current components for EMI suppression; Schaffner’s EMC specialization; Eaton’s system‑level power management alignment; Littelfuse’s protective integration; Sumida’s broad consumer/industrial range; and Coilcraft’s high‑frequency lineups. Collectively these suppliers define a competitive topology where technical depth, regulatory compliance, and geographic manufacturing footprints matter more than raw price alone.
Recent product developments underscore tactical moves by incumbents to secure design wins: TDK launched a high‑current SurfIND SMD common‑mode series in early 2025 targeting telecom and industrial power applications, and YAGEO released a high‑current ER19‑core SMD choke in mid‑2025 aimed at DC/DC converter lines. These launches indicate supplier focus on higher‑current and thermal robustness segments — areas where OEMs are increasingly designing to consolidate BOMs and improve power density.
Market structure and competitive intensity
The market exhibits moderate concentration: the top three suppliers account for a material share of industry revenue while the top five consolidate over half the market. That structure creates strategic implications for buyers and potential entrants — scale advantages in distribution, certification support, and R&D investment are meaningful, yet there remains room for focused innovators offering differentiated core materials or integrated protection features.
What the PW Consulting report provides (practical deliverables)
- Validated market sizing (2020–2025 historical; 2026–2032 forecast) with scenario modeling for downside and upside demand shocks.
- Segmentation by region, product type (e.g., wire‑wound, multilayer, thin‑film architectures), and application verticals — provided with demand drivers and discreet, actionable guidance for targeting design‑in opportunities. (Note: segmentation tables and granular shares are available in the full report.)
- Supplier benchmarking and product scorecards — performance, thermal ratings, current handling, packaging, qualification status (including automotive/AEC‑Q lines), and IP differentiators.
- Supply chain heatmaps showing lead times by core material, strategic single‑sourcing risks, and a recommended dual‑sourcing prioritization matrix.
- Raw material price sensitivity and BOM‑level cost models to support sourcing negotiations, hedging choices, and price‑pass‑through assessments.
- Regulatory and test matrix aligned to IEC/EN frameworks and common regional certification paths.
- Commercial playbooks for procurement and product teams: RFQs, qualification timelines, sample volume strategies, and contract language to secure capacity in tight market windows.
- Strategic opportunities and M&A signal map for corporate development teams — target profiles, partnership levers, and valuation considerations for bolt‑on acquisitions in magnetic materials and choke assembly capacity.
How to apply the insights in 2026
- Procurement: rebase supplier contracts with 12–24 month hedging on ferrite and copper inputs; prioritize suppliers with confirmed nanocrystalline supply for high‑performance SKUs.
- Product management: align product roadmaps to the growth pockets identified in our demand model; accelerate design‑in of high‑current or thermally enhanced chokes where applicable.
- Operations: adjust buffer stocking policies and lead‑time assumptions (plan for extended nanocrystalline lead times during constrained periods) and reconfigure safety stock by SKU criticality.
- Regulatory/compliance teams: incorporate IEC/EN validation gates early in the design cycle to avoid late rework and long qualification loops for automotive and industrial segments.
- Corporate development: use the vendor scorecards and concentration analysis to prioritize partnerships and inorganic options where market concentration and capability gaps create strategic openings.
Why PW Consulting’s study is decision‑ready
The report combines primary interviews with suppliers and OEMs, proprietary shipment and pricing indices, and bottom‑up BOM modeling to produce forecast outputs that are directly actionable for 2026 planning. Our methodology explicitly models material lead‑time variability and commodity price swings, enabling robust scenario planning rather than a single static projection. The result is a toolset that supports procurement negotiations, product qualification timelines, capital allocation decisions, and M&A screening.
Next steps and access
This release is a strategic preview intended to orient executive decision‑making for 2026. The full report contains the comprehensive segmentation tables, granular regional and application analyses, vendor scorecards, downloadable datasets, and the step‑by‑step procurement playbooks that underpin the recommendations above. PW Consulting clients and subscribers can access the complete report and editable models through our research portal or contact their account lead for a tailored briefing and scenario run‑through.
For organizations preparing sourcing strategies, product roadmaps, or M&A activity in 2026, the intelligence in the full SMD Common Mode Chokes Market report will materially shorten time‑to‑decision and reduce execution risk — particularly in an environment of material lead‑time strain and sustained demand growth.
For detailed analysis of this topic, please visit the official page: Smd Common Mode Chokes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Data Center Battery Backup Unit Market to Reach USD 4.33 Billion by 2032, Growing at a 8.15% CAGR
By pmarketresearch, 2026-07-13
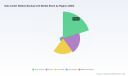
Data Center Battery Backup Unit Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As hyperscale compute, AI workloads and sustainability mandates reshape data center economics, battery backup choices have moved from an engineering afterthought to a board-level strategic decision. PW Consulting’s latest market study — built on an updated base year of 2025 and a seven-year forecast horizon through 2032 — synthesizes historical performance (2020–2025) and forward-looking scenarios to equip CIOs, data center operators, infrastructure investors and procurement leaders with actionable intelligence for 2026.
Data Center Battery Backup Unit Market
Market trajectory at a glance (why 2026 matters)
The global data center battery backup unit market has demonstrated steady expansion: from a multi-year history of recovery and reinvestment following 2020, the market reached USD 2,500 Million in 2025. Our modeling anticipates sustained compound annual growth of 8.15% across the 2026–2032 forecast window, driving the market toward a materially larger opportunity by 2032. That trajectory reflects accelerating investment in resilient power architectures, the commoditization of certain battery chemistries, and the emergence of new, workload-driven requirements (notably edge and AI clusters) that change sizing, thermal management and service expectations.
Data Center Battery Backup Unit Market
What this report delivers — practical, decision-ready outputs
- Scenario-based demand models that translate macro drivers (compute density, PUE targets, resiliency SLAs) into battery capacity and service requirements at site, campus and portfolio levels.
- Vendor scorecards and a selection matrix that map product attributes (chemistry, cycle life, thermal tolerance, modularity, warranty and service models) to common data center archetypes.
- Procurement playbooks and contract templates designed to shorten lead times, mitigate tariff exposure and preserve lifecycle performance — including guidance on service-level KPIs and replacement plans.
- TCO and LCOB (Levelized Cost of Backup) calculators that isolate CapEx / OpEx tradeoffs for lead-acid, lithium-ion and hybrid architectures under multiple energy-price and depreciation assumptions.
- Supply-chain risk heatmaps and mitigation blueprints focused on raw material concentration, cell and module bottlenecks, and long-lead electrical equipment that can derail expansion timelines.
- Site-level retrofit pathways and integration checklists for migrating from legacy VRLA/lead-acid systems to modern li-ion or hybrid solutions without compromising uptime.
- Environmental and regulatory impact matrices that translate tariffs, recyclability requirements and emissions reporting into procurement and design constraints.
- Illustrative case studies and operator interviews that expose recurring failure modes, maintenance strategies and cost-optimization tactics.
Competitive landscape — positioning and strategic moves
The supplier ecosystem is a mix of legacy battery specialists, UPS platform integrators and newer chemistry innovators. Market concentration metrics indicate moderate consolidation: the top three suppliers account for a meaningful portion of the market while the top five approach half the market — evidence that scale matters, but niche differentiation still wins deals.
Data Center Battery Backup Unit Market
- EnerSys (Reading, Pennsylvania): a longstanding provider of advanced lead-acid solutions optimized for high-temperature operation and grid support. EnerSys has reported strengthened lead-acid demand in 2026 and is actively trialing lithium-based systems — signaling a hybrid strategy that leverages installed base strength while testing future-facing chemistries.
- C&D Technologies (Columbus, Georgia): legacy capabilities in VRLA and pure lead AGM designs tailored to UPS environments. Their experience in hyperscale and colocation contexts positions them as a pragmatic incumbent for retrofit and replacement projects.
- Saft (Levallois-Perret): emphasizes turnkey lithium-ion systems and large-scale energy storage solutions. Their capability to deliver integrated, high-MW systems makes them a natural partner for campus-level resilience projects.
- Schneider Electric (Rueil-Malmaison): combines modular UPS platforms with lithium options, enabling operators to balance footprint, scalability and lifecycle costs across different tiers and densities.
- Eaton (Dublin): focuses on integrated UPS + battery solutions with attention to efficiency and maintainability, appealing to operators seeking consolidated supply and single-point SLAs.
- Vertiv (Westerville, Ohio): slots into high-efficiency, rack- and room-level UPS categories and has recently pursued partnerships and product innovations for liquid-cooled and AI-optimized platforms.
- Mitsubishi Electric (Tokyo) and ABB (Zurich): both present strong modular systems suitable for large-scale, AI-ready deployments where power density and redundancy architectures are critical.
Together, these incumbents and challengers form a dynamic competitive set where product differentiation (thermal tolerance, modularity, cell chemistry) and service economics (warranties, rapid-swapping, predictive maintenance) increasingly determine procurement outcomes.
Supply-chain and cost headwinds — what keeps procurement teams up at night
- Raw material concentration: In 2025–2026, supply chain data shows a high geographic concentration of critical cell and cathode production, creating a structural risk for lithium-based options. Operators should assume periodic sourcing shocks and plan dual-source strategies or inventory cushions for critical projects.
- Price bands and installed costs: Benchmarking indicates a wide range for data center-grade cells and installed battery energy systems. These ranges compress or expand quickly with shifts in raw material pricing, tariffs and logistics costs — making scenario-based TCO modeling essential.
- Regulatory and trade dynamics: Tariffs and import controls introduced in recent years materially affect landed cost and vendor selection; nearshoring or negotiated long-term supply agreements may be necessary to stabilize costs.
- Long-lead electromechanical items: Critical path items such as large power transformers can face multi-year lead times in high-build environments; battery procurement timelines must be aligned with these items to avoid project schedule risk.
Strategic recommendations for 2026 decision-makers
For executives and practitioners planning capital and operations in 2026, PW Consulting recommends a pragmatic, portfolio-based approach:
- Adopt a tiered procurement strategy: standardize on modular, swappable battery racks where possible; reserve specialized chemistries for high-density or mission-critical tiers.
- Use hybrid deployments as an interim play: combine proven lead-acid installations for baseline backup with targeted lithium deployments where space, weight and fast recharge are differentiators.
- Lock supply early for long-lead items and hedge exposure through multi-year purchase agreements or collaborated vendor stocking to mitigate tariff and lead-time risk.
- Insist on vendor transparency: require cell origin declarations, recycled content reporting and failure mode data as part of RFPs to reduce total cost surprises over the warranty period.
- Run portfolio-level TCO and risk sensitivity analyses, not only site-by-site cost comparisons — this reveals where centralized maintenance, spare pooling or lifecycle buybacks reduce overall expense.
- Plan for service ecosystems: prioritize suppliers offering rapid swap programs, predictive diagnostics and on-site spares logistics to compress MTTR and preserve SLA margins.
- Align battery selection with sustainability targets: evaluate lifecycle emissions and end-of-life recycling pathways as procurement criteria rather than afterthoughts.
- Invest in integration and training: battery management systems (BMS), thermal management and commissioning protocols are often the decisive elements in long-term reliability.
Why PW Consulting’s report is strategically valuable
Our study is designed as a practical playbook for 2026 decisions. Beyond headline market growth — which shows an expanding and durable opportunity for backup battery systems — the report supplies executable artifacts: contract clauses, swap-and-upgrade roadmaps, and interactive TCO models you can apply to your portfolio within days. We combine vendor benchmarking with raw-material and logistics intelligence to surface not just what the market looks like, but how to win and de-risk deployments operationally and commercially.
Importantly, while this preview outlines market dynamics and competitive positioning, the full report contains the detailed subsegment analytics, regional breakdowns, capacity-level economics and downloadable financial models that enterprise buyers and investors use to finalize 2026 procurement and capital plans.
Next steps
For operators preparing CAPEX cycles or investors underwriting data center portfolios in 2026, the immediate priorities are clear: finalize chemistry and modularity choices, secure long-lead supply, embed lifecycle and service economics into procurement, and pilot targeted lithium deployments where the operational benefits justify the premium. PW Consulting’s full Data Center Battery Backup Unit Market report provides the granular segmentation, vendor scorecards and spreadsheet models required to operationalize these priorities.
To access the complete dataset, interactive models and procurement playbooks, visit the PW Consulting report page or contact our industry desk for a tailored briefing and a demo of the calculators and risk maps included in the full deliverable.
For detailed analysis of this topic, please visit the official page: Data Center Battery Backup Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Off‑Grid Solar Street Light Market to Reach USD 4,185.43 Million by 2032 at 7.95% CAGR (2026–2032 Forecast); Asia‑Pacific Leads with USD 1,049.25M
By pmarketresearch, 2026-07-13
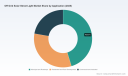
Off‑Grid Solar Street Light Market 2026: Strategic Imperatives for Executives — PW Consulting Industry Brief
PW Consulting's latest Off‑Grid Solar Street Light Market report (base year 2025, forecast 2026–2032) arms executives with pragmatic intelligence for making high‑stakes decisions this year. The global market reached approximately USD 2,450 Million in 2025 and, on the trajectory mapped in our study, is projected to expand at a compound annual growth rate (CAGR) of about 7.95% through the 2026–2032 forecast window — a growth profile that turns operational choices made in 2026 into five‑year differentiators.
Off-Grid Solar Street Light Market
Why 2026 is a Pivot Point
-
Policy and incentive realignment. Recent changes to incentive frameworks — including the expiration of select residential tax credits and time‑bound conditions for commercial credits — compress the window for projects that rely on legacy subsidy structures. Organizations that recalibrate investment models now will avoid stranded assumptions later in the forecast period.
Off-Grid Solar Street Light Market -
Input‑cost volatility meets technological substitution. Declines in polysilicon pricing and ongoing adjustments in cathode material costs for LiFePO4 batteries are creating asymmetric effects across bill‑of‑materials (BOM). Lower module cost pressure is offset in part by battery market normalization; the net effect is an evolving unit economics landscape that favors design and procurement agility.
Off-Grid Solar Street Light Market -
Product design consolidation and intelligence. The rapid maturation of integrated (all‑in‑one) product architectures and embedded power‑management software (including AI‑driven load optimization) is redefining performance benchmarks for reliability, total cost of ownership (TCO), and serviceability in off‑grid contexts.
What This Report Delivers (Practical, Actionable Content)
-
Robust market sizing and scenario forecasting — baseline and multiple downside/upside scenarios calibrated to 2026 policy and commodity states; all values in USD Million with a transparent methodological appendix.
-
Decision frameworks for buyers and suppliers — procurement checklists, contract templates for performance‑based SLAs, and vendor evaluation scorecards that convert technical specs into risk‑adjusted lifecycle costs.
-
Technology and product benchmarking — end‑to‑end comparisons of architecture families (integrated vs. split), battery chemistries, and smart energy controls, including field performance indicators and failure‑mode analysis.
-
Supply chain risk map and mitigation playbook — critical paths, single‑sourced nodes, and hedging strategies informed by recent raw‑material movements and logistics sensitivity tests.
-
Competitive landscape intelligence — strategic profiles, capability matrices, and a tracking dashboard of M&A, product launches, and landmark deployments to anticipate moves by peers and new entrants.
-
Commercial playbooks — pricing tier guidance, financing structures (including off‑balance sheet project constructs), and go‑to‑market options for municipal, rural, and commercial customers.
Strategic Takeaways for 2026 Decision‑Makers
-
Prioritize modularity and firmware upgradability. Given the pace of battery and power‑electronics improvements, designs that allow in‑field upgrades materially lower long‑term TCO and reduce obsolescence risk.
-
Revisit procurement timing. With polysilicon easing module costs but batteries exhibiting price adjustments, staged procurement (e.g., panel agreements with variable delivery vs. battery spot buys) can improve margins while preserving performance guarantees.
-
Embed intelligence as a value driver. Vendors offering proven AI‑driven power management and remote diagnostics enable lower operating expenses and faster fault resolution — differentiators in municipal procurement evaluations.
-
Plan for financing transitions. As certain public incentives phase or change structure, financing models that combine capex light options with performance guarantees will win more tenders during the near term.
Competitive Landscape — Who to Watch
The market remains commercially attractive and commercially diverse: global players with engineered solutions compete alongside specialized regional manufacturers and systems integrators. Our competitive chapter synthesizes corporate positioning, channel strategies, and technical strengths for rapid benchmarking.
-
Fonroche Lighting America (USA) — known for resilient all‑in‑one products with AI‑driven power management suited for off‑grid municipal projects ( https://www.fonrochesolarlighting.com/).
-
SEPCO Solar Electric Power Company (USA) — a long‑tenured supplier of high‑power off‑grid commercial systems focused on reliability in remote installations ( https://www.sepco-solarlighting.com/).
-
Greenshine New Energy (USA) — offers commercial‑grade outdoor LED systems with a recent strategic transaction that reshapes its production footprint and go‑to‑market scale ( https://www.streetlights-solar.com/).
-
Solar Lighting International (USA) — positions on high‑lumen solutions for parking and street applications with proven off‑grid performance since mid‑2000s ( https://www.solarlightingitl.com/).
-
Sunna Design (France) — emphasizes intelligent energy management systems for industrial and commercial off‑grid use cases ( https://solarlighting.com/).
-
EnGoPlanet , Streetleaf , ClearWorld , Solar Street Lights USA , and HeiSolar — each brings distinct strengths in manufacturing, systems integration, or regional distribution that matter for procurement and partnership decisions (see report for individual capability matrices and URL references).
Recent Industry Moves Illustrate the Direction of Play
-
Product innovations designed for higher‑traffic road applications and foldable all‑in‑one variants have entered the market, evidencing a push toward urbanization‑ready solutions.
-
M&A activity and asset transfers in early 2026 signal consolidation among mid‑tier manufacturers as they pursue scale and supply continuity.
-
Field deployments in Southeast Asian road projects highlight the importance of locally proven reliability for long‑term municipal contracts.
Supply Chain and Cost Dynamics — What to Model Now
-
Polysilicon pricing has moved downward in recent months, creating an opportunity to renegotiate module procurement terms and to model lower module BOM costs into pricing decks.
-
Battery cathode input costs have been adjusting; LiFePO4 supply and pricing should be modeled with scenario bands rather than point estimates given recent volatility.
-
Commercial‑grade off‑grid units in market practice show a wide per‑unit price band depending on specification and battery capacity; procurement teams should assess total lifecycle cost instead of headline per‑unit CAPEX to avoid late‑cycle surprises.
Procurement and Deployment Playbook (Concise Checklist)
-
Establish lifecycle KPIs up front: energy yield, autonomy hours, degradation expectations, and mean time to repair.
-
Require remote telemetry and firmware upgrade clauses for performance verification and post‑warranty management.
-
Insist on battery replacement and recycling terms to manage end‑of‑life costs and regulatory compliance.
-
Structure contracts with milestone‑based payments tied to verified performance to align supplier incentives.
How Executives Should Use This Report in 2026
-
CEOs and GMs — align product roadmaps and capital allocation against the report’s scenario outcomes to prioritize R&D and capacity investments that deliver the largest risk‑adjusted returns.
-
CPOs and procurement leads — use the negotiation playbooks and BOM sensitivity analyses to structure contracts that protect margins amid commodity swings.
-
BD and Sales leaders — apply our competitive matrices and value messaging templates to accelerate tender wins where intelligence‑enabled performance and service economics are required.
-
Investors and lenders — employ the report’s risk analysis and stress‑tested cash‑flow models to validate financing structures and inform covenants.
Next Steps and Where to Get the Full Dataset
This brief is intentionally selective: it demonstrates the analytical depth and actionable outputs PW Consulting delivers while reserving the full, granular segmentation tables, regional and application splits, and downloadable financial models for subscribers. For teams setting budgets, evaluating partners, or restructuring product portfolios in 2026, the full report provides the underlying datasets, scenario spreadsheets, and vendor scorecards needed to implement decisions with confidence.
Contact PW Consulting or visit our report page to request the full Off‑Grid Solar Street Light Market 2026–2032 report, schedule a private briefing, or license the data feed for internal decision systems. In a market growing at near‑8% CAGR and reshaped by policy and component dynamics, having the right intelligence this quarter will materially alter your five‑year outcomes.
For detailed analysis of this topic, please visit the official page: Off-Grid Solar Street Light Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Broadband Multilayer Ceramic Capacitors Market Reaches USD 2,150 Million in 2025, Signaling Strong Growth Ahead
By pmarketresearch, 2026-07-13
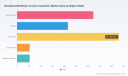
Broadband Multilayer Ceramic Capacitors Market — Strategic Insights for 2026 Decision‑Makers
PW Consulting today releases a focused strategic briefing derived from our full Broadband Multilayer Ceramic Capacitors (MLCC) Market report (base year 2025). The briefing distils the actionable intelligence that executives, product leaders, procurement heads and M&A teams need to set course for 2026 and beyond. At a market scale of USD 2,150.00 Million in 2025 and an expected compound annual growth rate (CAGR) of 7.5% over the 2026–2032 forecast window, the broadband MLCC segment is a fast‑moving, technology‑dense corner of the passive components industry with material implications for system design, supply‑chain resilience and competitive positioning.
Broadband Multilayer Ceramic Capacitors Market
Why this briefing matters now
-
Strategic timing: 2026 is the first full planning year after significant supply and pricing shocks in high‑end MLCCs. Procurement cycles, product roadmaps and capacity commitments made this year will determine cost basis and product availability into 2027–2028.
Broadband Multilayer Ceramic Capacitors Market -
Technology leverage: Broadband MLCCs sit at the intersection of RF, optical communications and power integrity. Small changes in dielectric formulation, ESR/Q and packaging footprints materially affect system BOMs and performance trade‑offs.
Broadband Multilayer Ceramic Capacitors Market -
Risk concentration: Premium broadband products are subject to extended lead times and raw‑material volatility. Structural constraints on capacity expansion mean near‑term supply discipline will reward well‑prepared buyers and vertically integrated suppliers.
What the full report delivers (practical, executable content)
-
Executive synthesis: concise strategic takeaways tied to financial and operational decisions — calibrated against the 2025 market base and the 2026–2032 forecast trajectory (7.5% CAGR).
-
TAM & addressable market frameworks: market sizing by node (broadband MLCCs versus other RF/MW passives), with model templates you can re‑parameterize for your product mix and regional exposures.
-
Technology roadmap: comparative performance matrices for Ultra‑Low ESR, High‑Q and specialized broadband MLCC architectures; recommended specification guardrails for telecom, aerospace, automotive and industrial applications.
-
Supplier scorecards and qualification playbooks: practical vendor evaluation templates, qualification checklists, RF test protocols and recommended long‑lead purchase clauses to shorten time‑to‑production.
-
Cost & pricing impact models: BOM sensitivity tools showing how dielectric price moves and lead‑time premia affect system margins and price elasticity under several market stress scenarios.
-
Supply‑chain risk matrix: mapped single‑point failures, alternate sourcing pathways, recommended inventory buffers (days of cover), and contract structures to mitigate 2026 delivery risks.
-
M&A and partnership playbook: target profiles, valuation heuristics and integration checklists for acquiring capabilities (manufacturing, IP, specialized product lines) versus partnering/licensing strategies.
-
Implementation toolkits: procurement negotiation scripts, technical spec templates, RF lab validation protocols, and a 12‑month tactical roadmap for engineering and supply teams.
Market dynamics shaping 2026 decisions
-
Demand drivers: Broadband MLCC demand continues to be pulled by optical communications, RF front‑end upgrades for higher bandwidths, and defense/aerospace programs requiring low insertion loss at mmWave frequencies. These application trends underlie the market’s steady expansion from the 2025 base toward the 2032 projection.
-
Raw material pressure: Barium titanate — the dominant dielectric for broadband MLCCs — was a USD 1.87 billion market in 2025. Price volatility and supply tightness in key dielectric feedstocks propagate directly into high‑end MLCC pricing.
-
Manufacturer pricing: Major producers announced wide price adjustments in 2026 for premium MLCCs. Buyers should assume persistent upward price pressure in the near term and model 2026 procurement rounds accordingly.
-
Lead‑time reality: Delivery windows for high‑capacity and high‑voltage MLCCs extended materially in early 2026 — in some product classes to multiple months — changing inventory strategies and qualification timelines.
-
Capacity constraints & regulation: Equipment import controls and long factory build cycles are delaying new high‑end capacity coming online in many jurisdictions until late 2026 or beyond. That timing should influence any capex or dual‑sourcing plans executed this year.
Competitive landscape — profiles and strategic posture
-
Passive Plus Inc. (Huntington, NY, USA) — Positioned as a supplier of broadband MLCCs across compact case sizes with practical drop‑in replacements for legacy series. Their product breadth and participation in industry shows make them a viable short‑term partner for companies seeking footprint‑compatible alternatives in high‑frequency designs.
-
KYOCERA AVX (Fountain Inn, SC, USA) — A leader in ultra‑broadband RF capacitors with products optimized from kHz to well into the GHz bands. Their 2026 extension of the 550/560 series with higher‑voltage 0402 parts signals a deliberate push into optical communications and RF front‑end segments that demand both broadband performance and higher voltage ratings.
-
Dalian Dalicap Technology (Dalian, China) — A regional manufacturer emphasizing low insertion loss and broadband performance for RF/microwave applications. For companies balancing cost and performance, such regional suppliers can be tactical partners when qualification timelines are accelerated.
-
Johanson Technology (Camarillo, CA, USA) — Known for High‑Q multilayer capacitors targeting RF and microwave circuits. Their engineering focus on low ESR and low loss positions them well for broadband wireless applications where signal integrity is paramount.
-
Presidio Components, Inc. (San Diego, CA, USA) — Specializes in custom, patented broadband DC blocking and single‑layer/multilayer solutions for RF, space and military markets. Their IP and customization capabilities are attractive for defense primes and space integrators with bespoke requirements.
Recent industry moves illustrate how suppliers are sharpening product portfolios and market engagement. Notably, a 2026 product line extension by a major supplier expanded ultra‑broadband components into higher voltage small packages, and several niche vendors showcased new high‑frequency offerings at key technical conferences during 2026. These developments underscore a shifting competitive dynamic in which product differentiation, supply reliability and speed to market are decisive.
Strategic implications and recommended actions for 2026
-
Re‑assess BOMs now: Re‑run BOM sensitivity analyses using updated dielectric and component pricing assumptions. Locking long‑lead items under flexible contracts will reduce exposure to price spikes.
-
Diversify qualification pipelines: Qualify at least two alternative suppliers for critical broadband MLCC families — balancing tier‑one incumbents with regional or specialized manufacturers to manage continuity risk.
-
Prioritize design tolerance: Where possible, specify parts with broader acceptable ESR/Q windows or package alternatives early in the design cycle to enable substitution without requalification.
-
Time selective capex: Given factory build and equipment import timelines, defer heavy capex bets until there is clear visibility on capacity coming online — or partner with capacity owners via tolling or JV arrangements.
-
Opportunity scanning for M&A: Target assets that offer differentiated IP (e.g., patented DC‑blocking topologies) or vertical integration into dielectric feedstocks to capture margin and secure supply.
-
Scenario planning: Maintain scenarios that assume continued lead‑time premiuming through 2026 and a gradual easing thereafter; use the 7.5% CAGR baseline to stress‑test revenue and procurement models.
How PW Consulting helps
-
We provide tailored engagements that translate the market forecast and scenarios into procurement playbooks, design‑for‑supply recommendations and M&A screening matrices.
-
Our supplier due‑diligence service combines technical validation, commercial benchmarking and capacity assurance checks tailored to broadband MLCC technologies.
-
For teams that require immediate tactical support, we offer a 90‑day accelerated program to rework BOMs, lock negotiated contracts and retool qualification plans to align with 2026 delivery realities.
PW Consulting’s full Broadband MLCC Market report contains the detailed models, supplier scorecards, and executable toolkits referenced here. This briefing is designed as a strategic preview — it surfaces the essentials and the business implications, while the comprehensive report contains the granular segmentation, company performance models and downloadable templates you will need to act with confidence. Visit our website to access the full report and to schedule a briefing with our industry practice leaders.
In an environment of constrained capacity, raw‑material pressure and rapid product innovation, the decisions made in 2026 will define cost positions and product roadmaps into the next decade. Use the 2025 market base and our 2026–2032 forecast as the financial and operational anchor for those decisions — then deploy the tactical measures above to convert visibility into advantage.
For detailed analysis of this topic, please visit the official page: Broadband Multilayer Ceramic Capacitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Cross‑Domain E/E Architecture Market to Grow from USD 8,500 Million in 2025 to USD 24,835.21 Million by 2032 at a 16.55% CAGR
By pmarketresearch, 2026-07-13
Automotive Cross-Domain E/E Architecture Market — Strategic Insights for 2026 Decision-Makers
Executive summary
The shift from federated ECUs to zonal and server-based E/E architectures is no longer an R&D footnote — it is the defining transformation of vehicle engineering and supplier economics for the next decade. PW Consulting’s latest Automotive Cross Domain E/E Architecture Market report (base year 2025, historical 2020–2025, forecast 2026–2032) quantifies and contextualizes that transformation: the market expanded from a multi-billion-dollar base in 2020 to approximately USD 8.5 billion in 2025 and is projected to exceed USD 9.9 billion in 2026, growing at a compound annual growth rate (CAGR) of 16.55% through our forecast window to reach roughly USD 24.8 billion by 2032. Market concentration is material — the top three suppliers account for about 45.5% of industry revenue and the top five for around 62.2% — underscoring the strategic value of scale and ecosystem positioning.
Automotive Cross Domain E E Architecture Market
Why this report matters for corporate strategy in 2026
-
Architecture choice is a board-level decision: Transition paths (zonal vs. centralized server-based) will determine hardware expenditure, software platform requirements, functional safety approaches, and OTA enablement. Companies choosing suboptimal architectures risk costly rework and lost time-to-market.
Automotive Cross Domain E E Architecture Market -
Software is becoming the strategic asset: Cross-domain orchestration and middleware are the gateways to recurring revenue models. For OEMs and Tier-1s, decisions in 2026 about owning or licensing software platforms will lock in margin profiles for the 2030+ vehicle fleet.
Automotive Cross Domain E E Architecture Market -
Cybersecurity and compliance are non-negotiable: UNECE WP.29 (R155/R156) and ISO/SAE 21434 are already reshaping supplier responsibilities and type-approval workflows. Companies must embed certified CSMS processes, secure SW update mechanisms, and auditable supply-chain controls into architecture roadmaps this year.
-
Compute and semiconductor strategy is a bottleneck: Real-time cross-domain functions require aligned SoC roadmaps, heterogeneous compute stacks, and predictable supply. Locking in preferred foundry/SoC partners, or hedging through multi-sourcing agreements, will materially affect product schedules and margins.
-
Supplier and partnership models are shifting: The industry is consolidating around a set of platform providers and compute suppliers. Strategic partnerships, JV models, and minority investments in software and silicon players are becoming critical levers for OEMs and Tier-1s alike.
-
Lifecycle economics matter more than unit BOM: OTA-enabled service streams, software monetization, and update-driven safety patches alter the total cost of ownership calculus. Procurement and finance teams must incorporate lifecycle revenue and cost scenarios into 2026 sourcing decisions.
What the PW Consulting report delivers (practical contents)
-
Macro sizing and scenario-based forecasts (2026–2032) grounded in historical 2020–2025 performance and validated technology adoption curves.
-
Actionable market-entry and product positioning frameworks for OEMs, Tier-1s, semiconductor vendors, and software platform providers.
-
Competitive benchmarking and capability heatmaps for leading suppliers, including technology strengths, go-to-market models, and partner ecosystems.
-
Use-case economics and TCO models for alternative E/E architectures, supporting CAPEX/OPEX trade-off analysis and pricing strategy.
-
Regulatory impact assessment (UNECE R155/R156, ISO/SAE 21434) and compliance playbooks tailored to architecture choices.
-
Procurement playbooks and negotiation levers for securing compute, zonal controllers, and middleware while mitigating supply-chain risk.
-
Investment and M&A screening criteria for 2026: targets, valuation heuristics, and integration risk checklists.
-
Roadmaps and migration blueprints: stepwise switching strategies from federated ECUs to zonal/centralized topologies that minimize fleet fragmentation and recall risk.
Competitive landscape: what leading suppliers are doing now
The market’s current topology is shaped by a blend of traditional Tier-1 systems integrators, automotive semiconductor leaders, and new platform-oriented entrants. Key players profiled in our research include Robert Bosch GmbH, Continental AG, Aptiv PLC, ZF Friedrichshafen AG, DENSO Corporation, Valeo SE, Magna International Inc., NXP Semiconductors, and Infineon Technologies AG. Their strategic postures reveal several themes that should inform 2026 decision-making:
-
Platform consolidation by Tier-1s: Companies such as Bosch, Continental, and ZF are investing in high-performance vehicle computers and zone control strategies to consolidate cross-domain functions (powertrain, chassis, ADAS, infotainment) on fewer, more capable compute nodes. Recent product demonstrations and series introductions by Tier-1s validate rapid progress from concept to vehicle integration.
-
Software-first differentiation: Aptiv’s Smart Vehicle Architecture and LINC software platform exemplify an approach that separates I/O from compute, enabling cloud-native, modular application stacks. Software stack ownership is emerging as a major differentiator.
-
Silicon enabling the stack: NXP and Infineon are positioning domain-/zonal-optimized SoCs and power semiconductors to capture value at both hardware and enablement layers. Their roadmaps influence OEM architecture choices and validation timelines.
-
Productization to series production: Continental’s recent implementation of an HPC in a technology vehicle and the series introduction of zone control units illustrate that leading suppliers are rapidly moving from prototypes to serial-ready systems that address manufacturing, thermal, and functional-safety constraints.
-
Scale and consolidation pressures: The observed CR3 and CR5 concentration metrics indicate that the market rewards scale and platform breadth. For smaller entrants, the path to relevance is increasingly partnership-led or highly specialized vertical differentiation.
Regulation, security and operational risk
UNECE WP.29 instruments (R155 requiring certified CSMS and R156 for maintenance of secure updates) together with ISO/SAE 21434 set explicit engineering, process, and audit expectations that cannot be addressed as an afterthought. For 2026 decision-makers this means:
-
Design and procurement specifications must include verifiable cybersecurity deliverables and evidence of lifecycle security management.
-
OTA architectures must be architected with provenance, rollback, and cryptographic verification, with clear ownership between OEMs and suppliers.
-
Supply-chain due diligence needs to extend into software bill-of-materials, third-party library risk, and patch management capabilities.
Investment, M&A and partnership plays to consider in 2026
Given the growth trajectory and concentration dynamics, 2026 is a critical year for capital allocation. High-conviction plays include:
-
Investing in middleware and cross-domain software platforms to capture recurring revenue and control over feature distribution.
-
Strategic minority investments in SoC and IP suppliers to secure access to compute roadmaps and preferred pricing.
-
Partnerships with Tier-1s that can provide integration-to-production capabilities, accelerating time-to-series for new architecture concepts.
-
M&A aimed at closing capability gaps (e.g., cybersecurity tooling, software-defined vehicle orchestration, diagnostics) where integration risk is manageable and synergies are clear.
How to use this research to shape 2026 decisions
-
Use the forecasting scenarios to stress-test procurement commitments: Align multi-year supplier contracts to forecasted compute and zonal controller demand curves to avoid over- or under-investment.
-
Make software-platform decisions with long-term economics: Model licensing vs. build scenarios incorporating OTA revenue, update costs, and regulatory compliance budgets.
-
Embed cybersecurity and compliance gates in every supplier selection: Require CSMS evidence and an ISO/SAE 21434-aligned engineering roadmap as part of RFPs.
-
Prioritize partnerships that shorten validation cycles: Early integration with HPC and ZCU suppliers reduces late-stage redesign risk and protects launch windows.
Next steps and call to action
This briefing provides the strategic context and decision levers critical for 2026. For the granular segmentation, supplier scorecards, scenario models, and downloadable data visualizations that underpin the above conclusions, access the full PW Consulting Automotive Cross Domain E/E Architecture Market report and data annex. The report preserves the necessary depth for procurement negotiations, M&A diligence, and product-roadmap signoff while omitting only the proprietary micro-level revenue splits in this public summary.
About PW Consulting
PW Consulting advises OEMs, Tier-1 suppliers, semiconductor vendors, and private equity on technology strategy, commercial diligence, and go-to-market execution across the automotive software and E/E stack. If you would like a tailored briefing from our Automotive & Mobility practice based on this research, including scenario workshops and supplier bake-off facilitation for 2026 planning cycles, contact our lead analysts.
For detailed analysis of this topic, please visit the official page: Automotive Cross Domain E E Architecture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Intelligent Control Market to Reach USD 257.9 Billion by 2032, Growing at 8.52% CAGR
By pmarketresearch, 2026-07-13
Intelligent Control Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence
As enterprises plan capital allocation and transformation roadmaps for 2026, intelligent control systems sit at the intersection of automation, energy transition and digitalization. PW Consulting’s latest market research — built on a 2020–2025 historical baseline and forward-looking to 2032 — finds the global intelligent control market reached USD 145.5 Billion in 2025 and is projected to expand to roughly USD 257.9 Billion by 2032, corresponding to an 8.52% compound annual growth rate across the forecast horizon. These macro dynamics create both runway and urgency for strategic choices: vendor selection, architecture decisions, cybersecurity posture, and talent investments made in 2026 will materially influence competitiveness over the next decade.
Intelligent Control Market
Why 2026 Is a Strategic Inflection Point
-
Acceleration of value-driven automation: Organizations are moving beyond isolated PLC upgrades to invest in systems that combine predictive analytics, model predictive control (MPC), and digital twins. The result is a shift from cost-avoidance automation projects to initiatives explicitly targeting throughput, yield and energy optimization.
Intelligent Control Market -
Regulatory and safety convergence: Cybersecurity and functional safety standards (for example, the ISA/IEC 62443 cybersecurity framework and IEC/ISO functional safety families) are being applied more rigidly by regulators and by risk-conscious operators. Procurement teams must now evaluate suppliers not only on functionality, but on lifecycle compliance and secure update practices.
Intelligent Control Market -
Computational and integration pressures: Real-time decisioning, high-fidelity digital twins and edge-cloud orchestration impose new computational demands. Firms that address processing bottlenecks through targeted edge compute and hybrid architectures can convert data velocity into operational advantage.
-
Concentration and partner ecosystems: The market exhibits moderate concentration: the top three vendors account for roughly 38.5% of market revenue, while the top five approach 52.3%. This concentration creates a dual imperative — leverage established platforms for scale while preserving optionality through open architectures and best-of-breed integrations.
Market Dynamics: Drivers, Headwinds, and Structural Themes
-
Demand drivers — sustainability and cost optimization. Energy and process efficiency projects are primary catalysts; intelligent control becomes the mechanism to lock operational improvements into repeatable outcomes.
-
Technology convergence. Edge compute, AI-driven control loops (including MPC), and cloud-native analytics are converging. Successful deployments are those that rethink control stacks end-to-end rather than bolt analytical layers onto monolithic legacy DCS installations.
-
Standards and safety. Compliance with IEC 61131-style programming models, ISO/IEC functional safety norms and lifecycle cybersecurity requirements is no longer optional — it is a procurement filter and a certification pathway to project deployment in regulated sectors.
-
Implementation friction. The computational bottleneck remains real: high-fidelity simulations and real-time digital twin operations often demand hybrid edge-cloud processing, and organizations without a clear data infrastructure strategy face stalled pilots and rising costs.
Competitive Landscape — Who Matters and What Their Moves Mean
The intelligent control supplier ecosystem combines global platform incumbents, specialized systems integrators and focused technology innovators. PW Consulting’s vendor workstreams show that strategic choices should be informed by three dimensions: depth of domain control algorithms, openness and integration capability, and lifecycle security practices.
-
Siemens AG (Munich) — Siemens remains a reference for model predictive control and digital twin integration in process industries. Recent recognition of leadership in MPC underscores the company’s sustained R&D drive. For buyers, Siemens offers a high-assurance path for end-to-end digitalization, but organizations should assess modularity and exit options when embedding proprietary twin frameworks.
-
ABB Ltd (Zurich) — ABB’s intelligent automation portfolio and AI-enhanced DCS offerings are positioned toward brownfield modernization and large industrial estates. ABB is a strong candidate when projects require integrated power-and-process optimization across large assets.
-
Rockwell Automation (Milwaukee) — Rockwell’s recent ControlLogix 5590 launch signals a renewed emphasis on unified control platforms for discrete and hybrid manufacturing. Purchasing teams should evaluate the platform’s cybersecurity and integration pathways when consolidating control architectures.
-
Schneider Electric (Rueil-Malmaison) — With platforms focused on energy management and industrial control, Schneider offers compelling solutions for organizations where energy optimization is primary. Evaluate interoperability with enterprise asset management and energy marketplaces.
-
Emerson, Honeywell, Mitsubishi Electric, Yokogawa and focused specialists — These vendors make distinct trade-offs between process control depth, motion and discrete control, and domain-specific optimizations. Notably, Mitsubishi’s MX controller expansion and other recent product launches indicate a cycle of refreshes that can accelerate migration opportunities for vendors and end-users alike.
-
Specialists (e.g., Intelligent Control Systems) — Niche suppliers deliver targeted value (for example HVAC economizers) and can be acquisition or partnership targets for larger players seeking to broaden platform capabilities rapidly.
Report Practicalities — What PW Consulting’s Full Study Provides
This briefing is intentionally selective. PW Consulting’s full Intelligent Control Market report is a practitioner-first resource designed to inform 2026 decision cycles. Key deliverables include:
-
Macro market sizing and scenario-based forecasts through 2032, including sensitivity analysis under alternative adoption trajectories and regulatory regimes.
-
Vendor scorecards that compare technical capability, integration openness (APIs and protocol support), cybersecurity posture, and lifecycle services — enabling side-by-side procurement shortlists.
-
Implementation playbooks with phased migration templates, CapEx/Opex modeling, and ROI calculators tailored to discrete, process and hybrid manufacturing footprints.
-
Technology decision frameworks — edge vs. cloud choreography, digital twin fidelity guidelines, and data governance checklists reflecting computational bottleneck mitigations.
-
Legal, standards and compliance roadmaps mapping ISA/IEC 62443, IEC 61131 and functional safety requirements to procurement clauses and acceptance testing protocols.
-
Case studies and supplier negotiation playbooks that preserve optionality and minimize vendor lock-in while accelerating time-to-value.
Actionable Recommendations for 2026 Decision-Makers
-
Adopt an edge-first pilot strategy. Prioritize pilots that prove control-loop optimization at plant scale with clearly defined KPIs (throughput, yield, energy intensity). Use pilots to validate real-time processing architectures before enterprise roll-out.
-
Insist on secure-by-design contracts. Embed lifecycle cybersecurity obligations (patching windows, secure update mechanisms and asset inventories) into RFPs and SLAs in alignment with ISA/IEC 62443 expectations.
-
Design for integration and escape routes. Favor architectures with well-documented APIs and modular digital twins so that future best-of-breed components can be adopted without rip-and-replace of the entire control stack.
-
Quantify total cost of ownership beyond license fees. Include compute, networking, data engineering, and long-term model maintenance in TCO analyses. Our report’s ROI templates can convert pilot metrics into multi-year financial cases.
-
Prioritize workforce enablement. Invest in control engineers with AI and data engineering skills; plan role transitions and certify internal teams on safety and cybersecurity standards.
-
Use M&A and partnerships tactically. Given the market’s concentration dynamics, acquisitions of niche control specialists or strategic partnerships can accelerate capability assembly while reducing time-to-market.
Conclusion — Positioning for Sustainable Advantage
The intelligent control market is large and growing — the macro trajectory from a 2025 base to 2032 demonstrates meaningful expansion and sustained investment opportunity. But growth alone does not guarantee value capture. Firms that align procurement, architecture, security and talent strategies in 2026 will outperform peers and secure persistent operational advantages. PW Consulting’s full report equips decision-makers with the analytical tools, vendor comparisons and implementation playbooks required to translate market potential into measurable outcomes.
For a complete view — including granular subsegment analyses, regional and application splits, and vendor benchmarking matrices withheld from this announcement — download the full Intelligent Control Market report from PW Consulting’s research portal. The full dataset and playbooks are designed to be directly actionable for 2026 capital and transformation planning cycles.
For detailed analysis of this topic, please visit the official page: Intelligent Control Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com