

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Cross‑Domain E/E Architecture Market to Grow from USD 8,500 Million in 2025 to USD 24,835.21 Million by 2032 at a 16.55% CAGR

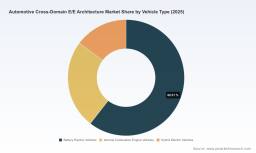
Automotive Cross-Domain E/E Architecture Market — Strategic Insights for 2026 Decision-Makers
Executive summary
The shift from federated ECUs to zonal and server-based E/E architectures is no longer an R&D footnote — it is the defining transformation of vehicle engineering and supplier economics for the next decade. PW Consulting’s latest Automotive Cross Domain E/E Architecture Market report (base year 2025, historical 2020–2025, forecast 2026–2032) quantifies and contextualizes that transformation: the market expanded from a multi-billion-dollar base in 2020 to approximately USD 8.5 billion in 2025 and is projected to exceed USD 9.9 billion in 2026, growing at a compound annual growth rate (CAGR) of 16.55% through our forecast window to reach roughly USD 24.8 billion by 2032. Market concentration is material — the top three suppliers account for about 45.5% of industry revenue and the top five for around 62.2% — underscoring the strategic value of scale and ecosystem positioning.
Automotive Cross Domain E E Architecture Market
Why this report matters for corporate strategy in 2026
-
Architecture choice is a board-level decision: Transition paths (zonal vs. centralized server-based) will determine hardware expenditure, software platform requirements, functional safety approaches, and OTA enablement. Companies choosing suboptimal architectures risk costly rework and lost time-to-market.
Automotive Cross Domain E E Architecture Market -
Software is becoming the strategic asset: Cross-domain orchestration and middleware are the gateways to recurring revenue models. For OEMs and Tier-1s, decisions in 2026 about owning or licensing software platforms will lock in margin profiles for the 2030+ vehicle fleet.
Automotive Cross Domain E E Architecture Market -
Cybersecurity and compliance are non-negotiable: UNECE WP.29 (R155/R156) and ISO/SAE 21434 are already reshaping supplier responsibilities and type-approval workflows. Companies must embed certified CSMS processes, secure SW update mechanisms, and auditable supply-chain controls into architecture roadmaps this year.
-
Compute and semiconductor strategy is a bottleneck: Real-time cross-domain functions require aligned SoC roadmaps, heterogeneous compute stacks, and predictable supply. Locking in preferred foundry/SoC partners, or hedging through multi-sourcing agreements, will materially affect product schedules and margins.
-
Supplier and partnership models are shifting: The industry is consolidating around a set of platform providers and compute suppliers. Strategic partnerships, JV models, and minority investments in software and silicon players are becoming critical levers for OEMs and Tier-1s alike.
-
Lifecycle economics matter more than unit BOM: OTA-enabled service streams, software monetization, and update-driven safety patches alter the total cost of ownership calculus. Procurement and finance teams must incorporate lifecycle revenue and cost scenarios into 2026 sourcing decisions.
What the PW Consulting report delivers (practical contents)
-
Macro sizing and scenario-based forecasts (2026–2032) grounded in historical 2020–2025 performance and validated technology adoption curves.
-
Actionable market-entry and product positioning frameworks for OEMs, Tier-1s, semiconductor vendors, and software platform providers.
-
Competitive benchmarking and capability heatmaps for leading suppliers, including technology strengths, go-to-market models, and partner ecosystems.
-
Use-case economics and TCO models for alternative E/E architectures, supporting CAPEX/OPEX trade-off analysis and pricing strategy.
-
Regulatory impact assessment (UNECE R155/R156, ISO/SAE 21434) and compliance playbooks tailored to architecture choices.
-
Procurement playbooks and negotiation levers for securing compute, zonal controllers, and middleware while mitigating supply-chain risk.
-
Investment and M&A screening criteria for 2026: targets, valuation heuristics, and integration risk checklists.
-
Roadmaps and migration blueprints: stepwise switching strategies from federated ECUs to zonal/centralized topologies that minimize fleet fragmentation and recall risk.
Competitive landscape: what leading suppliers are doing now
The market’s current topology is shaped by a blend of traditional Tier-1 systems integrators, automotive semiconductor leaders, and new platform-oriented entrants. Key players profiled in our research include Robert Bosch GmbH, Continental AG, Aptiv PLC, ZF Friedrichshafen AG, DENSO Corporation, Valeo SE, Magna International Inc., NXP Semiconductors, and Infineon Technologies AG. Their strategic postures reveal several themes that should inform 2026 decision-making:
-
Platform consolidation by Tier-1s: Companies such as Bosch, Continental, and ZF are investing in high-performance vehicle computers and zone control strategies to consolidate cross-domain functions (powertrain, chassis, ADAS, infotainment) on fewer, more capable compute nodes. Recent product demonstrations and series introductions by Tier-1s validate rapid progress from concept to vehicle integration.
-
Software-first differentiation: Aptiv’s Smart Vehicle Architecture and LINC software platform exemplify an approach that separates I/O from compute, enabling cloud-native, modular application stacks. Software stack ownership is emerging as a major differentiator.
-
Silicon enabling the stack: NXP and Infineon are positioning domain-/zonal-optimized SoCs and power semiconductors to capture value at both hardware and enablement layers. Their roadmaps influence OEM architecture choices and validation timelines.
-
Productization to series production: Continental’s recent implementation of an HPC in a technology vehicle and the series introduction of zone control units illustrate that leading suppliers are rapidly moving from prototypes to serial-ready systems that address manufacturing, thermal, and functional-safety constraints.
-
Scale and consolidation pressures: The observed CR3 and CR5 concentration metrics indicate that the market rewards scale and platform breadth. For smaller entrants, the path to relevance is increasingly partnership-led or highly specialized vertical differentiation.
Regulation, security and operational risk
UNECE WP.29 instruments (R155 requiring certified CSMS and R156 for maintenance of secure updates) together with ISO/SAE 21434 set explicit engineering, process, and audit expectations that cannot be addressed as an afterthought. For 2026 decision-makers this means:
-
Design and procurement specifications must include verifiable cybersecurity deliverables and evidence of lifecycle security management.
-
OTA architectures must be architected with provenance, rollback, and cryptographic verification, with clear ownership between OEMs and suppliers.
-
Supply-chain due diligence needs to extend into software bill-of-materials, third-party library risk, and patch management capabilities.
Investment, M&A and partnership plays to consider in 2026
Given the growth trajectory and concentration dynamics, 2026 is a critical year for capital allocation. High-conviction plays include:
-
Investing in middleware and cross-domain software platforms to capture recurring revenue and control over feature distribution.
-
Strategic minority investments in SoC and IP suppliers to secure access to compute roadmaps and preferred pricing.
-
Partnerships with Tier-1s that can provide integration-to-production capabilities, accelerating time-to-series for new architecture concepts.
-
M&A aimed at closing capability gaps (e.g., cybersecurity tooling, software-defined vehicle orchestration, diagnostics) where integration risk is manageable and synergies are clear.
How to use this research to shape 2026 decisions
-
Use the forecasting scenarios to stress-test procurement commitments: Align multi-year supplier contracts to forecasted compute and zonal controller demand curves to avoid over- or under-investment.
-
Make software-platform decisions with long-term economics: Model licensing vs. build scenarios incorporating OTA revenue, update costs, and regulatory compliance budgets.
-
Embed cybersecurity and compliance gates in every supplier selection: Require CSMS evidence and an ISO/SAE 21434-aligned engineering roadmap as part of RFPs.
-
Prioritize partnerships that shorten validation cycles: Early integration with HPC and ZCU suppliers reduces late-stage redesign risk and protects launch windows.
Next steps and call to action
This briefing provides the strategic context and decision levers critical for 2026. For the granular segmentation, supplier scorecards, scenario models, and downloadable data visualizations that underpin the above conclusions, access the full PW Consulting Automotive Cross Domain E/E Architecture Market report and data annex. The report preserves the necessary depth for procurement negotiations, M&A diligence, and product-roadmap signoff while omitting only the proprietary micro-level revenue splits in this public summary.
About PW Consulting
PW Consulting advises OEMs, Tier-1 suppliers, semiconductor vendors, and private equity on technology strategy, commercial diligence, and go-to-market execution across the automotive software and E/E stack. If you would like a tailored briefing from our Automotive & Mobility practice based on this research, including scenario workshops and supplier bake-off facilitation for 2026 planning cycles, contact our lead analysts.
For detailed analysis of this topic, please visit the official page: Automotive Cross Domain E E Architecture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com