

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: SMD Common Mode Chokes Market to Grow at 6.5% CAGR, Rising from USD 850 Million in 2025 to USD 1.32 Billion by 2032

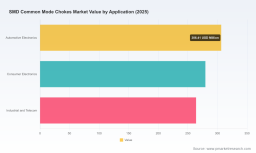
SMD Common Mode Chokes Market — Strategic Preview for 2026 Decision‑Makers
Executive summary
PW Consulting’s latest SMD Common Mode Chokes Market study (base year: 2025; historical: 2020–2025; forecast: 2026–2032) provides decision‑ready intelligence for procurement heads, product roadmap teams, and corporate strategy leaders preparing for 2026 and beyond. The market has shown steady expansion from an estimated USD 620.4 Million in 2020 to USD 850.0 Million in 2025 and is projected to continue growing through the forecast window at a compound annual growth rate (CAGR) of 6.5%, reaching an overall market size of roughly USD 1.32 Billion by 2032. This briefing highlights the strategic implications of those trends without revealing the proprietary segmentation tables included in the full report — a deliberate “trailer” to underpin executive decisions while preserving the granular intelligence available in the paid study.
Smd Common Mode Chokes Market
Why this matters for 2026
- Supply chain, design, and sourcing choices made in early 2026 will determine product cost curves and qualification schedules across the 2026–2032 growth window.
- Component manufacturers and systems OEMs face a market that is expanding but not homogeneous: product families, materials, and application requirements are differentiating winners from laggards.
- Raw material volatility and constrained lead times for advanced core materials create both operational risk and arbitrage opportunities for firms that align sourcing strategy with product roadmaps.
Market dynamics driving the next phase of growth
The SMD common mode choke market is being shaped by converging forces across end markets and supply chains. Demand drivers include ongoing electrification and higher power-density electronics in automotive and industrial systems, persistent emphasis on EMI/EMC compliance in telecom and datacom equipment, and continuous miniaturization and integration in consumer devices. These structural drivers underpin the multi‑year CAGR and the sustained expansion of the addressable market.
Smd Common Mode Chokes Market
On the supply‑side, ferrite cores and copper conductors remain the dominant cost and capacity levers. Advanced magnetic materials — including nanocrystalline cores used in higher‑performance chokes — have materially longer standard lead times (typical quoting ranges of 8–12 weeks and stretching to 16–22 weeks during constrained periods). Price volatility in ferrite and copper, influenced by broader commodities cycles and geopolitics, directly impacts BOM costs, margin planning, and contract negotiation windows for component buyers.
Smd Common Mode Chokes Market
Regulatory and test frameworks continue to codify requirements for common mode chokes in power applications; industry reference standards such as IEC/EN 60938‑2 remain pivotal for design validation and supplier qualification. The manufacturing footprint is concentrated in Asia‑Pacific hubs with strong capabilities for high-volume SMT processing and magnetic materials; this concentration is a factor in both cost leadership and geopolitical risk models.
Competitive landscape — what the leading suppliers signal
The vendor field combines global passive giants, specialized EMC players, and targeted power‑component suppliers. Key suppliers reviewed in the report include TDK Corporation, Murata Manufacturing, YAGEO Group (Pulse Electronics), Bourns, Vishay, Schaffner, Eaton, Littelfuse, Sumida, and Coilcraft. Our comparative view synthesizes product portfolios, technical differentiation, route-to-market, and go‑to‑design strategies.
- TDK Corporation (Tokyo, Japan) — TDK’s SurfIND family and similar high‑current SMD chokes (notably rated up to the mid‑30A range in recent launches) emphasize high thermal robustness and reflow compatibility for telecom and industrial power modules. Strategically, TDK reinforces the premium high‑current segment and is a go‑to for OEMs prioritizing thermal and mechanical reliability.
- Murata Manufacturing (Kyoto, Japan) — Murata’s broad SMT choke portfolio targets EMC compliance across diverse current ratings and package sizes. Murata remains competitive on miniaturization and integration for consumer and compact power supplies.
- YAGEO Group / Pulse Electronics (Taipei, Taiwan) — YAGEO’s introduction of high‑current designs with specialized core geometries signals an intent to capture DC/DC converter and power line design wins where compactness and current handling are prioritized.
- Bourns, Inc. (Riverside, USA) — With AEC‑Q200 compliant lines, Bourns is positioned for automotive design‑ins and the qualification cycles required by tier‑1 suppliers.
- Vishay, Schaffner, Eaton, Littelfuse, Sumida, Coilcraft — Each brings differentiated strengths: Vishay’s high‑current components for EMI suppression; Schaffner’s EMC specialization; Eaton’s system‑level power management alignment; Littelfuse’s protective integration; Sumida’s broad consumer/industrial range; and Coilcraft’s high‑frequency lineups. Collectively these suppliers define a competitive topology where technical depth, regulatory compliance, and geographic manufacturing footprints matter more than raw price alone.
Recent product developments underscore tactical moves by incumbents to secure design wins: TDK launched a high‑current SurfIND SMD common‑mode series in early 2025 targeting telecom and industrial power applications, and YAGEO released a high‑current ER19‑core SMD choke in mid‑2025 aimed at DC/DC converter lines. These launches indicate supplier focus on higher‑current and thermal robustness segments — areas where OEMs are increasingly designing to consolidate BOMs and improve power density.
Market structure and competitive intensity
The market exhibits moderate concentration: the top three suppliers account for a material share of industry revenue while the top five consolidate over half the market. That structure creates strategic implications for buyers and potential entrants — scale advantages in distribution, certification support, and R&D investment are meaningful, yet there remains room for focused innovators offering differentiated core materials or integrated protection features.
What the PW Consulting report provides (practical deliverables)
- Validated market sizing (2020–2025 historical; 2026–2032 forecast) with scenario modeling for downside and upside demand shocks.
- Segmentation by region, product type (e.g., wire‑wound, multilayer, thin‑film architectures), and application verticals — provided with demand drivers and discreet, actionable guidance for targeting design‑in opportunities. (Note: segmentation tables and granular shares are available in the full report.)
- Supplier benchmarking and product scorecards — performance, thermal ratings, current handling, packaging, qualification status (including automotive/AEC‑Q lines), and IP differentiators.
- Supply chain heatmaps showing lead times by core material, strategic single‑sourcing risks, and a recommended dual‑sourcing prioritization matrix.
- Raw material price sensitivity and BOM‑level cost models to support sourcing negotiations, hedging choices, and price‑pass‑through assessments.
- Regulatory and test matrix aligned to IEC/EN frameworks and common regional certification paths.
- Commercial playbooks for procurement and product teams: RFQs, qualification timelines, sample volume strategies, and contract language to secure capacity in tight market windows.
- Strategic opportunities and M&A signal map for corporate development teams — target profiles, partnership levers, and valuation considerations for bolt‑on acquisitions in magnetic materials and choke assembly capacity.
How to apply the insights in 2026
- Procurement: rebase supplier contracts with 12–24 month hedging on ferrite and copper inputs; prioritize suppliers with confirmed nanocrystalline supply for high‑performance SKUs.
- Product management: align product roadmaps to the growth pockets identified in our demand model; accelerate design‑in of high‑current or thermally enhanced chokes where applicable.
- Operations: adjust buffer stocking policies and lead‑time assumptions (plan for extended nanocrystalline lead times during constrained periods) and reconfigure safety stock by SKU criticality.
- Regulatory/compliance teams: incorporate IEC/EN validation gates early in the design cycle to avoid late rework and long qualification loops for automotive and industrial segments.
- Corporate development: use the vendor scorecards and concentration analysis to prioritize partnerships and inorganic options where market concentration and capability gaps create strategic openings.
Why PW Consulting’s study is decision‑ready
The report combines primary interviews with suppliers and OEMs, proprietary shipment and pricing indices, and bottom‑up BOM modeling to produce forecast outputs that are directly actionable for 2026 planning. Our methodology explicitly models material lead‑time variability and commodity price swings, enabling robust scenario planning rather than a single static projection. The result is a toolset that supports procurement negotiations, product qualification timelines, capital allocation decisions, and M&A screening.
Next steps and access
This release is a strategic preview intended to orient executive decision‑making for 2026. The full report contains the comprehensive segmentation tables, granular regional and application analyses, vendor scorecards, downloadable datasets, and the step‑by‑step procurement playbooks that underpin the recommendations above. PW Consulting clients and subscribers can access the complete report and editable models through our research portal or contact their account lead for a tailored briefing and scenario run‑through.
For organizations preparing sourcing strategies, product roadmaps, or M&A activity in 2026, the intelligence in the full SMD Common Mode Chokes Market report will materially shorten time‑to‑decision and reduce execution risk — particularly in an environment of material lead‑time strain and sustained demand growth.
For detailed analysis of this topic, please visit the official page: Smd Common Mode Chokes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com