

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: FC‑BGA Package Substrates Market Poised for 15% CAGR Through 2032

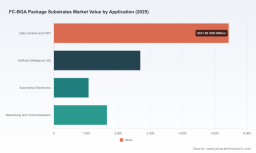
FC-BGA Package Substrates Market: Strategic Imperatives for 2026 — PW Consulting Insight
Executive summary
As semiconductor architectures pivot toward extreme I/O density and advanced compute, the flip-chip ball grid array (FC‑BGA) package substrate market is undergoing one of the most consequential growth phases in its history. PW Consulting’s new FC‑BGA Package Substrates Market report (base year 2025) finds that the global market has expanded rapidly from a modest multi‑billion USD base in 2020 to a significantly larger market by 2025, and is forecast to continue a high‑growth trajectory through 2032 at a compound annual growth rate (CAGR) of approximately 15% for the 2026–2032 horizon. Our bottom‑up market model projects total market value crossing key inflection points in 2026 and nearly tripling by 2032 under the base case — dynamics that will materially shape capital allocation, supplier strategy, and industrial policy throughout 2026 and beyond.
FC-BGA Package Substrates Market
Why this matters for 2026 corporate decision‑making
- Capacity timing is strategic: Long lead times and concentrated capacity mean that openings made in 2026 will determine supply balances and pricing power into the next decade. Our scenario analysis shows that investment decisions taken in 2026 produce outsized effects on utilization and delivery windows through 2028–2030.
- Raw materials and input risk are binding constraints: ABF build‑up films, high‑end copper foil, and CCL availability are now first‑order drivers of cost and throughput. Price shocks and extended supply lead times are already being observed and amplify the consequences of delayed capacity expansions.
- Customer segmentation is shifting: Data center, HPC, and AI workloads are the principal demand engines for advanced FC‑BGA substrates, while adjacent segments (networking, automotive, and edge compute) create complementary demand patterns that reward flexible capacity and qualification pathways.
Market trajectory and macro view
PW Consulting’s multi‑scenario forecast integrates historical trends (2020–2025) and forward modeling for 2026–2032. Industry recovery and reinvestment lifted the market from its 2020 base to a substantially larger market by 2025, with 2026 representing a critical acceleration point in absolute market value. Under our central scenario, the market grows at roughly 15% CAGR over 2026–2032, with 2026 marking the transition from the immediate post‑cycle replenishment phase into a sustained expansion driven by AI servers, GPUs, and high‑layer count requirements.
FC-BGA Package Substrates Market
Supply‑side dynamics: capacity, concentration and strategic chokepoints
- Concentration and scale matter: The supply base is moderately concentrated; the top three suppliers command a substantial share of market capacity, and the top five become dominant when capacity expansions are considered. This concentration accelerates during cyclical tightness and increases the strategic value of securing preferred supplier status.
- New lines and geographic shifts: Recent capacity announcements and launches — including major production starts and greenfield expansions in multiple jurisdictions — will reshape regional supply balances. These moves are tactical responses to both customer requirements and geopolitical incentive structures, and they materially influence lead times and pricing across 2026.
- Raw material friction points: Price increases for ABF films, extended lead times for CCLs, and a widening gap in high‑end copper foil availability create multi‑layered bottlenecks. These input constraints imply that nominal substrate capacity is not equivalent to effective throughput unless raw material contracts and inventory strategies are synchronized.
Competitive landscape: who matters and why
Leading global substrate manufacturers have differentiated along technical capability, scale, and customer proximity. Key players analyzed in the report include long‑standing Japanese manufacturers renowned for ultra‑fine microfabrication; Taiwanese producers that balance volume with rapid qualification cycles; Korean groups investing heavily to capture AI substrate demand; European specialists targeting niche high‑reliability applications; and a growing set of Chinese and regional suppliers pursuing volume and cost leadership.
FC-BGA Package Substrates Market
- Manufacturers with advanced microfabrication and ultra‑fine wiring capabilities are best positioned to serve the highest layer‑count, highest I/O density packages needed by AI and HPC customers.
- Large Taiwanese players remain pivotal for server and GPU supply chains due to scale and established customer relationships.
- Korean investments — particularly new greenfield capacity targeted at high‑growth compute centers — are rapidly changing the competitive map.
- European and select regional suppliers are capitalizing on premium, high‑reliability segments and localized demand for automotive and industrial electronics.
Notable recent industry developments include production line launches and capacity expansion programs by global incumbents, and multi‑billion‑KRW scale investments to add FC‑BGA capacity in lower‑cost manufacturing jurisdictions. These moves validate our market view that substrate capacity will be a primary battleground in 2026.
Segment and raw‑material intelligence (what we include in the report)
PW Consulting’s full report provides a practical, operational playbook designed for procurement teams, product planners, and corporate strategy groups. Key deliverables include:
- Granular demand model (bottom‑up by package type and application) with vintage demand curves for 2020–2025 and scenario projections for 2026–2032.
- Supply capacity database including age, technology node capability, planned expansions, and ramp profiles — enabling accurate lead‑time and utilization forecasts.
- Input supply assessment for ABF films, CCLs, and high‑end copper foil, including supplier concentration, lead‑time elasticity, and price shock sensitivity.
- Supplier scorecards and qualification roadmaps to support accelerated onboarding or dual‑sourcing for mission‑critical programs.
- Contract negotiation playbook — practical terms and protective clauses designed for periodic shortages, force majeure, and long lead‑time management.
- Scenario and stress tests for pricing, capacity shutdowns, tariffs, and raw‑material supply shocks, with quantified P&L impacts under multiple cases.
- Strategic M&A and J‑V playbook tailored to substrate value chain consolidation and capability acquisition opportunities.
To preserve commercial value for clients, our public summary intentionally withholds certain granular split figures and price trajectories — these are contained in the full report and the downloadable data annex.
Strategic implications and recommended actions for 2026
- Prioritize lead‑time management: Establish multi‑tiered supplier agreements with capacity reservations and clear ramp milestones. For companies dependent on high‑layer count substrates, securing allocation in 2026 is more valuable than spot‑market purchases later.
- Hedge raw‑material exposure: Negotiate long‑term procurement contracts for ABF films and premium copper foil, and evaluate strategic inventory positioning. Joint procurement or off‑take agreements with substrate makers can reduce price volatility and secure throughput.
- Invest selectively in qualification: Accelerate parallel qualification tracks with at least two qualified suppliers for each strategic product family. Passing qualification earlier in 2026 will unlock capacity priority in 2027–2028 cycles.
- Reconsider vertical integration and partnerships: Where scale and margin dynamics justify, explore partial vertical integration or exclusive co‑investment with substrate manufacturers to secure technological roadmaps and priority capacity.
- Localize with eyes open: Geography matters — incentives, tariffs, and industrial policy can materially shift landed costs. Use our scenario maps to model total landed cost under varying tariff regimes and incentive packages before siting decisions.
- Prepare for consolidation: Industry profit pools and capacity imbalances make M&A attractive. Identify targets with complementary technology (e.g., ultra‑fine wiring capability or specialized build‑up processes) to accelerate time to market.
Risk matrix: what keeps supply chain executives awake at night
- Input price spikes: Historic and recent ABF film price increases demonstrate that raw‑material inflation can outpace substrate pricing adjustments, squeezing margins.
- Lead‑time escalation: Extended lead times for CCLs and substrate production have been observed during peaks, with episodes of beyond‑30‑week delivery timelines in prior cycles.
- Geopolitical/tariff risk: Tariff regimes on advanced substrates and critical inputs are reshaping cost competitiveness and driving strategic re‑routing of supply chains.
- Capacity under‑utilization: Premature capacity additions without raw‑material assurance can create stranded assets and depressed returns.
What PW Consulting’s report enables for 2026
For executives preparing 2026 budgets and capital plans, our FC‑BGA report provides actionable intelligence to convert growth forecasts into executable supply strategies. Clients will receive the data and tools to quantify the trade‑offs between speed to market, cost, and risk exposure — enabling precision in negotiating supplier commitments, scheduling capital projects, and shaping governance for sourcing critical substrates.
Next steps and access
PW Consulting’s public brief is intentionally selective. The detailed demand and supply matrices, supplier scorecards, contract templates, and model workbooks — including our near‑term allocation model and upside/downside scenarios — are included in the full report and protected data annex. Organizations planning capacity decisions, procurement negotiations, or strategic investments in 2026 should consult the full deliverable to translate the high‑level imperatives above into executable plans.
For access to the complete FC‑BGA Package Substrates Market report, model license, and bespoke advisory engagements tailored to 2026 decision cycles, please visit PW Consulting’s report page or contact our advisory desk for a guided walkthrough of the findings and scenario tools.
For detailed analysis of this topic, please visit the official page: FC-BGA Package Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com