

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: AI in Telecommunications to Grow at 24.85% CAGR, Market Poised to Reach USD 59.19 Billion by 2032

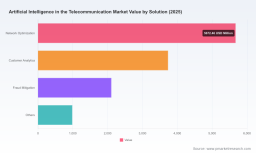
Artificial Intelligence in the Telecommunication Market: Strategic Imperatives for 2026
Executive summary
As telecommunications operators accelerate AI investments, the market is shifting from experimentation to enterprise-scale deployment. PW Consulting’s new market study — Artificial Intelligence in the Telecommunication Market (base year 2025) — maps this transition, combining a rigorous historical analysis (2020–2025) with a scenario-based forecast through 2032. The headline: the market has moved from early-adopter growth into a compounding expansion phase, with an expected compound annual growth rate of 24.85% over the forecast window. For strategy teams budgeting and prioritizing in 2026, the report provides the decision-grade intelligence needed to reconcile commercial opportunity, regulatory exposure, and operational readiness — without sacrificing pragmatic playbooks for execution.
Artificial Intelligence In The Telecommunication Market
Why 2026 is a pivot year
-
Capital allocation decisions in 2026 will determine who leads the next wave of network autonomy. Our analysis shows the market scale already reached a critical inflection point in 2025 and is forecast to continue on a steep trajectory through 2032. Executives face a narrow window to convert pilots into differentiated, scalable platforms that capture disproportionate value.
Artificial Intelligence In The Telecommunication Market -
The confluence of technology maturation (agentic AI, telco-tailored models, GPU-accelerated stacks), commercial trials, and tightening energy and regulatory constraints makes 2026 the year to shift from “proof of concept” to “proof of value.” Decisions made this year on architecture, partner choice, and data governance will materially influence cost curves and go-to-market speed over the next three to five years.
Artificial Intelligence In The Telecommunication Market -
Market concentration metrics indicate a moderately dynamic competitive landscape where a handful of platform and infrastructure players can shape industry standards — but there remains space for focused, domain-specialized entrants to capture value through vertical differentiation and operations-led propositions.
Market trajectory and what it means for investment timing
Our topline market model traces rapid expansion from the early 2020s into a large addressable market by the early 2030s. The sector’s compound annual growth rate of 24.85% reflects an accelerating cadence of deployments across network optimization, customer analytics, fraud mitigation, and adjacent enterprise offerings. Practically, this means that investments in AI-enabled network orchestration, edge inference platforms, and AI-driven customer experience platforms will see compounding returns — but timing and architecture choices matter.
Companies that front-load efforts to standardize data schemas, instrument monitoring, and create reusable model pipelines are positioned to compress time-to-value. Conversely, late movers who prioritize point solutions without operational integration risk becoming perpetual pilots with sub-scale economics.
What decision-makers will find in the report (practical contents)
-
Actionable playbooks for pilot-to-production: step-by-step deployment sequencing, acceptance criteria, and a maturity model tailored to network operators, data service providers, and managed service partners.
-
Commercial frameworks and ROI templates to quantify total cost of ownership (TCO), capital versus operational trade-offs for edge vs. centralized inference, and scenario-based NPV models that account for energy and regulatory externalities.
-
Vendor assessment toolkits and vendor scorecards: a repeatable methodology to evaluate infrastructure providers, model vendors, systems integrators, and hyperscalers across capability, integration risk, and strategic alignment.
-
Risk matrices and compliance playbooks addressing energy, siting, and data governance. These include mitigation paths for escalating data center operating costs and state-level regulatory constraints.
-
Partner ecosystem blueprints: how to structure revenue-sharing, IP ownership, and integration responsibilities between telcos, cloud providers, chipmakers, and specialist AI vendors.
-
A library of operator case studies and tested KPIs for network optimization, predictive maintenance, fraud mitigation, and customer lifetime-value uplift — intentionally aggregated at sector level to preserve strategic confidentiality while demonstrating measurable outcomes.
Competitive landscape — strategic implications
The competitive map is shaped by two sets of players: infrastructure and compute platform leaders, and incumbent telecom equipment and software suppliers who are embedding AI across network domains. Our competitive analysis synthesizes product trajectories, partnership patterns, and go-to-market moves across the leading companies.
-
NVIDIA continues to define the high-performance compute layer for telecom AI. Its GPU-accelerated stacks, telco-specific model blueprints, and growing set of live AI-RAN trials with major carriers position it as the preferred choice for operators prioritizing performance-intensive, low-latency workloads.
-
Ericsson and Nokia are competing on AI-native network strategies, focusing on integrating intelligence into RAN and orchestration layers. Their emphasis on autonomous operations and software-defined architectures is aimed at reducing operational expense through automation and energy-aware scheduling.
-
Huawei’s full-stack AI Core Network proposition is designed for operators seeking vertically integrated solutions and deep on-premises intelligence. Its product direction underscores the strategic split between open ecosystem approaches and vertically integrated offers.
-
Cloud and platform providers — Microsoft and IBM — are pushing differentiated value through managed AI services, telecom-specific data platforms, and pre-integrated tools for analytics, customer experience, and fraud detection. Their scale in cloud and enterprise services makes them natural partners for operators that want to reduce internal build cost and accelerate deployment.
-
Cisco and other networking incumbents are embedding AI capabilities into hardware and network services, offering hybrid paths that combine traditional networking investments with new AI workloads.
-
Large operators such as AT&T are increasingly operating as both buyers and orchestrators — trialing agentic AI for customer service and network operations while actively partnering in AI-RAN and edge initiatives.
Recent market signals and their strategic read
-
Industry disclosures in early 2026 — including a major vendor report citing widespread planned increases in telco AI budgets and multiple vendor-operator partnerships for live AI-RAN trials — signal that pilots are moving into network-integration phases. This validates a market dynamic where competitive differentiation will be realized through integration depth and operational excellence rather than feature lists alone.
-
Public MoUs and strategy unveilings highlight longer-term commitments to AI-powered RAN and autonomous networks through the second half of this decade. These agreements reduce technology adoption uncertainty but raise questions about vendor lock-in and multi-vendor interoperability — critical governance considerations addressed in our procurement playbooks.
-
Product launches for AI Core Network capabilities show suppliers are racing to offer end-to-end generative and agentic network functionality. Operators must assess where to place strategic bets: adopt integrated stacks for speed-to-market or assemble best-of-breed stacks to preserve flexibility.
Energy, regulation and infrastructure — the under-appreciated constraints
Energy and regulatory factors are fast becoming determinative for AI deployment economics. For example, U.S. data center electricity consumption was reported at roughly 176 TWh in 2023 and global data center demand approached 415 TWh in 2024, with forecasts indicating a sharp increase in AI-driven load. Acute regional pressures — from state-level bills regulating water, siting and energy to federal commitments that shift the cost of new generation infrastructure onto hyperscalers — materially affect deployment costs and timeline risk.
Recent market monitoring has also revealed volatile wholesale power markets in certain grids, with quarter-over-quarter price escalations tied in part to data center demand. For telcos and their partners, this translates into immediate strategic questions: Where should inference and training workloads be sited? Which workloads must remain on-premises for latency or sovereignty reasons? And how should contracts and TCO models be structured to reflect the true cost of compute and energy?
How the report informs 2026 decisions — three practical change levers
-
Strategic architecture decisions: Use our decision matrices to choose between centralized cloud, distributed edge, and hybrid topologies based on workload profiles, latency, and regulatory constraints.
-
Commercial negotiations and partner governance: Implement the vendor scorecards and contract templates to secure favorable data ownership, SLAs, and infrastructure-cost-sharing arrangements — and to de-risk vendor lock-in.
-
Energy and compliance hedging: Apply energy-impact scenarios and regulatory playbooks to anticipate siting constraints, capital expenditure timing, and to qualify incentives or mitigation strategies before committing to large-scale deployments.
Final note — what we intentionally withhold here
This briefing highlights strategic contours and practical implications; it deliberately omits detailed regional, solution, and end-user level splits that underpin our proprietary models. Those subsegment allocations, receiver-specific growth curves, and granular revenue figures are included in the full PW Consulting report and accompanying data annex — essential inputs for transaction diligence, procurement negotiation, and detailed capex planning.
Call to action
For executive teams preparing 2026 budgets and three-year roadmaps, PW Consulting’s full report provides the calibrated, operationally focused intelligence required to move from experimentation to scale. Access to the complete dataset, vendor scorecards, ROI templates, and deployment playbooks is available on our publication page. Use the report to align internal stakeholders, stress-test supplier choices, and lock in deployment sequences that capture first-mover operational advantage without incurring undue energy or regulatory risk.
For detailed analysis of this topic, please visit the official page: Artificial Intelligence In The Telecommunication Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com