

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Healthy Lifestyle
PW Consulting Reports Disposable Syringes Market to Reach $34M by 2032, Growing at 6.5% CAGR 2026-2032
By pmarketresearch, 2026-09-15
Navigating the Next Wave: Strategic Insights into the Global Disposable Syringes Market (2026–2032)
The global healthcare landscape is undergoing a structural transformation, and the disposable syringes market stands at the intersection of clinical safety, regulatory tightening, and supply chain modernization. Over the past half-decade, the sector has demonstrated steady upward momentum, with historical revenue climbing from approximately 18.0 million USD in 2020 to 23.8 million USD in 2025. As we move through the forecast window extending to 2032, market projections indicate a trajectory toward 34.0 million USD, supported by a compound annual growth rate of 6.5 percent. These figures are not merely retrospective summaries; they are strategic signposts that reveal where procurement budgets, manufacturing capacity, and regulatory compliance investments will be allocated in the coming years.
For executives, investors, and supply chain leaders, the question is no longer whether the disposable syringes sector will grow, but how to position operations, partnerships, and product portfolios to capture disproportionate value within that expansion. The latest edition of our Disposable Syringes Market research is engineered to translate macroeconomic momentum into actionable intelligence. This article previews the analytical architecture of the report, outlines the competitive and regulatory currents shaping the landscape, and explains why a disciplined, data-grounded reading of this market is essential for 2026 decision-making.
Why 2026 Is a Inflection Point for Syringe Market Strategy
The forecast period opens against a backdrop of compounding forces. Procurement cycles are lengthening, safety-engineering mandates are widening, and immunization programs are recalibrating their supply specifications. Historical data from 2020 through 2025 shows a market that has resisted volatility and continued to expand, with 2025 closing at 23.8 million USD. The early forecast years project 24.74 million USD in 2026 and 27.3 million USD in 2027, signaling that growth is not being driven by a single temporary catalyst but by durable structural demand.
Three strategic realities make 2026 particularly consequential. First, regulatory frameworks across major markets are moving from voluntary safety adoption to codified performance requirements. Second, reimbursement adjustments in key regions are reshaping downstream unit demand for self-administered and clinical injectable therapies. Third, global health procurement agencies are institutionalizing long-term agreements that reward manufacturers and distributors who can demonstrate both compliance consistency and volume reliability. Companies that treat these shifts as isolated events will miss the compounding effect; those that map them to their product lines, sourcing strategies, and market-entry plans will secure a measurable advantage.
Our research is built to help decision-makers separate signal from noise. Rather than offering a static snapshot, the report is structured to show how historical baselines, forward projections, and operational milestones interact across the forecast horizon. The goal is to give leadership teams a shared analytical language for capacity planning, pricing strategy, and competitive positioning.
Inside the Report: Analytical Architecture and Practical Utility
This study is designed as a working intelligence asset, not a passive reference document. It combines top-down market sizing with bottom-up segmentation logic, then layers in competitive profiling, regulatory mapping, and procurement-signal tracking. The result is a multi-dimensional view that can be directly plugged into strategic planning cycles.
At the macro level, the report anchors on verified historical revenue from 2020 through 2025 and extends forward through 2032. The forecast pathway is constructed to reflect realistic adoption curves, procurement timing, and regional demand diffusion. This structure allows users to test scenarios against a consistent baseline and evaluate where incremental investment is most likely to yield returns.
The segmentation framework is built to expose where value concentrates and where operational complexity rises. By volume class, the market spans a range of syringe formats, from lower-volume configurations that dominate high-frequency clinical use to larger-volume variants that serve specialized infusion and procedure settings. By end-use environment, the analysis tracks how institutional care settings, ambulatory and clinic-based networks, home healthcare channels, and other application streams each contribute to overall demand patterns. By geography, the report examines how mature markets, high-growth regions, and emerging procurement corridors differ in pricing sensitivity, regulatory pacing, and channel dynamics.
Importantly, the report does not stop at descriptive segmentation. It connects volume distributions and application footprints to strategic implications: which formats are most exposed to safety-engineering mandates, which care settings are most likely to expand procurement as reimbursement landscapes shift, and which geographic markets present the steepest compliance or distribution hurdles. This is the kind of connective analysis that helps teams prioritize product adaptation, sales-force deployment, and supplier qualification.
Beyond sizing and segmentation, the report integrates the operational pulse of the industry. It catalogues regulatory touchpoints that affect product design, labeling, and market access. It tracks reimbursement developments that influence downstream unit consumption. It monitors raw-material and procurement pricing signals that shape margin expectations. And it follows corporate activity—from trade show participation to regulatory clearances and tender announcements—that indicates where competitors are investing attention and capacity.
For each component, the report emphasizes practical application. Procurement teams can use the segmentation logic to validate sourcing mixes. Commercial leaders can use the competitive profiles to benchmark positioning and identify white space. Regulatory and quality functions can use the compliance mapping to anticipate documentation, testing, and certification requirements. Executive teams can use the forecast structure to align long-range planning with realistic growth pacing.
Competitive Landscape: Incumbents, Specialists, and Shifting Battle Lines
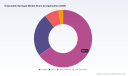
Market structure matters as much as market size. The disposable syringes sector is characterized by a concentrated core of large, globally integrated manufacturers alongside a broad tier of regional specialists and safety-focused innovators. Concentration metrics indicate that the top three players account for roughly 45 percent of market revenue, while the top five extend that share to about 65 percent. This hierarchy shapes pricing leverage, procurement relationships, and the speed at which new safety or design standards can be absorbed across the supply base.
At the center of the landscape are established medical technology and device manufacturers with broad hospital and clinic reach. Becton, Dickinson and Company stands as one of the largest providers of disposable syringes across conventional, safety, and auto-disable formats, serving immunization programs, acute care, and routine clinical use. Its scale and distribution footprint make it a reference point for compliance standardization and volume reliability. Terumo Corporation, based in Tokyo, is recognized as a pioneer and major producer of disposable syringes and needles with an emphasis on precision, clinical safety, and GMP-compliant sterile production. Nipro Corporation contributes a parallel strength in volume-based manufacturing for global healthcare supply chains, reinforcing the importance of scale, consistency, and export readiness.
European manufacturers add distinct engineering and safety-engineering perspectives. B. Braun SE produces disposable syringes and related medical devices with a clear focus on safety-engineered and infusion-compatible models, aligning product development with the needs of integrated care settings. CODAN Medizinische Geräte GmbH supplies safety and standard models designed to comply with international standards, while Gerresheimer AG brings material expertise through glass and polymer disposable syringes used in pharmaceutical and clinical applications. These firms illustrate how material science, device compatibility, and compliance assurance can become differentiators in markets where specification scrutiny is rising.
The specialist tier is equally important to watch. Retractable Technologies, Inc. focuses on retractable and safety disposable syringes designed to reduce needlestick injury risk, a positioning that directly intersects with occupational safety priorities and procurement criteria. ICU Medical, Inc. supplies sterile, single-use disposable syringes and infusion systems for clinical use, and Exelint International, Co. offers EXEL-branded disposable syringes with secure-touch safety needles, reinforcing the commercialization of ergonomic and safety-oriented design features. On the international supply side, Star Syringe Limited emphasizes quality and sterility in disposable and safety syringes, while Hindustan Syringes and Medical Devices Limited produces safety and auto-disable variants for both domestic and export markets. In Asia, KMED Kangyi Medical and Liaoning KANGYI Medical Equipment Co., Ltd. supply disposable syringes, infusion sets, and related medical disposables certified to MDR and ISO standards, reflecting the growing role of compliant Asian manufacturers in international procurement channels.
Recent corporate activity underscores how dynamic this landscape has become. In late 2025, Exelint International, Co. received FDA 510(k) clearance for EXEL Disposable Syringes with Needles, including models with Secure Touch safety needles, signaling continued U.S. market entry and product expansion. Trade channels have also been active: Liaoning KANGYI Medical Equipment Co., Ltd. presented disposable syringes and related medical devices at MEDICA 2025 in Düsseldorf, and Healthtopmed exhibited disposable syringes, insulin syringes, and auto-destroy syringes at Arab Health 2025. Looking ahead, YIZUMI is scheduled to exhibit at the 93rd CMEF 2026 in Shanghai, focusing on medical injection molding and production solutions relevant to disposable syringes. These events are not peripheral; they are indicators of where product roadmaps, manufacturing partnerships, and distribution alliances are being negotiated.
Worldwide Disposable Medical Syringe Market
For buyers and competitors alike, the strategic takeaway is that market leadership is increasingly defined by more than unit volume. It is defined by the ability to align product portfolios with safety mandates, maintain compliance documentation across jurisdictions, and demonstrate consistent supply performance in both institutional and programmatic procurement environments. The report's competitive profiling is designed to help users read these signals systematically rather than anecdotally.
Regulatory, Procurement, and Demand Dynamics Reshaping the Field
The disposable syringes market does not expand in a vacuum. It is being re-shaped by regulation, reimbursement, and programmatic procurement expectations that together influence product specification, pricing, and channel strategy. Understanding these dynamics is essential for anyone planning capacity, entering new markets, or renegotiating supplier relationships in 2026.
On the regulatory side, safety and performance requirements are becoming more explicit. The EU Medical Device Regulation classifies safety syringes as Class IIa devices and requires compliance with ISO 23908 performance testing, reinforcing a framework in which safety-engineered designs must meet documented performance benchmarks rather than general expectations. In parallel, WHO's Global Injection Safety Initiative mandates the exclusive use of auto-disable and safety syringes in immunization programs worldwide, elevating compliance from a procurement preference to a program-level prerequisite. UNICEF prequalification further tightens the specification environment by requiring auto-disable syringes to comply with ISO 7886-3 for fixed-dose immunization use. These standards do not merely restrict the market; they define the qualification threshold for participation in high-volume public health supply chains.
Reimbursement developments are adding another layer of demand influence. In the United States, CMS broadened reimbursement in 2025 for self-injectable anticoagulants, adding a meaningful number of prefilled units to annual demand. This kind of policy shift changes the downstream consumption environment for syringe formats used in self-administration and ambulatory care, and it illustrates how payer decisions can ripple into device demand with limited lead time. For manufacturers and distributors, the implication is clear: reimbursement calendars and clinical practice changes should be monitored as closely as production metrics.
Procurement behavior is also evolving. UNICEF's issuance of RFP-DAN-2025-503825 for long-term agreements to supply safe injection equipment, including disposable syringes and auto-disable syringes for 2026–2027 procurement, signals a preference for multi-year supply commitments that reward reliability, scale, and compliance consistency. At the same time, pricing dynamics remain a practical concern. UNICEF paid approximately 0.08 to 0.12 USD per auto-disable syringe unit in 2025, compared with about 0.05 USD for conventional designs. This gap highlights a persistent tension: safety and auto-disable features are increasingly non-negotiable in many programs, yet they carry higher unit costs and therefore place pressure on sourcing strategies, subsidy structures, and volume planning.
Disposable Syringes Market
Together, these dynamics create a market environment in which compliance, specification alignment, and procurement readiness are competitive assets. A company that can demonstrate ISO-aligned performance, maintain ready access to safe and auto-disable formats, and respond credibly to multi-year program tenders is better positioned to secure demand than one that competes on price alone. The report's dynamics section is built to map these forces to practical consequences for product design, market access, and commercial planning.
What This Means for 2026 Decision-Making
The strategic value of this research lies in its ability to convert market momentum into planning clarity. The forecast pathway to 34.0 million USD by 2032 implies that growth will continue, but it also implies that the composition of that growth will matter as much as the total. Volumes will shift across syringe formats. Demand will migrate across care settings. Regional procurement patterns will diverge as mature markets stabilize and emerging corridors scale. Regulatory expectations will continue to raise the bar for product qualification.
For leadership teams, the report is intended to support several concrete decisions. It can help determine which volume classes and application segments deserve closer commercial focus, which regulatory requirements must be built into product roadmaps, and which geographic markets require additional compliance preparation or distribution investment. It can help procurement leaders benchmark sourcing assumptions against broader market pricing and program-tender behavior. It can help competitive strategists understand where concentration gives incumbents leverage and where specialist innovation may open narrower but higher-value niches.
Most importantly, the report is built to be used. The segmentation logic supports scenario testing. The competitive profiles support benchmarking and partnership evaluation. The regulatory and procurement mapping supports risk prioritization. The forecast structure supports capacity and revenue planning that is grounded in realistic pacing rather than optimistic extrapolation.
Access the Full Intelligence Architecture
This preview is intended to demonstrate the depth and structure of the study, not to exhaust it. The complete Disposable Syringes Market research provides the detailed segmentation frameworks, full competitive profiling, regulatory timelines, procurement-signal tracking, and forecast calculations that decision-makers need to move from awareness to action. If your 2026 planning involves product positioning, sourcing strategy, market entry, or competitive response in the disposable syringes sector, the full report offers the evidence base required to make those choices with confidence.
We invite you to explore the complete research on our platform, where the full segmentation breakdowns, company profiles, developments timeline, and market dynamics analysis are available in their entirety. The macro trajectory is clear; the strategic opportunity lies in understanding exactly where to act within it.
For detailed analysis of this topic, please visit the official page: Disposable Syringes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Foot Care Market to Hit $5.48 Billion by 2032, Growing at 6.84% CAGR
By pmarketresearch, 2026-09-15
Navigating the Next Wave: Strategic Intelligence in the Foot Care Products Market (2026–2032)
The global foot care products market stands at a critical inflection point. As consumer awareness of podiatric health rises and regulatory frameworks adapt to emerging clinical needs, the sector is no longer a niche retail category—it is a strategically vital landscape where personal wellness, sports performance, and clinical reimbursement intersect. PW Consulting's latest comprehensive market study maps this transformation across a six-year forecast horizon, equipping category managers, supply chain leaders, and strategic planners with the actionable intelligence required to make confident decisions in a rapidly evolving environment.
A Market Built on Sustained Structural Growth
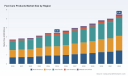
Drawing on a rigorous historical analysis spanning 2020 through 2025, our research establishes a clear baseline of resilience. The global foot care products market has consistently expanded from approximately $2.7 billion in 2020 to an estimated $3.45 billion in 2025, reflecting both post-pandemic consumer re-engagement and a broadening appreciation for preventive foot health. More importantly, our forward-looking model projects a compound annual growth rate of 6.84% through 2032, with the overall market trajectory positioning it to surpass the $5 billion threshold before the decade concludes.
These figures are not merely retrospective markers. They represent a foundational reality: demand is compounding at a pace that outstrips many adjacent personal care segments. For organizations planning capacity expansions, brand portfolio allocations, or distribution network upgrades, understanding the velocity of this growth is essential. Yet the headline trajectory only tells part of the story. Our full study dissects the underlying drivers—demographic shifts, therapeutic innovation, retail channel migration, and policy-enabled clinical access—that will determine which market participants capture disproportionate share during this expansion phase.
Beyond the Headline: Where the Real Strategic Decisions Live
Scaling revenue requires more than confidence in a positive CAGR. It demands precision in segmentation, go-to-market architecture, and competitive positioning. Our report delivers a structured, decision-oriented breakdown across product types and end-use categories, enabling leadership teams to identify the highest-leverage opportunities within their specific operational context.
The product landscape encompasses established staples such as topical creams and lotions, alongside specialized interventional formats including shoe pads, moisturizing socks, and a growing array of adjacent solutions. Each format carries distinct cost structures, shelf-life considerations, consumer adoption curves, and clinical utility profiles. Likewise, the end-use segmentation reveals how personal and home-care demand compares against the performance-oriented sports and athletes segment, and how the medical and therapeutic category continues to gain structural support from evolving reimbursement pathways. Our analysis isolates the growth mechanics within each of these buckets without relying on superficial slice-and-dice reporting. Instead, we translate segmentation into strategic signal: where volume is concentrating, where margins are being defended, and where new entrants or incumbents are most likely to contest share.
Foot Care Products Market
For executives who need to prioritize capital allocation, the segmentation framework in our study serves as a roadmap for portfolio rebalancing. It identifies which subcategories are consolidating around established consumer habits, which are being reshaped by active-lifestyle purchasing behavior, and which are moving in lockstep with clinical guideline updates. Full segment-level intelligence—including unit economics proxies, demand elasticity observations, and regional appetite indicators—is provided in the complete report, enabling teams to move from high-level trend awareness to specific, defensible action plans.
Competitive Architecture: How the Market Is Being Shaped
The foot care products market remains notably fragmented at the top, with our data indicating that the three largest players account for roughly 22% of aggregate market revenue and the top five for approximately 26%. This concentration profile has important strategic implications. It suggests that no single enterprise currently dictates pricing, channel access, or innovation cadence across the entire category. Instead, competitive advantage is being won through specialization, brand trust, clinical credibility, and regionally attuned distribution strategies.
Our report profiles a representative set of organizations that illustrate how different strategic postures are playing out in the current environment. Aetrex Worldwide, Inc., based in Princeton, New Jersey, continues to demonstrate the value of aligning foot care products with footwear-adjacent engineering and consumer comfort standards, an approach that resonates strongly with performance-oriented and personal-use buyers. PediFix Inc., operating out of Hauppauge, New York, reflects a more therapeutic, solution-oriented positioning that emphasizes accessible over-the-counter interventions for common foot conditions. Alva-Amco Pharmacal Companies, Inc., headquartered in Sterling, Virginia, brings a pharmacological heritage to the category, reinforcing the bridge between everyday wellness products and clinically informed formulation expectations.
Anti Cellulite Care Products Market
Blistex Inc., based in Oak Brook, Illinois, continues to leverage its broader dermatological and personal care reputation to extend consumer trust into foot-specific care formats. Footlogix, headquartered in Sammamish, Washington, exemplifies the specialized, science-forward brand play that has gained traction among consumers and professionals seeking targeted efficacy claims. Further broadening the geographic and clinical lens, Diabetik Foot Care India Private Limited, based in Chennai, Tamil Nadu, illustrates how localized clinical need—particularly around at-risk foot management—is inspiring product strategies that align with both consumer education and medical guidance.
Each of these companies occupies a distinct strategic position within the broader market. Our study examines how their product focus, brand narratives, and channel strategies interact with the structural forces shaping demand. The goal is not to rank competitors, but to illuminate the playbooks that are currently generating momentum, so that your organization can identify analogous opportunities or anticipate competitive counter-moves.
Policy, Reimbursement, and the Clinicalization of Foot Care
One of the most consequential developments in the current market cycle is the gradual clinicalization of categories that were once dominated by general consumer retail. Regulatory and reimbursement evolutions are reshaping how foot care products are positioned, purchased, and valued by end users and care providers alike.
Recent regulatory activity underscores this shift. In May 2026, FDA granted supplement approval for NDA 209089/S-010 for OTC foot care products, a development with direct implications for labeling, claims substantiation, and competitive parity among manufacturers seeking to align their portfolios with recognized pathways. Around the same time, in April 2026, the American Podiatric Medical Association and the New York State Podiatric Medical Association engaged with NGS to address LCA changes allowing reimbursement for at-risk foot care by certified nurses. This policy dialogue reflects a broader movement toward formalizing which clinical professionals may deliver reimbursed foot care services, and under what certification and supervision conditions.
The reimbursement environment has been further clarified by CMS guidance. Updated billing and coding information indicates that the revised LCA for Medicare Part B allows a Registered Nurse holding a CFCN® credential to perform at-risk foot care under direct physician supervision, with proof of certification required upon request. Complementary recognition from WOCNCB confirms that the Foot Care Certification credential is acknowledged for reimbursement of eligible foot care services. Together, these developments create a more navigable pathway for clinical engagement in foot care, which in turn expands the addressable demand for products that complement nurse-administered or physician-supervised care.
On the device and product-handling side, infection-control expectations continue to sharpen. Industry guidance emphasizes that all foot care devices must be intended for human use and reprocessed according to Spaulding classification principles, with single-use emery bands and manufacturer-specified steam sterilization cycles applied where relevant. For manufacturers, formulators, and private-label partners, these standards influence packaging design, product claims, and operational compliance. Simultaneously, the APMA Seal of Acceptance program continues to evaluate footwear, insoles, and equipment for normal foot function and quality standards, reinforcing a trust signal that many consumers and procurement professionals increasingly treat as a baseline consideration.
These dynamics are not peripheral. They affect product architecture, claims strategy, retailer relationships, clinical distribution partnerships, and the long-term positioning of brands that aim to compete across both retail and care-adjacent channels. Our report integrates these developments into a coherent market dynamics framework, helping organizations anticipate where compliance, credibility, and clinical alignment will become decisive competitive factors.
What Decision-Makers Will Find Inside the Full Report
This market study is designed for teams that need to move from macro awareness to execution-ready intelligence. The report is structured to support a range of strategic tasks, including:
- Category and portfolio planning: A detailed segmentation lens that helps identify where to accelerate, where to defend, and where to experiment based on growth momentum and competitive saturation.
- Competitive benchmarking: Company-specific profiles that translate product focus and market behavior into actionable positioning insights, enabling more precise competitive monitoring and response planning.
- Regulatory and reimbursement readiness: An integrated view of recent approvals, policy discussions, certification recognition, and infection-control expectations that shape product claims, clinical adoption, and procurement confidence.
- Distribution and channel strategy: Analysis of how consumer purchasing pathways, retail formats, and care-adjacent access points are influencing product placement, basket economics, and brand visibility.
- Risk and compliance awareness: Practical context on sterilization, reprocessing expectations, and credentialing requirements that matter to manufacturers, brand owners, and clinical-facing partners.
By connecting top-line market sizing with the operational realities of product development, brand positioning, and channel execution, the report serves as a reference point for both near-term planning and longer-term portfolio strategy. It is especially relevant for organizations evaluating expansion into adjacent subcategories, assessing partnerships with clinical or retail intermediaries, or preparing for a market environment in which reimbursement and certification signals increasingly influence purchasing decisions.
Why This Study Matters for 2026 Strategy
The period ahead will reward organizations that can read the market at multiple levels simultaneously. At the macro level, sustained growth through 2032 creates the conditions for profitable expansion. At the segment level, the dispersion of demand across product formats and end-use categories requires disciplined prioritization rather than undifferentiated scaling. At the competitive level, a fragmented concentration profile means that differentiation, credibility, and channel precision can outweigh sheer scale. And at the policy level, regulatory approvals and reimbursement developments are broadening the clinical relevance of foot care products, creating new vectors for demand while also raising the bar for compliance and claims integrity.
In that context, the strategic question is not simply whether the market is growing, but where your organization can most effectively participate in that growth. Our study is built to help leadership teams answer that question with greater clarity and less guesswork. It combines historical rigor, forward-looking modeling, competitive profiling, and policy-aware market dynamics into a single decision-support framework.
To access the full segmentation intelligence, complete company profiles, and the entire forecast series underpinning this analysis, we invite you to explore the complete PW Consulting Foot Care Products Market research. The detailed dataset and executive insights are available through our report portal, where you can retrieve the full market model, download the segmentation breakdown, and align the findings directly with your internal planning cycles.
For detailed analysis of this topic, please visit the official page: Foot Care Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: N95 Mask Market Hits $2B in 2025, 8.7% CAGR to $3.49B by 2032
By pmarketresearch, 2026-09-15
Navigating the N95 Grade Medical Protective Masks Market: A Strategic Overview for 2026 and Beyond
The global landscape for respiratory protection has undergone a fundamental transformation over the past half-decade. What was once a commoditized procurement category has evolved into a critically regulated, clinically essential infrastructure component. As healthcare institutions, industrial operators, and supply chain strategists recalibrate their risk mitigation frameworks, the N95 Grade Medical Protective Masks Market stands at the intersection of public health preparedness, regulatory stringency, and manufacturing capability. This analysis draws from our latest comprehensive market research to outline the structural forces shaping the industry from 2026 through 2032. Readers seeking actionable intelligence, granular segmentation breakdowns, and proprietary forecasting models are directed to the full report, which serves as a foundational decision-support tool for procurement leaders, investor relations teams, and competitive strategists.
Market Trajectory and Structural Drivers
The market has demonstrated sustained expansion since the early 2020s, with historical performance indicating a consistent upward trajectory driven by heightened infection control protocols, occupational safety mandates, and institutional procurement standardization. From a baseline of approximately 1.38 billion USD in 2020, the sector has progressed through successive annual increments, reaching the 2.00 billion USD threshold by 2025. Forward-looking projections place the market value at 2.14 billion USD in 2026, with acceleration expected through the latter half of the forecast window. By 2032, estimated market revenue approaches 3.49 billion USD, reflecting a compound annual growth rate of 8.7 percent across the 2025–2032 forecasting horizon.
Several interdependent dynamics underpin this trajectory. First, healthcare administrators have institutionalized respiratory protection as a baseline operational requirement rather than an episodic procurement response. Second, regulatory frameworks governing filtration certification, fluid resistance, and single-use compliance have raised the technical bar for market entry, effectively concentrating supply among manufacturers capable of consistent quality validation. Third, supply chain resilience initiatives have prompted end-users to diversify sourcing strategies, favoring vendors with documented certification continuity and transparent material sourcing. Together, these forces have transitioned the market from volume-driven surplus cycles to value-driven, compliance-aligned purchasing behavior.
Regulatory Frameworks and Technical Benchmarks
The commercial viability of N95-grade respiratory protection is inextricably linked to certification rigor and regulatory compliance. All FDA-cleared N95 respirators are designated as single-use disposable devices. Reprocessing or reuse pathways require explicit FDA enforcement discretion or emergency use authorization, a constraint that shapes inventory planning, waste management protocols, and lifecycle costing across healthcare networks. Concurrently, NIOSH-certified filtering facepiece respirators must display a TC-84-A approval number and demonstrate a minimum 95 percent filtration efficiency against 0.3-micron particles, a technical threshold that serves as the de facto baseline for procurement qualification in clinical environments.
For surgical N95 respirators deployed in medical protective applications, the technical requirements extend further. These devices must additionally satisfy ASTM F2100 Level 2 or Level 3 fluid resistance and particulate filtration standards. The convergence of these standards creates a bifurcated product architecture in which general particulate protection and fluid-resistant medical-grade models occupy distinct procurement categories. Electrostatic filter media technology has emerged as a critical performance differentiator within this architecture, reducing breathing resistance by up to 50 percent while preserving medical-grade fluid resistance at 160 mm Hg. This engineering balance directly influences clinician adoption rates, wearer compliance, and extended-shift usability, factors that procurement committees increasingly weigh during vendor evaluations.
Reimbursement and administrative dynamics further complicate purchasing decisions. CPT codes for N95 respirator utilization in hospital settings are anchored to infection control procedures that require documented medical necessity for airborne pathogen protection. This coding dependency ties product selection to clinical documentation workflows, meaning that procurement choices must align not only with technical specifications but also with hospital coding compliance and cost-recovery pathways. The intersection of regulatory labeling, certification numbering, material performance, and reimbursement justification forms a complex decision matrix that many organizations are only beginning to navigate systematically.
Competitive Landscape and Strategic Positioning
The market exhibits moderate concentration, with the top three manufacturers accounting for 47.8 percent of total revenue and the top five collectively capturing 58.2 percent. This concentration reflects the barriers to entry posed by certification pipelines, compliance documentation, and established institutional relationships. Several organizations have differentiated their positioning through product-line specialization, supply chain agility, and regulatory continuity.
3M Company, headquartered in Saint Paul, Minnesota, remains a defining reference point in the healthcare respirator segment. The company manufactures NIOSH-approved N95 and surgical N95 filtering facepiece respirators, including fluid-resistant medical-grade models engineered for clinical deployment. Louis M. Gerson Company, Inc., operating from Middleboro, Massachusetts, produces FDA-cleared and NIOSH-approved N95 particulate respirators that emphasize low breathing resistance and fluid resistance tailored to medical applications. Makrite Industries, Inc., with headquarters in Taiwan and global operations that include United States supply channels, supplies NIOSH-approved and FDA-cleared surgical N95 respirators for healthcare settings, offering private-label medical-grade options that appeal to institutional branding and procurement flexibility.
DemeTECH Corporation, based in the United States, manufactures NIOSH-approved N95 and surgical N95 respirators for medical use, including FDA-cleared fluid-resistant models. Moldex-Metric, Inc. offers NIOSH-approved N95 filtering facepiece respirators specifically oriented toward healthcare and medical protective applications. Shawmut Corporation provides NIOSH-approved N95 respirators under its Protex series, explicitly designed for medical and healthcare protective needs. Medtecs Corporation, also United States-based, develops and supplies N95 masks certified for medical protective use within healthcare environments. These organizations collectively represent a competitive field shaped by differing manufacturing footprints, certification pathways, and product-line emphases.
Strategic differentiation among these players rarely hinges on price alone. Instead, it revolves around certification continuity, production capacity stability, material sourcing transparency, private-label capability, and responsiveness to institutional compliance requirements. The recent CDC-NIOSH update in May 2026, which refreshed the Certified Equipment List as of June 1, 2026, confirmed ongoing active production and certification for medical-grade respirators, reinforcing the regulatory permanence of the category. For procurement teams and competitive analysts, tracking certification list updates, approval number visibility, and documented fluid-resistance compliance has become a routine but essential element of supplier qualification.
Segmentation Logic and Demand Architecture
The market is structured around three primary segmentation dimensions: geography, product type, and application context. Each dimension shapes procurement behavior, inventory strategy, and risk allocation. Regional demand patterns reflect varying institutional procurement maturity, regulatory adoption speeds, and healthcare infrastructure density. Product type segmentation distinguishes respirators equipped with exhalation valves from those without, a distinction that carries clinical, operational, and infection-control implications. Application segmentation separates demand originating from hospital and clinic environments, industrial settings, and individual end-users, each with different purchasing cycles, compliance drivers, and volume characteristics.
Hospital and clinic procurement typically operates through structured vendor qualification processes, bulk contracting, and compliance documentation requirements. Industrial demand is influenced by occupational safety programs, particulate exposure assessments, and worker protection mandates. Individual market segments often respond to public health messaging, retail availability, and consumer-grade certification awareness. The interplay among these segments creates a multi-channel demand environment in which pricing, certification emphasis, and distribution strategy must be calibrated separately rather than treated as a uniform market proposition.
Material cost dynamics further complicate segmentation strategy. The adoption of electrostatic filter media has enabled manufacturers to improve wearer comfort without sacrificing fluid resistance, but this engineering advantage also introduces sensitivity to raw material availability, media formulation consistency, and production yield. Organizations evaluating long-term supply partnerships must therefore consider not only unit pricing but also media quality control, tolerance consistency, and the ability to maintain filtration performance across production batches. In a market where clinical usability directly influences adoption and compliance, material performance is a strategic variable rather than a purely technical footnote.
Operational Implications for 2026 Decision-Makers
For executives, procurement leaders, and strategy teams operating in 2026, the N95 Grade Medical Protective Masks Market presents several actionable considerations. The first is compliance alignment. As regulatory expectations around certification labeling, single-use classification, and fluid-resistance standards remain firmly entrenched, organizations must embed verification checkpoints into supplier onboarding and periodic re-qualification. The presence of a valid TC-84-A approval number, documented NIOSH approval status, and FDA clearance where applicable should form the minimum baseline for any contract inclusion.
The second consideration is inventory architecture. Given the single-use disposable classification and the reimbursement implications tied to documented medical necessity, organizations benefit from treating respirator inventory as a regulated clinical supply rather than a general safety stock item. Forecasting should incorporate infection control calendars, seasonal respiratory illness patterns, institutional staffing cycles, and potential surge scenarios. Over-reliance on reactive purchasing increases exposure to price volatility and compliance gaps; proactive multi-quarter planning reduces both.
The third consideration is supplier diversification with qualification rigor. Market concentration indicates that a limited number of manufacturers command a substantial share of revenue, but institutional buyers still benefit from maintaining qualified alternatives across different manufacturing footprints and product configurations. Diversification should not dilute compliance standards. Instead, it should expand the pool of pre-qualified vendors capable of meeting certification, fluid-resistance, and documentation requirements. Private-label options, where available, can provide additional flexibility for institutions seeking branded supply continuity without compromising regulatory alignment.
A fourth consideration involves reimbursement and coding awareness. Since CPT code utilization for N95 respirators in hospital settings depends on documented medical necessity for airborne pathogen protection, procurement decisions should be coordinated with clinical documentation teams and revenue cycle stakeholders. Alignment across supply chain, infection control, and administrative coding functions helps ensure that purchased products support both clinical protection and institutional cost-recovery structures.
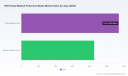
Medical Protective Masks Market
Finally, organizations should monitor certification list updates, material performance trends, and regulatory guidance revisions as ongoing intelligence inputs. The May 2026 CDC-NIOSH equipment list refresh underscores that certification status is dynamic and must be tracked continuously. Companies that institutionalize this monitoring process are better positioned to anticipate supply continuity, validate replacement products, and maintain uninterrupted compliance across procurement cycles.
Conclusion and Next Steps for Strategic Intelligence
The N95 Grade Medical Protective Masks Market is no longer defined by episodic demand shocks alone. It is now shaped by enduring regulatory expectations, engineering-driven product differentiation, concentration-oriented competitive dynamics, and procurement workflows that fuse clinical protection with administrative compliance. The 8.7 percent compound annual growth trajectory projected through 2032, alongside the estimated expansion from approximately 2.14 billion USD in 2026 to 3.49 billion USD by the close of the forecast period, signals a market that will continue to reward organizations capable of aligning technical qualification, supply resilience, and compliance discipline.
N95 Grade Medical Protective Masks Market
This overview has outlined the structural contours, regulatory benchmarks, competitive positioning, and operational considerations that define the market environment for 2026 decision-makers. Full segmentation data, regional demand distribution, application-level revenue splits, product-type breakdowns, detailed company profiles, competitive benchmarking matrices, and proprietary scenario modeling are available in the complete market research publication. Readers seeking comprehensive datasets and actionable strategic frameworks are encouraged to access the full report to support procurement planning, competitive positioning, investment evaluation, and long-range supply strategy development.
For detailed analysis of this topic, please visit the official page: N95 Grade Medical Protective Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects American Ginseng Market to Hit $383M by 2032 with 5.2% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence for the American Ginseng Market 2026-2032: A PW Consulting Executive Brief
As the global wellness economy matures and consumer preference shifts decisively toward botanical, science-backed functional ingredients, American Ginseng has emerged as a cornerstone commodity with distinct value chains, regulatory nuances, and geographic supply advantages. PW Consulting is pleased to introduce our newly released American Ginseng Market Research, a comprehensive analytical instrument designed specifically to equip executive teams, product strategists, and commercial leaders with the actionable intelligence required to navigate a market poised for sustained, measured expansion through the end of the decade.
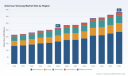
American Ginseng Market
This executive brief serves as a strategic preview of the full study. It outlines the structural forces shaping the category, introduces the methodological backbone of our research, and demonstrates precisely how the complete report can be operationalized to support capital allocation, product portfolio design, supply chain optimization, and market-entry decision-making in 2026 and beyond. Just as a well-crafted trailer establishes tone, credibility, and narrative stakes without surrendering the full plot, this document is engineered to establish analytical rigor and strategic relevance while reserving the granular, segment-level forecasts, company scorecards, and scenario matrices for the full published report.
The Strategic Imperative: Why 2026 Decisions Require Deeper Market Architecture
The American Ginseng category is no longer a niche botanical play. It has evolved into a multi-feedstock, multi-format, multi-region commercial ecosystem where historical growth informs but does not dictate future performance. Our analysis covers a historical window from 2020 through the base year of 2025, establishing a clarified trajectory of adoption, pricing normalization, and channel maturation. Building on that foundation, the forecast period from 2026 through 2032 projects a consistent compound annual growth rate of 5.2 percent, measured in USD millions. That trajectory signals durable, compounding demand rather than a speculative spike, and it carries significant implications for how organizations plan capacity, negotiate long-term sourcing agreements, and prioritize innovation investments.
For decision-makers, the strategic question is no longer whether American Ginseng represents a growth opportunity. The question is which structural drivers will translate into margin expansion, which regulatory and logistics realities will discipline inventory planning, and which competitive positions will prove defensible as the market broadens across product formats, application verticals, and export corridors. The full report dissects these dynamics with methodological discipline. What follows is a curated view of the analytical architecture and commercial context that make the study a decision-grade asset for 2026 planning cycles.
Macro Trajectory and the Discipline of Forecast Confidence
Reliable strategy rests on reliable baselines. The historical record we examine from 2020 to 2025 reflects a market that has steadily recalibrated around verified cultivation, quality authentication, and expanding distribution pathways. From that base, the mid-2020s and early-2030s forecast arc reflects sustained momentum with an anticipated average annual expansion of 5.2 percent. Importantly, this is not a single-point projection presented in isolation. The complete study frames growth within demand-side adoption curves, supply-side cultivation and processing capacity, and the regulatory-export infrastructure that conditions international commercialization. That triangulation is essential because American Ginseng is a category where authenticity signaling, compliance documentation, and channel access materially influence realized pricing and velocity.
Executives will find value in how the forecast connects top-line expansion with the operational realities that determine whether growth is captured efficiently or lost to friction. The full report translates the aggregate trajectory into the planning language that product, procurement, and commercial teams require: format mix implications, application-level demand pacing, and regional opportunity gradients that inform where to concentrate sales effort, packaging investment, and trade-support activities.
What the Full Report Delivers: Operational Intelligence Beyond Headlines
PW Consulting’s study is built for execution, not just orientation. The complete report moves beyond top-line sizing to deliver a practical command of the American Ginseng market’s structure, participants, and conditions. It is organized to support three core executive tasks: diagnosing where value is created, identifying where competitive and regulatory pressure is concentrated, and mapping the tactical moves that translate insight into share and margin.
Within the full study, readers will find a structured breakdown of product-format dynamics covering capsules, powders, tablets, and other formats, each examined for its manufacturing implications, consumer-facing positioning, and channel fit. The application-side analysis explores how demand flows across dietary supplements, pharmaceuticals, food and beverages, and cosmetics and personal care, highlighting the distinct purchasing drivers, formulation considerations, and regulatory expectations that differ by end use. Regional analysis maps the market’s geographic architecture across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, providing the comparative context needed to assess saturation, growth runway, and distribution requirements in each territory.
Equally central to the report is its treatment of competitive structure. With a combined share held by the top three competitors at roughly 24 percent and the top five at about 26 percent, the market remains comparatively fragmented, which has direct consequences for bargaining power, channel access, and the role of certification and authenticity in differentiation. In a fragmented environment, strategic advantage frequently accrues to participants who can formalize quality, secure compliant export pathways, and present defensible sourcing narratives to buyers who increasingly scrutinize provenance.
Analytical Modules Designed for Cross-Functional Use
The study is deliberately constructed so that multiple functions can extract directly relevant intelligence without navigating unnecessary abstraction. Key modules include:
- A format- and application-oriented demand framework that connects product architecture to commercial positioning and downstream buying behavior.
- A regional opportunity map that prioritizes where market development, export support, and packaging localization can generate disproportionate returns.
- A competitive landscape assessment that profiles participating organizations by business model, format emphasis, certification posture, and distribution orientation, rather than by brand narrative alone.
- A regulatory and trade-compliance overlay that addresses export documentation, certification programs, and the practical implications of moving cultivated American Ginseng across borders.
- A forward-looking scenario structure that helps leadership test how shifts in sourcing cost, export facilitation, and format adoption could alter planning assumptions over the forecast horizon.
Taken together, these modules enable alignment across R&D, procurement, sales, regulatory affairs, and investor relations. Instead of each function relying on partial data, the report provides a shared operating picture with the depth required to support committed decisions.
Competitive Landscape and the New Shape of Value Creation
The American Ginseng market is shaped by a mix of regional growers, processors, and specialty suppliers whose value propositions increasingly hinge on authenticity, format versatility, and commercial packaging capability. Several participating organizations illustrate the strategic patterns that define the current landscape.
Industry participants based in Wisconsin, a region closely associated with cultivated American Ginseng, demonstrate how origin storytelling, certification, and flexible commercial formats are being combined into defensible market positions. The Ginseng Board of Wisconsin, headquartered in Marathon, Wisconsin, emphasizes wholesale showroom access and 100 percent Wisconsin-grown American Ginseng in roots, tea bags, and slices, supported by the official Seal of the Ginseng Board of Wisconsin for authenticity and premium quality. Its offering spans bulk and private-label packaging options, indicating a dual orientation toward volume supply and branded or co-branded commercial formats. Wisconsin Grown Ginseng LLC operates as a wholesale and bulk supplier of whole roots, powder, slices, tea bags, and extracts, while also offering private-label and custom packaging for commercial use. Dairyland Ginseng similarly focuses on private-label American Ginseng tea and products using high-quality roots, with customizable packaging for tea and bulk herbal products.
These profiles illustrate a broader competitive logic: differentiation is increasingly expressed through format breadth, packaging flexibility, and the ability to present authenticated origin claims to buyers who value traceability and consistency. The full report builds on this pattern by mapping how such business models compete on pricing, service, compliance readiness, and market reach, and by identifying where consolidation, partnership, or channel specialization is likely to reshape positions over the forecast period.
Recent Developments Signaling Market Direction
Current industry activity further clarifies the direction of travel. In July 2025, BioVivo Science launched a water-soluble American Ginseng extract at IFT FIRST 2025, supported by investment in a new U.S. facility intended to enable scalable production and packaging for functional health products. This kind of format innovation matters because solubility and processing characteristics influence downstream formulation opportunities in supplements, beverages, and other functional applications.
In May 2025, the American Herbal Products Association attended the U.S. Ginseng Summit to represent members, with discussions centered on sustainable practices and packaging for American Ginseng products. Around the same time, the Ginseng Board of Wisconsin received a $250,000 USDA AFTPP funding allocation to promote ginseng exports and support packaging for international markets. These developments are not isolated headlines; they reflect coordinated attention to sustainability, export viability, and packaging readiness, all of which affect how quickly and efficiently product can be positioned in overseas channels.
The complete report interprets such developments within a broader structural context, linking product innovation, association-level coordination, and public funding support to the practical realities of commercialization, export compliance, and category scaling.
Regulatory, Certification, and Trade Dynamics as Competitive Variables
American Ginseng is not a commodity that moves freely without documentation. Trade and certification frameworks are integral to how value is created and how risk is managed. Export shipments are subject to CITES export permit requirements administered by the U.S. Fish and Wildlife Service, including USDA Protected Plant Permits for commercial trade. On the cultivation and certification side, the Wisconsin Ginseng Certification Program administered by MDARD certifies cultivated American Ginseng roots for sale and export compliance with federal and state laws.
At the same time, authenticity signals continue to shape purchasing decisions. The Ginseng Board of Wisconsin Seal is designed to ensure 100 percent Wisconsin American Ginseng authenticity on product packaging for growers and processors, reinforcing a provenance-based differentiation strategy that resonates with downstream buyers seeking consistency and traceability. Alongside this, the USDA Foreign Agricultural Service allocation of $250,000 to the Ginseng Board of Wisconsin for ginseng export promotion and packaging support in fiscal 2026 underscores how public-sector facilitation can influence market access and presentation quality in export destinations.
These regulatory and certification elements are not peripheral. They influence lead times, documentation burden, packaging strategy, and the credibility of origin claims. The full report weaves these dynamics into the commercial analysis so that organizations can anticipate compliance requirements, assess the cost of market access, and evaluate where certification and authenticity may function as competitive differentiators rather than mere administrative obligations.
How 2026 Decision-Makers Should Use This Research
A study of this scope is most valuable when it is embedded into a specific decision process. For 2026 planning, the report is designed to support several concrete applications:
- Portfolio and format strategy: determining where to expand across capsules, powders, tablets, and other formats based on manufacturing feasibility, buyer preferences, and channel compatibility.
- Sourcing and supply planning: assessing the implications of fragmented competition, authenticated origin positioning, and export documentation on procurement strategy and vendor selection.
- Geographic prioritization: identifying which regional markets warrant deeper commercial investment, trade-support engagement, or packaging localization.
- Application targeting: aligning product development and commercialization efforts with the demand characteristics of dietary supplements, pharmaceuticals, food and beverages, and cosmetics and personal care.
- Risk and scenario planning: testing how changes in export facilitation, formulation innovation, and certification requirements could affect cost structures and market timing.
In practice, these uses depend on access to the segment-level detail, company profiles, and comparative frameworks that the full report provides. The executive brief establishes the strategic stakes; the complete study delivers the structured evidence required to act on them.
Conclusion: From Market Awareness to Market Advantage
The American Ginseng market is entering a phase in which disciplined intelligence will separate resilient strategies from reactive ones. With a credible historical baseline, a forecast period extending to 2032, and a growth trajectory averaging 5.2 percent annually, the category presents a meaningful but nuanced opportunity. Realizing that opportunity requires more than awareness of size and pace. It requires clarity on format and application dynamics, regional opportunity gradients, competitive differentiation through authenticity and packaging, and the regulatory and trade conditions that shape export readiness.
Saponin Market
PW Consulting’s full American Ginseng Market Research is built to provide that clarity. It combines methodological rigor with commercial relevance, giving leadership teams a shared foundation for sourcing, product, geographic, and compliance decisions. This preview has outlined the strategic architecture and the practical utility of the study; the complete report goes further, delivering the segment-level intelligence, competitor mapping, and scenario detail needed to convert market insight into decisive advantage.
For executives preparing for 2026 and the forecast years that follow, the next step is clear: access the full study to obtain the comprehensive data, frameworks, and company-level analysis that will support informed, confident strategy.
For detailed analysis of this topic, please visit the official page: American Ginseng Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Frozen Bakery Market Hits $215B in 2025, Projected to Reach $344.8B by 2032 at 5.67% CAGR
By pmarketresearch, 2026-09-15
Strategic Horizons in the Frozen Bakery Products Market: Navigating Growth Through 2032
The global landscape for baked goods is undergoing a profound transformation, driven by shifting consumer preferences, operational efficiencies, and the relentless pursuit of convenience. For senior executives and strategic planners, the frozen bakery segment represents not merely a subset of the broader food industry, but a critical vector for growth and resilience. At PW Consulting, we have meticulously compiled a comprehensive market research report designed to equip leadership teams with the actionable intelligence required to thrive from 2026 through 2032.
This analysis serves as a strategic compass. While the industry buzzes with anecdotal trends, decision-makers need rigorous, data-backed forecasts to allocate capital effectively. Our latest study dissects the Frozen Bakery Products Market with a granularity that reveals both immediate opportunities and long-term structural shifts. Below, we outline the macro-economic trajectory and the operational realities defining this sector, offering a glimpse into the depth of our full findings.
Market Trajectory: From Historical Resilience to Future Expansion
Understanding the momentum of the frozen bakery sector requires a clear view of its historical performance and projected pathway. The market has demonstrated remarkable stability and growth over the past half-decade, recovering from global supply chain disruptions and emerging stronger. Our data indicates that the overall market size has climbed steadily, reaching significant valuation milestones in the base year of 2025.
Looking forward, the forecast period from 2026 to 2032 suggests a continued upward trajectory. The compound annual growth rate (CAGR) is projected to sustain a healthy pace, reflecting enduring demand across retail and foodservice channels. This growth is not accidental; it is underpinned by the convenience factor associated with frozen dough and pre-baked items, which appeals to both time-pressed consumers and commercial kitchens seeking consistency. By 2032, the revenue landscape is expected to expand substantially, offering substantial upside for stakeholders who position themselves correctly during the early years of this forecast window.
However, aggregate numbers only tell part of the story. The true value of this research lies in understanding the velocity of growth across different vectors and the specific drivers fueling this expansion. Our full report details the numerical forecasts that will allow your finance and strategy teams to model revenue scenarios with precision.
Navigating the Competitive Arena
The competitive dynamics within the frozen bakery industry are characterized by a mix of global giants and specialized regional players. Market concentration remains a key focus for strategic analysis, as understanding the power distribution among top firms is essential for assessing market entry barriers and partnership opportunities. Our report profiles the key companies that are shaping the industry, providing a detailed look at their strategic offerings and market positions.
Leaders in this space include major global producers such as Grupo Bimbo, which maintains a strong distribution network in retail and foodservice with a vast portfolio of frozen breads and pastries. Similarly, North American powerhouses like Conagra Brands and General Mills continue to leverage iconic brands to capture shelf space and consumer loyalty with ready-to-bake and frozen dough solutions. In Europe, companies like ARYZTA AG, Lantmännen Unibake, and Europastry demonstrate the dominance of specialized frozen solutions, particularly in viennoiserie and artisanal breads.
Strategic consolidation and innovation are key themes among these players. For instance, recent activity highlights how companies are securing supply chains and expanding geographic footprints. Vandemoortele's integration of Délifrance into its portfolio marks a significant move to consolidate frozen bakery assets globally. Likewise, Europastry's acquisition of a majority stake in a Thailand-based baker signals a aggressive push into Asian markets. These moves are not isolated; they reflect a broader industry trend where scale and geographic diversity are becoming critical defenses against volatility.
Additionally, operational sustainability is becoming a differentiator. Recent initiatives by major players to reduce carbon emissions across frozen operations underscore the growing importance of ESG metrics in vendor selection and brand reputation. Our full competitive landscape section provides deep dives into the specific product offerings, distribution strategies, and recent corporate developments for each key entity, allowing you to benchmark your own strategy against the market leaders.
Segmentation Dynamics: Type, Application, and Regional Nuances
A one-size-fits-all approach is insufficient in a market as diverse as frozen bakery products. Success depends on recognizing the distinct performance characteristics of various product types and application channels. Our research segments the market to reveal where demand is strongest and where margins are most favorable.
In terms of product type, categories such as bread and rolls continue to form a substantial foundation of the market, while cakes, pastries, and pizza crusts offer niche growth avenues. The ready-to-bake application segment, in particular, shows significant volume, reflecting the consumer desire to engage in baking without the labor of starting from scratch. Ready-to-eat options cater to immediate consumption needs, while ready-to-proof products serve specific commercial baking workflows. Understanding the interplay between these segments is crucial for product development teams.
Geographically, the market exhibits varied growth patterns. While North America and Europe remain mature and substantial markets, the Asia Pacific region presents compelling opportunities for expansion, driven by urbanization and changing dietary habits. Latin America and the Middle East and Africa also contribute to the global total, with specific regional dynamics influencing import and export flows. For example, recent trade data highlights steady growth in bakery exports to key partners, indicating potential avenues for cross-border commerce. Our report details the regional performance without relying on generic assumptions, providing specific forecasts that account for local economic conditions and consumer behaviors.
We advise clients to look beyond the headline numbers. The interaction between regional preferences and product types often creates unique white spaces. For instance, the demand for specific pastry types in European markets differs markedly from the preferences driving the pizza crust segment in the Americas. Our segmentation analysis helps identify these specific opportunities.
Operational Realities and External Drivers
Strategic planning cannot occur in a vacuum. The frozen bakery sector is influenced by a complex web of operational challenges and regulatory requirements. Our report integrates these external factors to provide a realistic view of the operating environment.
Labor costs and availability remain a persistent pressure point. Persistent labor shortages across industrial baking are reshaping product demand patterns and raising operational expenses. This dynamic is accelerating the adoption of frozen and par-baked solutions, as foodservice operators look to mitigate labor risks while maintaining quality. Conversely, raw material costs present a mixed picture. While cereal and bakery product prices have seen fluctuations, recent data suggests a moderation in the rate of increase compared to historical averages, though vigilance is required to manage input costs effectively.
Regulatory compliance is another critical layer. In key markets like the United States, food labeling requirements mandate strict adherence to ingredient declaration and allergen information standards. FDA regulations require all ingredients to be declared by their common or usual name in descending order of predominance, and nutrition facts must be clearly presented. For exporters, understanding these labeling mandates is essential to avoid market access issues. Furthermore, trade dynamics, such as specific export performance to regions like Australia, illustrate the potential for international growth when regulatory and logistical hurdles are managed correctly.
The Strategic Imperative for 2026 and Beyond
As we move into 2026, the window for proactive strategic adjustment is open. Companies that rely on outdated market assumptions risk losing ground to agile competitors who are leveraging data to optimize their portfolios. The frozen bakery market is poised for significant evolution, driven by the convergence of convenience, health consciousness, and supply chain optimization.
Recent industry developments underscore this momentum. The launch of gluten-free frozen bakery lines by major players indicates a response to health-conscious consumer demands. Such innovations are not merely product launches; they are strategic pivots that redefine category boundaries. Similarly, sustainability initiatives aimed at reducing carbon emissions by significant percentages by 2030 show that environmental responsibility is being baked into the operational core of leading firms.
Frozen Pizza Market
Our full market research report goes beyond these high-level observations. It provides the detailed segmentation data, competitor profiles, and quantitative forecasts necessary to build a robust business case for investment, expansion, or consolidation. We analyze the specific value chains, distribution channels, and consumer trends that will define the next seven years.
For decision-makers, the value of this intelligence lies in its ability to reduce uncertainty. Whether you are evaluating a potential acquisition, launching a new product line, or entering a new geographic market, the detailed insights contained in our full study offer the evidence base required to de-risk your strategy. The market size projections, growth rates, and concentration metrics provided in the complete report allow for precise modeling of potential returns.
Frozen Bakery Products Market
The frozen bakery sector offers a pathway to growth, but only for those who navigate it with clarity. By understanding the competitive moves of giants like Grupo Bimbo and Vandemoortele, the shifting demands of consumers for ready-to-bake solutions, and the operational constraints of labor and regulation, your organization can position itself to capture value in this expanding marketplace.
We invite you to delve deeper into the data. The overview provided here highlights the strategic landscape, but the complete report contains the specific numerical forecasts, granular segmentation splits, and detailed company profiles that will inform your specific decisions. Explore the full study to unlock the comprehensive intelligence needed to lead in the Frozen Bakery Products Market through 2032.
For detailed analysis of this topic, please visit the official page: Frozen Bakery Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Refrigerated Display Cases Market Hits $9.83 Billion in 2025, Projects 7.4% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence in the Cold Chain: Navigating the Refrigerated Display Cases Market Outlook 2026–2032
Executive Summary: The Imperative for Data-Driven Decision Making
The global refrigeration landscape is undergoing a structural transformation driven by tightening environmental regulations, evolving consumer expectations for product visibility, and relentless pressure on operational energy costs. For stakeholders across retail, foodservice, and commercial refrigeration, the Refrigerated Display Cases Market represents a critical nexus of capital expenditure, compliance risk, and revenue generation. PW Consulting has synthesized a comprehensive market research study spanning the historical trajectory from 2020 through 2025 and projecting forward to 2032. This analysis delivers the strategic intelligence required to navigate the complexities of the 2026 market environment and beyond. The research is designed not merely as a static snapshot, but as a dynamic planning tool that equips executives, procurement leaders, and investors with the granular insights necessary to allocate capital efficiently and hedge against systemic volatility.
Macro Trajectory and Revenue Projections
Understanding the overarching revenue trajectory is the first step in framing strategic investments. Over the historical review period, the market demonstrated consistent expansion, rising from a baseline of 6,865.0 million USD in 2020 to 9,830.0 million USD by 2025. This upward momentum is projected to continue, with the market valuation expected to reach 10,331.18 million USD in 2026 and accelerate toward 16,140.0 million USD by the end of the forecast period in 2032. The analysis indicates a robust compound annual growth rate of 7.4 percent over the 2026 to 2032 forecast window. This macroeconomic expansion is underpinned by widespread modernization initiatives in grocery and convenience sectors, alongside mandatory upgrades triggered by regulatory shifts. However, aggregate figures only tell part of the story. The true strategic advantage lies in dissecting the velocity of growth across different technological architectures, application verticals, and geographic corridors, each of which presents distinct risk-return profiles for market participants.
Core Report Architecture and Actionable Intelligence
The complete research study is structured to provide end-to-end visibility into the market ecosystem, enabling stakeholders to build resilient business strategies. The report delivers a multi-dimensional analysis that moves beyond surface-level observations to uncover the operational and financial drivers shaping the industry. Key components include:
- Comprehensive profiling of market segmentation by product architecture, covering plug-in, remote, and semi-plug-in configurations, with detailed assessments of their respective adoption curves and total cost of ownership implications.
- Deep-dive evaluation of application verticals, examining how demand dynamics diverge between food service operations and retail food and beverage environments, including channel-specific purchasing behaviors and capacity utilization metrics.
- Regional market mapping that quantifies demand intensity, infrastructure readiness, and competitive saturation levels across major economic zones, providing a framework for prioritizing market entry or expansion initiatives.
- Supply chain and raw material analysis that tracks pricing volatility, component availability, and manufacturing constraints affecting critical inputs such as tempered glass, stainless steel, and aluminum, alongside mitigation strategies for procurement teams.
- Regulatory impact modeling that quantifies the financial and operational consequences of compliance mandates, including refrigerant charge limits, energy efficiency certification requirements, and phase-out timelines for legacy technologies.
- Competitive benchmarking and strategic grouping of market participants based on product portfolios, geographic footprints, innovation pipelines, and corporate development trajectories.
This structured approach ensures that decision-makers can align technology selection, capital deployment, and partnership strategies with the specific growth vectors and constraint boundaries that define the current market cycle.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderately concentrated competitive environment, with the top three participants collectively commanding approximately 48.0 percent of total revenue and the leading five firms accounting for 57.0 percent. This concentration reflects the high barriers to entry associated with engineering certification, distribution network development, and compliance with stringent energy and environmental standards. The competitive field features a mix of established multinational manufacturers and specialized regional players, each pursuing distinct value propositions to differentiate their offerings.
In North America, prominent players such as Hussmann Corporation from Chicago, Carrier Commercial Refrigeration based in Syracuse, Zero Zone Inc. from Madison, True Manufacturing Co. Inc. in Saint Augustine, Hillphoenix Inc. in Fort Worth, and Kysor Warren in Dallas maintain strong market positions through expansive product lines and direct service networks. Hussmann, for instance, has built its reputation on a comprehensive lineup of multi-deck, island, and reach-in merchandisers that integrate natural refrigerants, energy-efficient lighting, and customizable configurations tailored to retail and foodservice environments. Carrier Commercial Refrigeration emphasizes integrated store systems and display cases featuring both plug-in and remote solutions, with a strong focus on low-GWP refrigerants and smart control architectures that enable centralized monitoring and optimization. Zero Zone Inc. offers a suite of series including Crystal, Highlight, Guardian, and Reveal, alongside its Hybrid and ultra-narrow models engineered for energy efficiency and space optimization in constrained retail footprints. True Manufacturing Co. Inc. focuses on reach-in coolers, glass-door merchandisers, and display cases that prioritize durability, LED lighting integration, and energy performance across both foodservice and retail applications. Hillphoenix Inc. has positioned itself at the forefront of sustainable refrigeration with its AdvansorFlex CO2 and SoloChill series, which are optimized for energy efficiency, serviceability, and transcritical system performance. Kysor Warren contributes specialized refrigerated merchandisers engineered for durability, reliability, and labor savings in supermarket and retail settings.
European manufacturers bring distinct engineering philosophies and regulatory compliance expertise to the global market. Epta S.p.A., headquartered in Vimercate, Italy, delivers the Zenith and Costan lines of vertical and multi-deck refrigerated cabinets, achieving up to 36 percent energy savings through natural refrigerants and PFAS-free insulation, with EU Energy Class B certification. Arneg S.p.A., based in Bologna, emphasizes modular and plug-in refrigerated cabinets with a strong emphasis on sustainable refrigeration and custom store design solutions that adapt to varied retail formats. AHT Cooling Systems GmbH from Austria offers the BOREA and plug-in multideck refrigerated cases utilizing natural refrigerants such as R290, targeting retail outlets and convenience stores with compact, efficient configurations. In the Asia-Pacific region, Hoshizaki Corporation in Nagoya, Japan, provides reliable refrigerated display cases with a focus on convenience store and foodservice segments, emphasizing durability and energy performance. Frigoglass S.A.I.C., based in Athens, Greece, supplies glass-door coolers and refrigerated cabinets tailored for beverage and food display, supported by an international distribution network that extends its reach across multiple continents.
Refrigerated Display Cases Market
Recent Industry Movements and Innovation Signals
Recent corporate activities underscore the pace of technological advancement and the strategic importance of product innovation in capturing market share. In September 2025, Hussmann Corporation launched the RLN-A and RMN-A reach-in merchandisers, incorporating Air-Cooled Microblock technology designed to improve product temperature retention and enhance energy efficiency. This launch reflects a broader industry trend toward thermal management optimizations that directly impact both compliance standing and operating cost structures. In July 2025, Epta S.p.A. showcased the MD3 double-sided multideck cabinet at Metcash 2025, a configuration offering up to 30 percent floor space reduction for independent retail stores. Such space-saving innovations address the persistent challenge of maximizing merchandising density without compromising cooling performance or customer accessibility. In April 2025, Hillphoenix Inc. introduced ChargeSecure technology for CO2 refrigeration systems, delivering 1.5 amps operation and consuming six times less energy than conventional units. These developments highlight the competitive advantage accruing to manufacturers that can simultaneously address energy efficiency, refrigerant compliance, and operational reliability. Stakeholders who track these innovation cycles gain early visibility into emerging product standards and can align their procurement or development roadmaps accordingly.
Regulatory Pressures and Material Constraints Shaping Market Dynamics
The 2026 market environment is being reshaped by a confluence of regulatory mandates and material supply dynamics that demand proactive strategic adaptation. Starting January 1, 2026, new installations of Hybrid merchandisers are prohibited under the AIM Act, requiring replacement with low-GWP refrigerant alternatives. This regulatory shift, coupled with low-GWP refrigerant requirements under the AIM Act that limit refrigerant charge to 200 pounds for new installations, is driving accelerated adoption of R-290 and CO2 systems in display cases. These constraints are not merely compliance checkboxes; they fundamentally alter the economics of product selection, installation logistics, and long-term service contracts.
In parallel, EU Energy Class B certification mandates for vertical refrigerated cabinets are compelling manufacturers and end-users to prioritize high-efficiency designs. Epta's Zenith line, achieving up to 36 percent energy savings through natural refrigerants and PFAS-free insulation, exemplifies the performance benchmarks now required to meet these standards. On the materials front, glass doors dominate refrigerated display cases, with tempered safety glass capturing approximately 38.7 percent market share due to its optical clarity and hygiene compliance. Stainless steel and aluminum remain primary structural materials, and while component costs including steel, aluminum, and glass showed moderated price volatility in 2025, persistent supply chain risks continue to warrant careful inventory planning and supplier diversification. These regulatory and material factors interact to create a complex decision matrix where energy performance, compliance timelines, and input cost stability must be evaluated in concert.
Strategic Implications for 2026 and the Path Forward
The refrigerated display cases market in 2026 presents a landscape where growth is accessible but competition for share is intensifying, and where regulatory compliance is no longer a peripheral concern but a central pillar of product strategy. Organizations that succeed in this environment will be those that integrate macro demand signals with micro-level insights into product architectures, regional adoption patterns, and competitive maneuvering. The full study provides the detailed segmentation data, regional revenue breakdowns, application-specific growth rates, and competitor benchmarking matrices necessary to construct precise market entry strategies, optimize portfolio mixes, and anticipate regulatory-driven demand shifts. Readers seeking to unlock the complete dataset and proprietary analytical frameworks are encouraged to access the source research portal, where the full report delivers the granular intelligence required to inform capital allocation, technology roadmapping, and long-term competitive positioning.
Worldwide Home Display Case Market
For detailed analysis of this topic, please visit the official page: Refrigerated Display Cases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Basmati Rice Market to Hit $315.1M by 2032, Growing at 6.98% CAGR
By pmarketresearch, 2026-09-15
Strategic Horizons: Navigating the Global Basmati Rice Market in 2026 and Beyond
Executive Summary: The Imperative for Precision Intelligence
The global basmati rice sector stands at a critical juncture where traditional trade flows intersect with shifting regulatory frameworks, evolving consumer preferences, and strategic realignment among key producing nations. For executives, procurement leaders, and market strategists operating in 2026, relying on retrospective summaries or anecdotal trade intelligence is no longer sufficient. The market is characterized by compounding macroeconomic pressures, fragmented supply chains, and highly asymmetric information flows across regions. Our latest basmati rice market research was designed to close that gap.
Prepared as a comprehensive analytical foundation rather than a superficial industry overview, this report translates multi-year historical performance and forward-looking model trajectories into actionable strategic intelligence. It is engineered to support pricing architecture, sourcing diversification, capacity planning, export positioning, and risk mitigation across the entire basmati value chain. The following sections outline the analytical rigor, structural frameworks, and decision-ready content embedded within the study, demonstrating why it serves as a critical reference point for enterprise strategy in the current operating environment.
Market Trajectory and Structural Momentum
Historical baselines spanning 2020 through 2025 reveal a market that has absorbed external disruptions, adapted to shifting demand patterns, and consistently expanded its revenue footprint. Over this period, the global basmati rice market progressed from approximately $147.5 million to $198.0 million, reflecting sustained growth driven by expanding consumer adoption, strengthening trade linkages, and product standardization across major export corridors. This historical momentum establishes a reliable baseline for evaluating forward performance.
The forward trajectory extends through 2032, projecting continuous expansion with a compound annual growth rate of 6.98 percent. Under this modeled pathway, market revenue scales from an estimated $205.89 million in 2026 to over $315.1 million by 2032. These figures represent aggregate market evolution rather than isolated product or channel spikes, indicating that underlying demand drivers are structural rather than cyclical. Importantly, this growth is unevenly distributed across geographies and product formats, meaning that generalized assumptions can misallocate capital or expose firms to avoidable margin compression.
Because growth is not uniform, decision-makers require granular visibility into where value is concentrating, which formats are driving incremental dollar share, and how regional demand elasticity interacts with trade policy shifts. The report addresses this complexity by mapping historical inflection points, identifying the mechanisms behind period-over-period revenue shifts, and situating forward projections within established market architecture. The objective is to enable firms to distinguish between durable expansion and temporary arbitrage opportunities, ensuring that investment and sourcing commitments align with long-term structural realities rather than short-term headline noise.
Report Architecture: Operational Content for Execution Teams
A market study only delivers value when it translates into executable direction. Accordingly, this publication was structured around operational deliverables that procurement, commercial, and strategy teams can integrate directly into planning cycles. The analytical architecture moves from macro validation to segment-level mechanics, then to competitive and regulatory overlays, ensuring that every conclusion is traceable to methodologically consistent inputs.
Core components include a full historical reconstruction from 2020 through 2025, with period-over-period revenue movements contextualized against demand shifts, pricing behavior, and trade flow adjustments. The forward modeling covers 2026 through 2032 and is built on scenario-sensitive assumptions, allowing leadership to test sensitivity around volume growth, price realization, and policy-induced supply changes. Rather than presenting a single deterministic path, the study incorporates structural variability so that organizations can evaluate performance under differing operating conditions.
The segmentation framework examines the market through format distinctions, demand-end utilization patterns, and regional allocation trends. These dimensions are deliberately analyzed in combination because basmati rice performance cannot be understood through a single lens. Format shifts influence processing requirements and pricing tiers. Demand-channel dynamics shape inventory velocity, promotional strategy, and margin structure. Regional performance reflects trade agreements, tariff exposure, logistical constraints, and consumer preference evolution. By treating segmentation as an interconnected system, the report enables readers to identify which combinations are generating disproportionate value and where realignment may be necessary.
Another critical layer is competitive and institutional mapping. The study profiles the organizations shaping production, export coordination, trade facilitation, and downstream brand positioning. It does not limit analysis to product attributes; it also evaluates how trade bodies, industry associations, and export federations influence market access, policy advocacy, certification environments, and negotiating leverage. This institutional dimension is especially relevant in agricultural commodity markets, where collective representation and government-aligned export frameworks can alter competitive outcomes as significantly as individual firm strategy.
Basmati Rice Market
Finally, the regulatory and macro context is integrated throughout rather than isolated as a standalone appendix. Trade restrictions, tariff adjustments, floor price mechanisms, certification requirements, and supplier registration processes are analyzed for their direct impact on cost structures, shipment timing, and market-entry feasibility. This ensures that strategic recommendations are grounded in operational reality, not abstract market sizing.
Competitive Architecture and Institutional Dynamics
The basmati rice ecosystem is shaped by a mix of commercial producers, export associations, and institutional research bodies, each exerting influence over pricing, quality standards, supply reliability, and market access. Understanding this architecture is essential for firms seeking to navigate sourcing decisions, brand positioning, and regional expansion strategies.
Among commercial brand actors, RiceSelect operates as an active US-based producer offering Texmati White Rice, a hybrid basmati-style aromatic long-grain product developed through previous RiceTec lineage. The company emphasizes non-GMO, gluten-free, and Kosher-certified positioning while expanding sustainable lines that include Premium Indian Basmati Rice. For downstream distributors and retail partners, this profile signals a strategy that blends American-market familiarity with international basmati credentials, emphasizing certification, product consistency, and sustainability messaging as differentiators. The strategic implication is not merely product availability but brand architecture: firms entering or expanding in the US market must contend with players that are actively bridging origin credibility with domestic retail expectations.
On the export coordination side, the Rice Exporters Association of Pakistan (REAP) serves as a central institutional vehicle for Pakistani basmati rice exporters. Its function extends beyond membership administration to include trade delegation facilitation, global market promotion, and direct engagement with overseas buyers. Recent US engagement activities illustrate how producer-country associations increasingly act as coordinated market-access platforms, helping align exporter interests with foreign distributor expectations. In a market where origin perception, pricing competitiveness, and compliance readiness all influence purchasing decisions, such institutional coordination can materially affect the speed and scale at which supplying countries expand footprint.
The India Rice Exporters Federation (IREF), based in New Delhi, operates as an apex trade body representing Indian rice exporters. It supports basmati producers and facilitates policy advocacy directed at export-oriented production and trade. Given the scale and global prominence of Indian basmati shipments, IREF’s advocacy and coordination role influences how exporters interpret regulatory shifts, manage certification obligations, and respond to policy recalibration. In practical terms, these institutions function as information and negotiation hubs, shaping how producer-country supply responds to international price signals and import-country trade rules.
Competitive understanding also requires situational awareness of recent high-visibility events that expose operational vulnerabilities and accelerate structural adjustments. A voluntary recall involving Kirkland Signature Traditional Basmati Rice in the US retail environment underscores the sensitivity of consumer-facing supply chains to quality assurance failures. Even when isolated, incidents of this nature affect retailer confidence, audit expectations, and supplier qualification standards. For sourcing teams, the lesson is not simply risk avoidance but the need for rigorous traceability, batch control, and supplier compliance documentation across the basmati supply chain.
Equally relevant is the institutional push toward input efficiency and cultivation modernization. The launch of new RobiNOweed Basmati Rice varieties developed for direct seeded rice cultivation reflects an industry-level response to resource constraints, particularly water usage. Varieties designed for DSR systems can alter production economics, yield stability, and regional planting patterns. For buyers and analysts, such developments signal potential shifts in supply-side cost structures and long-term agronomic conditions, especially in producing regions where water availability and labor economics remain pressing considerations.
Regulatory and Trade Realignment: Mapping Systemic Risk
Trade policy and regulatory design have become central determinants of basmati rice competitiveness. In 2026, market participants cannot evaluate sourcing or export strategy without accounting for tariff asymmetry, floor price changes, export restriction cycles, and registration frameworks that govern shipment eligibility.
A significant competitive shift emerged from tariff divergence affecting US import dynamics. The imposition of a 50 percent tariff on Indian basmati rice imports raised effective landed costs and altered relative price positioning in the American market. This development created conditions in which Pakistani basmati rice, subject to a lower tariff rate, gained renewed competitiveness. The strategic consequence is not a simple swap of origin preference; it is a recalibration of price-sensitive procurement, brand positioning, and distributor negotiation leverage. Firms that fail to incorporate tariff-adjusted landed cost modeling into sourcing decisions risk mispricing, margin erosion, or suboptimal supplier allocation.
Regulatory recalibration in the producing country context further complicates planning. India’s policy actions included the lifting of export restrictions on non-basmati white rice alongside the removal of the basmati minimum export floor price, changing the incentive structure for exporters and downstream traders. These adjustments influence shipment timing, export willingness, and downstream pricing expectations across the broader rice trade architecture. Even when a firm’s focus is basmati specifically, non-basmati policy moves matter because they affect total export capacity, logistics utilization, and the strategic behavior of exporters who manage multiple product categories simultaneously.
At the same time, institutional registration and allocation mechanisms remain critical for market participation. APEDA’s issuance of a substantial volume of registration cum allocation certificates for Indian basmati rice exporters during the 2024-25 fiscal year demonstrates the continued role of formalized export authorization in governing shipment eligibility and trade transparency. For international buyers and distributors, the existence of structured registration systems reinforces the importance of verifying exporter status, allocation compliance, and documentation readiness before committing to supply agreements.
Pakistan’s ongoing efforts to expand US market presence also highlight the strategic importance of distributor engagement, pricing alignment, and compliance readiness. Trade discussions involving US distributors reflect a deliberate push to secure market access through commercial and regulatory coordination. In practice, this means that competitive advantage in target markets increasingly depends on a supplier’s ability to demonstrate consistent quality, price competitiveness under tariff conditions, and adherence to buyer-specific compliance expectations.
Procurement, Pricing, and Expansion Strategy in 2026
For enterprise decision-makers, the strategic question is not whether the basmati rice market is expanding, but how to position operations to capture value without overexposing the organization to compliance, pricing, or supply continuity risk. This requires a disciplined approach to sourcing architecture, pricing strategy, and market-entry planning.
Sourcing diversification should be evaluated through the lens of landed-cost realism rather than origin branding alone. Tariff differentials, logistics reliability, certification requirements, and supplier compliance maturity all influence effective cost. Firms that maintain concentration in a single origin or a narrow supplier base may find themselves vulnerable to policy shifts or trade-flow disruptions. A more resilient approach involves mapping multiple qualified sources, stress-testing scenarios against tariff and floor-price changes, and aligning supplier selection with specified audit and documentation expectations.
Pricing architecture must account for volatility in both input markets and trade policy. Floor price changes, tariff adjustments, and recall-driven quality reassessments can alter the price environment faster than traditional seasonal forecasting anticipates. Organizations should incorporate scenario-based pricing models that include tariff-adjusted comparisons, compliance cost assumptions, and quality-assurance overhead. This helps prevent margin compression when external conditions shift unexpectedly.
Market expansion planning should be equally disciplined. Regional demand patterns differ materially in terms of channel structure, price sensitivity, and certification expectations. Retail and household demand typically favors consistent quality, packaging reliability, and brand trust, while foodservice and hospitality channels emphasize volume consistency, specification adherence, and operational reliability. Understanding which demand environment a firm is entering allows more precise commercial execution and reduces the risk of misaligned positioning.
Quality assurance and traceability also deserve elevated strategic priority. High-visibility quality incidents in consumer-facing channels demonstrate that retailer confidence can be fragile. Supplier qualification processes should therefore go beyond basic product specifications to include traceability systems, batch control discipline, documentation completeness, and audit responsiveness. In a market where brand reputation and retailer trust are closely tied to supply integrity, these capabilities can function as competitive differentiators.
Organic Rice Market
Finally, developments in cultivation technology and resource efficiency should be monitored as longer-term supply-side indicators. Agronomic shifts that reduce water usage or improve direct seeding viability can influence regional production economics and supply stability over time. While these changes may not translate immediately into short-term pricing moves, they are relevant to medium- and long-term sourcing strategy, especially for organizations with multi-year supply commitments or regional expansion targets.
Why the Full Study Matters for Executive Decision-Making
The basmati rice market presents a paradox that many organizations underestimate: the headline trajectory is strong, but the operational levers that determine success are highly specific. Aggregate growth figures and broad regional performance indicate favorable conditions, yet they do not reveal which formats are generating disproportionate revenue, which channels are most sensitive to price or certification shifts, or how tariff and policy divergence is reshaping competitiveness in key import markets. Without segment-level clarity, firms risk making allocation, pricing, and sourcing decisions on incomplete pictures.
This report is built to resolve that ambiguity. It connects historical performance with forward modeling, embeds segmentation analysis within the broader market architecture, and overlays competitive and regulatory dynamics so that decision-makers can see not only where the market is heading, but also what actions are required to respond effectively. The objective is to provide a defensible analytical foundation for procurement strategy, commercial planning, brand positioning, and risk management.
Organizations that rely on partial information may identify opportunities, but they often misjudge the cost of pursuing them. In contrast, teams equipped with structured segment insights, scenario sensitivity, institutional mapping, and regulatory context can allocate resources more precisely, negotiate with greater confidence, and anticipate competition more effectively. That is the strategic value the full study is designed to deliver.
To obtain the detailed segmentations, scenario-based projections, competitive profiles, and operational frameworks referenced throughout this overview, access the complete Basmati Rice Market research on the PW Consulting portal. The full intelligence set is structured for immediate integration into enterprise planning workflows and is intended to support decision-making with the level of specificity required for 2026 strategy execution.
For detailed analysis of this topic, please visit the official page: Basmati Rice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cover Glass Market Hits $1.56B with 1.3% CAGR from 2026-2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the 2026 Decision-Maker: Smartphone Cover Glass Market Outlook
The smartphone cover glass market stands at a critical inflection point as industrial leaders navigate the 2026 operating environment. Following five years of moderate historical expansion from 2020 through 2025, the sector now enters a forecast horizon extending to 2032 that demands precise strategic calibration. Our latest market research study translates complex supply-demand signals, regulatory shifts, and competitive maneuvers into actionable intelligence for procurement executives, R&D planners, and C-suite strategists who must allocate capital with confidence in a market defined by high concentration, evolving material science, and geopolitical recalibration.
This introduction outlines the strategic architecture of the full report, demonstrating why leadership teams should treat this assessment as a core input to 2026 portfolio decisions, capacity planning, and supplier negotiations. Rather than presenting a static snapshot, the research functions as a forward-looking decision framework that connects macro trajectory signals to on-the-ground execution priorities.
Market Trajectory and the Strategic Imperative for 2026
Historical revenue data from 2020 through 2025 reveals a market that has demonstrated resilience through cycles of component volatility, shifting OEM demand patterns, and intermittent supply disruptions. The sector crossed the 1,560 million USD threshold in the most recent base year measurement before entering the current forecast window, where trajectory modeling projects growth toward the 1,700 million USD range by the close of the decade. The forecasted compound annual growth rate of 1.3 percent across the 2026 to 2032 period underscores a market characterized by measured, structural expansion rather than explosive volatility.
For decision-makers, this trajectory carries nuanced implications. A modest CAGR in a high-value component category often masks significant underlying shifts in product mix, regional sourcing preferences, and premiumization trends within flagship device portfolios. The market is not simply growing; it is recomposing. Foldable device architectures, chemically strengthened glass specifications, and OEM supply chain localization strategies are altering where margin accrues and which suppliers capture disproportionate value. Strategic leaders who rely on backward-looking averages risk misallocating resources in a landscape where product-level differentiation and capacity positioning matter far more than aggregate market size.
The full report decomposes this trajectory into decision-grade scenarios, enabling teams to map procurement commitments, capital expenditure timing, and partnership strategies against realistic demand pathways rather than single-point projections. Readers are invited to access the complete forecast modeling and scenario analysis on our source page, where detailed growth drivers, sensitivity parameters, and regional momentum indicators are presented in full operational depth.
Competitive Architecture and Supplier Positioning
Market concentration remains a defining structural feature of the smartphone cover glass landscape. With the top three participants commanding approximately 80 percent of revenue and the top five collectively representing roughly 85 percent, the sector operates as an oligopolistic environment where incumbent scale, proprietary material formulations, and long-standing OEM relationships create formidable barriers to displacement. Yet within this concentrated framework, competitive dynamics are intensifying as suppliers race to align capacity with next-generation device requirements and navigate cost pressures from regulatory and raw-material headwinds.
Incumbent Technology Leaders
Corning Incorporated continues to anchor the premium cover glass segment through its Gorilla Glass series, anchoring a substantial share of flagship smartphone adoption. The launch of Corning® Gorilla® Glass Ceramic 3 in March 2026 marks a deliberate push into enhanced drop durability for foldable device architectures, signaling how material innovation is being reoriented around new form factors rather than traditional flat-panel optimization. This product introduction follows a broader capacity expansion effort in early 2026 designed to support high-volume flagship OEM demand across North American and Asian supply networks.
The strategic weight of these moves was reinforced by the August 2025 commencement of production at a Kentucky facility developed in partnership with Apple, representing a 2.5 billion USD investment that consolidated a significant share of iPhone and Apple Watch cover glass manufacturing within a single U.S.-based operation. For the broader market, this capacity concentration illustrates how anchor OEM commitments can reshape regional supply footprints while reinforcing the competitive moat of leading material science firms.
Diversified Global Contenders
AGC Inc. maintains a strong premium positioning through its Dragontrail® product family, delivering chemically strengthened glass solutions targeted at flagship and high-tier device segments. Schott AG continues to compete in the chemically strengthened category with its Xensation® series, including the Xensation® α specification engineered for improved drop performance in flagship smartphones. Nippon Electric Glass Co., Ltd. supplies chemically strengthened cover glass across smartphone and foldable device applications, while AvanStrate Inc. operates production facilities across Japan, Taiwan, and Korea to support display and cover glass requirements for major OEM customers.
In the broader production ecosystem, Biel Crystal Manufactory Ltd. has scaled as a major global producer of cell phone cover glass and sapphire components, with annual production capacity exceeding 1.85 billion units. Lens Technology Co., Ltd. functions as a key supplier of cover glass, structural parts, and functional modules for smartphones, serving major OEMs worldwide. TPK Holding Co., Ltd. rounds out the competitive field as a manufacturer of cover glass and touch solutions for smartphones. Together, these players illustrate a competitive matrix in which differentiation hinges on material specifications, geographic production flexibility, and the ability to secure multi-year OEM program wins.
The report's competitive analysis module provides granular supplier benchmarking, program win trajectory assessment, and capability-to-capacity alignment mapping. Complete supplier profiles, performance scorecards, and strategic risk indicators are available through the full research portal, enabling procurement and R&D teams to pressure-test their current sourcing strategies against an evolving competitive baseline.
Market Dynamics Shaping Strategic Decisions
The operating environment for smartphone cover glass in 2026 is shaped by intersecting forces that extend well beyond simple demand forecasting. Regulatory compliance costs, export control expansions, import surge patterns, raw-material lead-time elongation, and critical material export restrictions all contribute to a more complex sourcing and planning landscape. Decision-makers must integrate these factors into scenario planning rather than treating them as peripheral risks.
Regulatory and Chemical Compliance Pressure
The European Chemicals Agency reported that compliance costs for hydrofluoric acid used in glass tempering processes rose by 15 percent in 2024. This increase directly touches the cost structure of chemically strengthened glass production, a category that constitutes a meaningful share of premium cover glass supply. For procurement teams, the implication is twofold: cost models that rely on historical chemical input assumptions may underestimate current and forward pricing pressure, and supplier negotiations must account for regional regulatory divergence that affects landed cost and availability.
A separate indicator of demand strength and import dependency comes from the U.S. International Trade Commission, which recorded a 17 percent increase in imports of chemically strengthened glass for smartphones in 2024. This import trajectory signals both robust downstream demand and the extent to which supply chains remain internationally interconnected, even as OEMs pursue localized capacity strategies. The tension between import reliance and regional supply expansion is a key theme explored in the full report's dynamics section.
Geopolitical and Supply Chain Disruption Vectors
U.S. export controls on advanced computing items expanded in 2024, creating ripple effects across global supply chains for specialty glass components. While cover glass may not always fall directly within the narrowest controlled categories, the broader export control environment influences manufacturing equipment access, technology transfer constraints, and supplier qualification pathways across multiple jurisdictions. Strategic sourcing plans that do not explicitly model geopolitical fragmentation risk understimating qualification timelines and dual-sourcing complexity.
Compounding these dynamics, supply chain constraints and precursor cost surges drove average lead times for cover glass components to approximately 45 days in 2024. For program managers and inventory planners, extended lead times translate directly into buffer stock requirements, working capital exposure, and scheduling rigidity. The report's operations section translates these lead-time signals into inventory strategy recommendations and supplier diversification frameworks tailored to high-concentration supply markets.
Smartphone Cover Glass Market
In addition, China's Export Control Law and related MOFCOM regulations, updated with detailed rules in October 2024, impose restrictions on exports of critical materials used in display cover glass production. For organizations with material dependencies crossing this regulatory boundary, the compliance pathway now demands explicit mapping of raw-material origin, processing steps, and end-use classification. The research study provides a regulatory impact matrix that helps teams identify where material flow vulnerabilities could affect cost, availability, or program continuity.
Report Contents and Practical Applications
The full market research study is designed as a decision-support toolkit rather than a static market description. It integrates historical baseline analysis, multi-year forecasting, segmentation perspectives, competitive profiling, and dynamic risk factor assessment into a cohesive reference for 2026 strategy development. The following components represent the operational core of the study.
- Market Sizing and Trajectory Framework: A comprehensive revenue trajectory spanning historical baseline years and a forecast window extending through 2032, structured to support demand planning, capacity justification, and investment prioritization. The analysis presents total market perspective alongside segmentation views that illuminate type-based and application-based composition without isolating strategic detail from its broader market context.
- Segment-Level Composition Analysis: Detailed coverage of material type categories and end-use application patterns, enabling teams to understand where revenue concentration lies and how product mix evolution may influence sourcing requirements, specification priorities, and supplier selection criteria over the forecast horizon.
- Competitive Intelligence and Supplier Profiling: In-depth profiles of the key companies shaping the market, including headquarters location, product positioning, recent strategic developments, and capability signals. The study connects company-level moves to market-level implications, allowing readers to assess competitive threats, partnership opportunities, and supply base resilience.
- Dynamics and Risk Factor Integration: A structured treatment of regulatory cost pressures, export control and trade policy developments, import trend indicators, raw-material lead-time dynamics, and critical material export restrictions. This section translates external signals into actionable planning considerations for procurement, compliance, and supply chain leadership.
- Strategic Implications and Decision Scenarios: Synthesis sections that connect market data, competitive signals, and dynamic risks into decision scenarios for capacity planning, supplier diversification, program timing, and technology roadmapping. These scenarios are designed to support internal alignment across R&D, operations, procurement, and executive strategy functions.
Throughout the study, segmentation insights are presented with the discipline required for confidential strategic use: enough structural clarity to inform sourcing and planning logic, while preserving the detailed quantitative granularity that belongs in the paid research deliverable. The complete segmentation splits, scenario parameters, and sensitivity ranges are available in the full report, where they can be applied directly to internal models and negotiation frameworks.
Why This Research Matters for 2026 Decisions
In a market where a small number of suppliers command the majority of revenue, where material specifications are rapidly evolving around foldable and flagship device requirements, and where regulatory and geopolitical factors are reshaping cost and availability assumptions, strategic advantage depends on early visibility and precise interpretation. Aggregate market size alone does not reveal where margin is shifting, which supplier capabilities will be stressed by new device architectures, or how regional compliance costs will alter sourcing economics over the forecast period.
This research is built to answer those questions with the rigor required for enterprise decision-making. It equips leaders with a structured view of market trajectory, competitive positioning, and dynamic risk factors so that 2026 planning can move beyond reactive adjustments and toward proactive portfolio design. Whether the objective is to validate a long-term supplier partnership, prioritize R&D investment in cover glass specifications, or construct a resilient sourcing strategy amid extended lead times and raw-material constraints, the study provides the analytical foundation to make those choices with greater confidence.
The complete market research study, including full forecast modeling, detailed segmentation breakdowns, supplier capability assessments, and dynamic risk matrices, is available through our source page. We encourage strategy, procurement, and product leadership teams to access the full report to integrate these insights directly into 2026 planning cycles and supplier engagement strategies.
Glass Screen Protector Market
For detailed analysis of this topic, please visit the official page: Smartphone Cover Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vegan & Processed Cheese Market Hits $21.3M in 2025, Projects 7.26% CAGR to $28.89M by 2032
By pmarketresearch, 2026-09-15
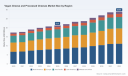
Navigating the Dairy Dilemma: Strategic Insights into the vegan cheese and processed cheeses Market Through 2032
The global landscape for vegan cheese and processed cheeses is undergoing a period of complex transformation. As consumer preferences shift and regulatory frameworks evolve, stakeholders across the value chain are seeking clarity amidst volatility. PW Consulting is pleased to unveil our latest comprehensive market research study, designed specifically to equip executive leadership and strategy teams with the actionable intelligence needed to navigate the forecast period from 2026 to 2032.
This article serves as a strategic primer, highlighting the macroeconomic trajectories and competitive dynamics captured in our full report. While we share high-level indicators here, the nuanced segmentation and granular data required for precise investment decisions are reserved for our licensed partners. The following analysis underscores why this research is critical for 2026 corporate planning.
Macro Market Trajectory and Growth Dynamics
Understanding the baseline momentum is essential for any strategic roadmap. Over the historical period from 2020 to 2025, the market has demonstrated a steady upward trajectory, recovering from early pandemic disruptions and adapting to changing supply chain realities. In 2020, the global market valuation stood at 17.37 Million USD. By the base year of 2025, this figure has grown to 21.3 Million USD, reflecting a cumulative expansion despite intermittent economic pressures.
Looking forward, our forecasts indicate continued growth, albeit with nuanced variations across different horizons. The market is projected to reach 22.03 Million USD in 2026, climbing steadily to 28.89 Million USD by 2032. This progression represents a Compound Annual Growth Rate (CAGR) of 7.26% over the forecast period. Such a rate suggests that while the sector is expanding, it is not immune to correction phases. For decision-makers, this CAGR is not merely a number; it is a benchmark against which internal performance targets and capacity expansion plans must be calibrated.
The divergence between historical performance and future projections hints at underlying structural changes. The slowdown in growth rates observed in certain segments during the base year suggests that volume drivers are shifting. Our report dissects these shifts without relying on superficial top-line numbers, offering a deeper understanding of where value is being created and where erosion is occurring.
Segmentation Nuances: Type and Application
A superficial view of the market often lumps all cheese alternatives and processed varieties into a single bucket. However, the strategic realities for a vegan cheese producer differ vastly from those of a traditional processed cheese manufacturer. Our research provides a detailed breakdown of the market by type, distinguishing between the niche but high-growth potential of vegan cheese and the established volume dominance of processed cheeses.
While processed cheeses continue to hold a significant share of the revenue pool, the vegan segment presents a unique set of challenges and opportunities. The narrative around plant-based dairy has evolved from uncritical hype to a more mature assessment of taste, texture, and price parity. Investors and product developers need to understand the specific revenue contributions of each type to allocate R&D budgets effectively. Our report details these valuations without exposing the specific percentage splits publicly, ensuring that competitive advantages remain protected for our clients.
Similarly, the application landscape reveals critical insights into consumption patterns. The market is driven primarily by retail channels, but the foodservice and industrial ingredients sectors play pivotal roles in scaling distribution. Understanding the volume flow into retail packaging versus bulk industrial usage is vital for supply chain optimization. The report analyzes how demand in these application areas interacts with pricing strategies and shelf-life considerations, providing a holistic view of end-user behavior that goes beyond simple unit sales.
Competitive Landscape and Corporate Maneuvers
The competitive environment is characterized by a mix of agile niche players and established conglomerates diversifying their portfolios. Market concentration remains moderate, with the top three companies holding a combined share of 24.6% and the top five reaching 26.2%. This concentration level indicates a fragmented market where innovation and branding can still disrupt incumbents, but also where consolidation trends are active.
Key players such as Kraft Heinz and Groupe Bel continue to leverage their massive distribution networks and brand equity in the processed cheese sector. Kraft Heinz, with iconic brands like Kraft Singles and Velveeta, maintains a stronghold on the American processed cheese market. Meanwhile, Groupe Bel, known for Babybel and Boursin, is navigating the dual challenge of maintaining dairy core performance while experimenting with plant-based extensions.
On the vegan side, companies like Miyoko's Creamery and Violife are setting standards for quality and availability. Miyoko's Creamery, based in Sonoma, California, focuses on artisanal vegan cheese and butter using traditional fermentation techniques with plant-based ingredients, appealing to premium consumers. Violife, headquartered in the Netherlands, has expanded its dairy-free cheese products to over 50 countries, covering slices, shreds, and spreads. Daiya Foods continues to innovate in melting applications with shreds and slices made from tapioca and nutritional yeast, recently introducing fiery cheese innovations like Chipotle Cheddar Shreds and Pepper Jack Slices in May 2025. Kite Hill offers another angle with vegan cheeses produced from coconut milk and almond milk bases, targeting health-conscious demographics.
Vegan Cheese and Processed Cheeses Market
However, the landscape is fluid. Recent developments highlight the risks and rewards of this sector. In June 2025, Bel Group discontinued its plant-based brand Nurishh and closed its Saint-Nazaire production site, a move that impacted approximately 30 employees and signaled a strategic pivot away from certain plant-based ventures. Conversely, in November 2025, Harvey & Brockless acquired the Julienne Bruno plant-based cheese brand and assets, indicating that consolidation and acquisition remain active strategies for gaining footholds in this space. Additionally, RIND by Dina & Joshua launched the ALPINE SVVISS cashew-based artisan vegan cheese in November 2025, certified gluten-free and kosher Pareve, demonstrating continued innovation in the artisanal premium segment. These events underscore the importance of tracking corporate moves not just as news, but as signals of broader market viability.
Recent Industry Dynamics and Consumer Shifts
Strategic planning for 2026 cannot rely on historical data alone; it must account for the immediate shifts observed in late 2025. Data from the Good Food Institute Retail Sales Data for 2025 indicates that plant-based cheese dollar sales declined 10% while unit sales declined 8%, with average retail prices down 2%. This contraction in value and volume suggests a consumer pullback, potentially driven by price sensitivity or fatigue with existing product formulations. Furthermore, household penetration of plant-based cheese remained at 4% in 2025, indicating that despite widespread availability, mainstream adoption has stalled at a niche level.
These dynamics suggest that the growth story for vegan cheese is no longer a straight line. Companies must reconcile the broader market CAGR of 7.26% with the specific headwinds facing the plant-based sub-sector. Our report integrates these consumer habit shifts into the forecast models, adjusting expectations for volume growth against price erosion. For processed cheeses, the dynamics are different, often tied to inflation-sensitive consumer behavior and ingredient costs. Understanding how these two sub-sectors interact—whether they compete directly or occupy distinct consumption occasions—is a key deliverable of our analysis.
Strategic Deliverables for 2026 Decision-Makers
PW Consulting's Vegan Cheese and Processed Cheeses Market research is designed to be a practical tool for strategy formulation. Beyond the macro data and company profiles, the report offers several core deliverables that address the specific pain points of 2026 planning:
- Regional Performance Analysis: While global totals provide context, regional variances drive local strategy. The report examines performance across key geographies, including North America, Europe, and Asia Pacific, without disclosing specific regional revenue figures publicly. This allows clients to benchmark their local performance against hidden benchmarks and identify high-potential markets for expansion.
- Supply Chain and Cost Structure Insights: With fluctuations in raw material costs and labor impacts, such as the closure of production sites affecting local employment and capacity, understanding cost drivers is essential. The study analyzes the cost structures influencing margins across different product types.
- Innovation Roadmap Guidance: Given the product launches seen in 2025, from spicy variants to artisanal cashew-based options, the report categorizes innovation trends. It helps R&D teams understand which flavor profiles, bases, and certifications are gaining traction versus those that are saturating the market.
- Risk Assessment and Mitigation: The discontinuation of brands like Nurishh serves as a case study in portfolio risk. The report includes an assessment of market risks, including regulatory changes and consumer sentiment shifts, helping companies build more resilient product pipelines.
Our analysis goes further to explore the interplay between retail and foodservice channels. The stability of retail sales versus the volatility of foodservice demand post-pandemic and during economic slowdowns is a critical variable. By isolating these application streams, we provide clarity on where volume is most secure and where promotional intensity is required to maintain share.
Conclusion: The Imperative for Deep Intelligence
As the market moves from 2026 toward 2032, the distinction between success and stagnation will lie in the quality of intelligence guiding corporate strategy. The headline CAGR of 7.26% is attractive, but it masks the complexities of a market where plant-based sales are contracting while processed cheese volumes face their own inflationary pressures. Companies that rely on generic industry reports risk misallocating capital into segments that are shrinking in value even if units remain stable.
Processed Cheese Market
PW Consulting's full report offers the depth required to navigate this environment. It provides the confidential segmentation data, the detailed regional breakdowns, and the proprietary analysis of competitive moves that public summaries cannot reveal. For executives preparing budgets, launching new lines, or considering M&A activity in the dairy and alternatives space, this intelligence is not just an asset; it is a necessity.
We invite you to access the complete study to unlock the full spectrum of data and strategic recommendations. The future of cheese—whether vegan or processed—will be defined by those who understand the nuances behind the numbers.
For detailed analysis of this topic, please visit the official page: Vegan Cheese and Processed Cheeses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bubble Tea Syrup Market Poised to Grow at a 7.45% CAGR Through 2032
By pmarketresearch, 2026-08-18
Bubble Tea Syrup Market 2026: Strategic Imperatives from PW Consulting's New Market Research Report
PW Consulting today releases its comprehensive market research brief on the global Bubble Tea Syrup market — an operationally focused intelligence product designed to inform executive decisions in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon (base year: 2025), the study quantifies a market that has expanded meaningfully over the past five years and is forecast to grow at a compound annual growth rate (CAGR) of 7.45% through 2032. All revenue figures in this release are expressed in USD Million; full time series and model access are available in the complete report.
Worldwide Radiation Imaging System Market
Why this report matters for 2026 decision-making
- The bubble tea syrup market is simultaneously mature in core geographies and highly dynamic in premium and convenience-driven channels; the 7.45% CAGR reflects structural demand plus premiumization tailwinds.
- Operational levers — raw-material sourcing, formulation, certification, and channel execution — drive near-term margin swings. Our analysis quantifies these levers and translates them into tactical playbooks.
- The market remains fragmented (CR3 ~22.4%; CR5 ~31.8%), creating a window for scale plays, distribution tie-ups, and targeted M&A in 2026.
What the PW Consulting report delivers (practical and executable)
- Transparent market-sizing methodology with downloadable forecast model (historical 2020–2025; forecast 2026–2032) so commercial teams can re-run scenarios with their own assumptions.
- Segment and channel frameworks that translate macro demand into SKU-level implications for R&D and procurement (regional footprints, product types, and applications are mapped—granular splits are published in the full report).
- Supply-chain diagnostics: supplier scorecards, ingredient cost pass-through models, and stress-tested contingency plans for sugar and fruit extract price volatility.
- Go-to-market playbooks for three priority strategies: branded expansion, private-label/white-label scaling, and foodservice anchoring — each with margin math, pricing ladders, and promotional templates.
- Regulatory and compliance checklists for North America and Europe (import testing, labeling, and certification pathways), plus templated documentation for HACCP/ISO/FDA/Halal approvals.
- Product innovation blueprints focused on reduced-sugar, natural/clean-label, and functional (e.g., adaptogen-infused) syrups — including formulation trade-offs and cost-to-produce matrices.
- M&A and partnership shortlist methodology: a repeatable framework to prioritize targets by capability (OEM/ODM, manufacturing location, certification set, and distribution reach).
- 90/180-day operational playbooks for procurement, commercial pilots, and channel rollouts — designed to turn insight into measurable KPIs within the first two quarters of execution.
Key market dynamics and operational consequences
Two non-negotiable dynamics shape 2026 strategy:
Textilene Market
- Raw-material exposure: syrup production is heavily dependent on sugar, fruit extracts, and natural flavors. Industry data and our primary interviews confirm that raw inputs represent a material share of manufacturing costs (commonly in the mid-40s to mid-50s percent range of OPEX). This concentration creates both margin risk and opportunity for procurement-led competitiveness.
- Regulatory and consumer sentiment: stricter food-safety requirements in North America and Europe, combined with a consumer shift toward reduced-sugar and clean-label formulations, mean that product compliance and transparent ingredient stories will be prerequisites for premium pricing.
For 2026, companies that proactively hedge raw-material exposure, validate product claims through recognized certifications, and reposition SKUs towards lower-sugar or functional formats will preserve margin and capture share as premiumization continues.
Worldwide Tinted Glass Market
Competitive landscape: tactical reads on core players
Our competitive analysis synthesizes public disclosures, trade-show activity, and product footprints for the market’s active B2B suppliers. Highlights:
- Sunnysyrup Food Co., Ltd. (Taiwan) — a long-established ingredient specialist offering concentrated juices, syrups, and full bubble tea ingredient portfolios with OEM/ODM capabilities. Recent trade-show participation (IFE London and TUTTOFOOD Milano in 2026) signals an intensified push into European foodservice and retail channels.
- Zonegoing Food (China) — positioned around bulk boba syrups and caramelized milk/brown sugar formats, with HACCP/ISO/FDA/Halal certifications. Their emphasis on certification and scale enables competitive access to institutional buyers.
- Fanale Drinks (Taiwan/USA) — differentiates on formulations containing a meaningful percentage of real fruit juice and pulp, targeting premium fruit-tea segments in blended and bottled formats.
- Bossen (USA; Taiwan/Asia sourcing) — a wholesale bridge for US operators, combining syrup supply with toppings and powder mixes; appeal is in breadth and distribution convenience.
- Qbubble (USA) — legacy wholesale supplier with training and consultation services; their value proposition is channel enablement as much as product supply.
- Inspire Food Company (Europe) — a regional leader focused on European distribution of syrups, pearls, and accessories; attractive for brands seeking an EU-compliant partner.
- Possmei (Taiwan) — integrated supplier of ingredients and equipment with US agent relationships; participation in the Winter Fancy Food Show (Jan 2026) underscores their North American channel ambitions.
- Yujie Food (China) — bulk syrup and cane sugar supplier, positioned for cost-sensitive, high-volume customers.
Implication for buyers and investors: suppliers now compete on a mix of formulation authenticity, certification breadth, training/consultation services, and global trade-show visibility. In 2026, strategic customers should prioritize suppliers that can deliver verified ingredient provenance and co-development capability at scale.
Recommended 2026 playbook for executives (prioritized and time-bound)
To convert market growth into sustainable profitability in 2026, PW Consulting recommends the following sequence.
- 0–90 days (stabilize & prioritize)
- Run the embedded forecast model against your SKU portfolio to identify top- and bottom-quartile products by margin under three raw-material price scenarios.
- Secure dual-sourcing for sugar and core fruit extracts; negotiate indexed contracts with trigger thresholds to share short-term risk with suppliers.
- Audit regulatory readiness for key export markets (NA/EU) and commence documentation for any outstanding certifications.
- 90–180 days (test & pilot)
- Launch a pilot SKU series for reduced-sugar and a single functional syrup (e.g., adaptogen- or vitamin-enriched) to evaluate price elasticity and margin sensitivity.
- Implement supplier scorecards and supplier-financing options to thin cost volatility and accelerate raw-material visibility.
- 180–365 days (scale & lock)
- Execute channel expansion prioritized by profitability and regulatory ease: accelerate rollouts where certification timelines are shortest and margin potential highest.
- Pursue one strategic partnership or tuck-in acquisition to shore up either OEM/ODM capability, certification depth, or regional distribution — guided by our M&A shortlist methodology.
Scenario planning: three outcomes to model now
- Base case — steady premiumization plus logistics normalization yields continued mid-single-digit CAGR consistent with our published 7.45% forecast.
- Upside — faster substitution to natural, low-sugar, and functional formulations drives accelerated ASPs and mix-improvement; premium suppliers and innovators capture above-market returns.
- Downside — protracted raw-material inflation and non-tariff regulatory barriers compress margins; price-sensitive channels (high-volume QSR) hurt fastest and favor vertically integrated or low-cost suppliers.
Where PW Consulting’s report intentionally stops — and why
Following our “trailer” principle, this release demonstrates the analytical depth and operational frameworks contained in the full report while withholding the granular regional/application monetary splits and SKU-level unit economics that make the report immediately executable for commercial teams. Those detailed tables, partner-ready templates, and editable forecast models are included in the full PW Consulting market package and are available through our distribution portal.
Final note — how to use this intelligence
For commercial heads, procurement leads, and corporate development teams planning 2026 action, the report is a decision acceleration tool: it converts market growth projections, supplier capability mapping, and regulatory realities into a prioritized action plan with measurable milestones. Whether your aim is to launch a reduced-sugar portfolio, negotiate more resilient raw-material contracts, scale private-label production, or evaluate M&A targets, the operational roadmaps and model-driven scenarios in this study are designed to shorten time-to-impact.
To access the complete dataset, downloadable models, and supplier scorecards (including the full regional and application splits), visit the PW Consulting report page. The granular intelligence you need to execute in 2026 is in the full report; this release is your strategic preview.
For detailed analysis of this topic, please visit the official page: Bubble Tea Syrup Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com